

August delivered a partial rebound from July’s AI-driven pull back: the Philadelphia Semiconductor Index (SOX Index) recovered 2.0% and the Nasdaq 100 rose 4.2%. The broader market pushed further ahead, with the S&P 500 Index gaining 2.7% and most sectors ending the month in positive territory. Software outperformed semiconductors for the second straight month, suggesting a broadening of the AI trade.
There was no FOMC meeting in August but all eyes were on new Fed chair Kevin Warsh’s first Jackson Hole address on August 28. Warsh struck a hawkish tone, noting the Fed “may have work to do” on inflation. At the 15–16 September meeting, the FOMC voted unanimously—12–0—to lift the target range by 25 basis points to 3.75%–4.00%.
Global equity
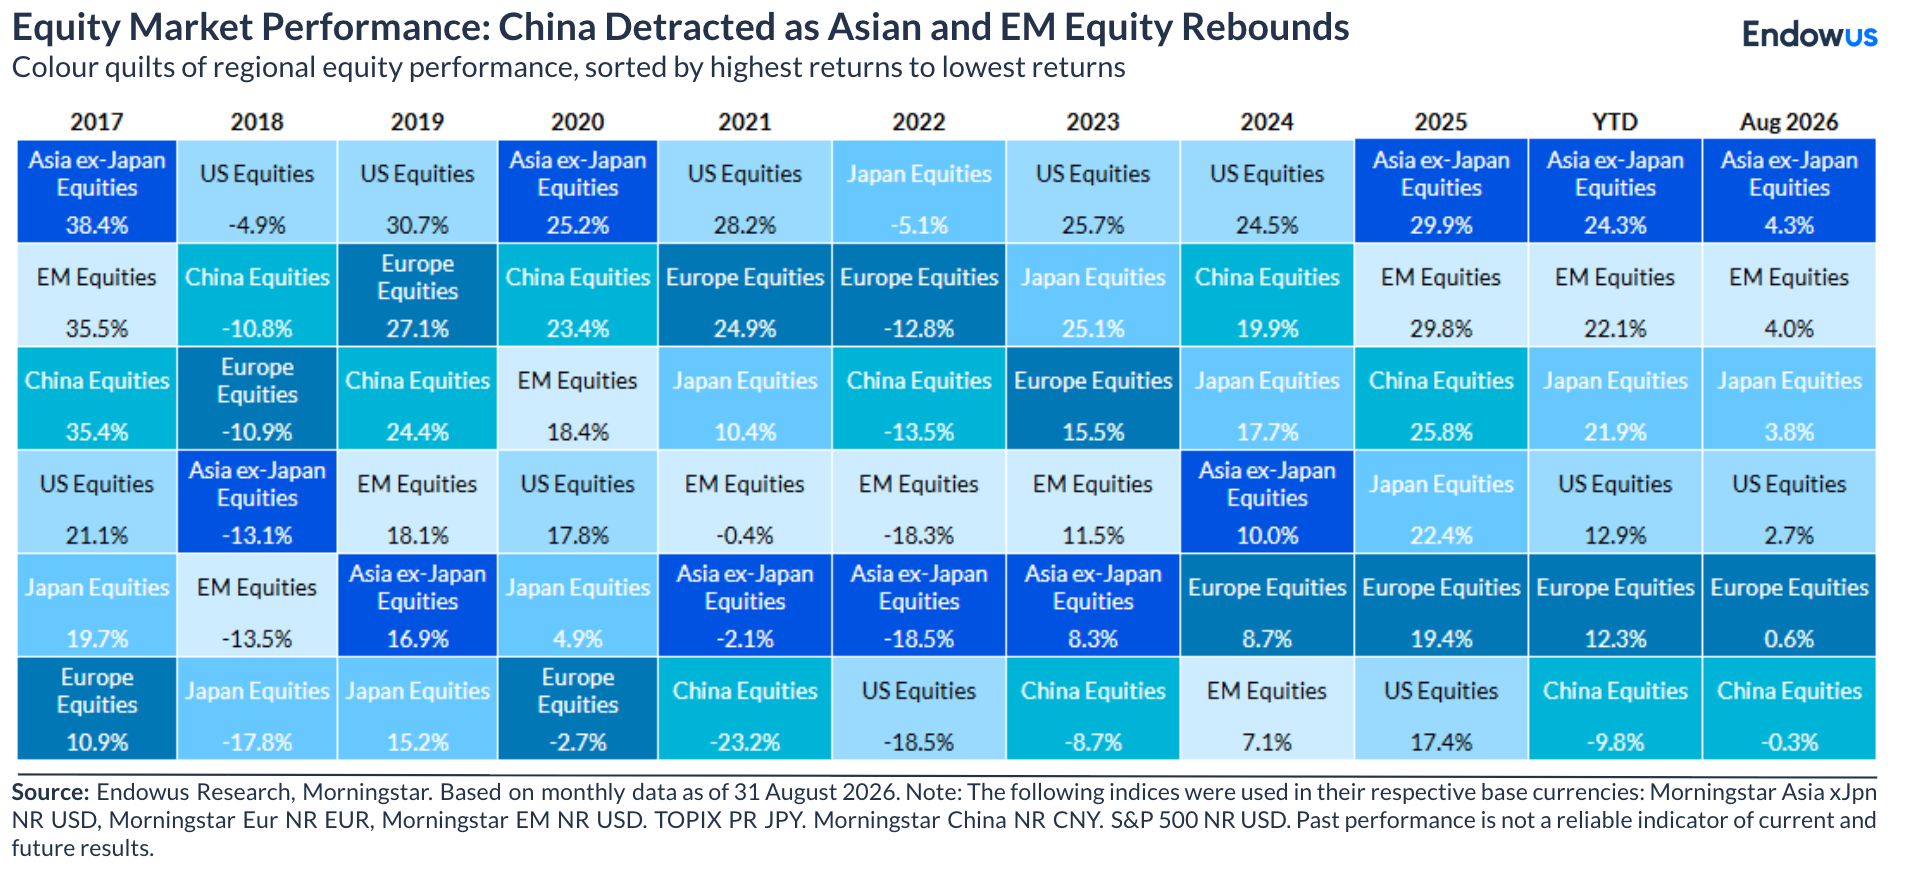
Global equities advanced 2.8% in USD terms in August, a broad-based recovery after July’s flat print. Growth reasserted itself over value in August (the Russell 1000 Growth Index was up 3.7%, while the Russell 1000 Value Index only rose 1.9%), reversing the more than 8 percentage point July underperformance.
Regional performance (in USD) was largely a reversal of July, with Taiwan rebounding sharply by 9.1% after July’s 7.8% drop. Korea also gained 8.8% after the 16.2% pull back in July. In contrast, HK-listed Chinese equities (HSCEI), July’s top regional performer, gave back 1.1% as the rally proved short-lived against soft domestic demand data.
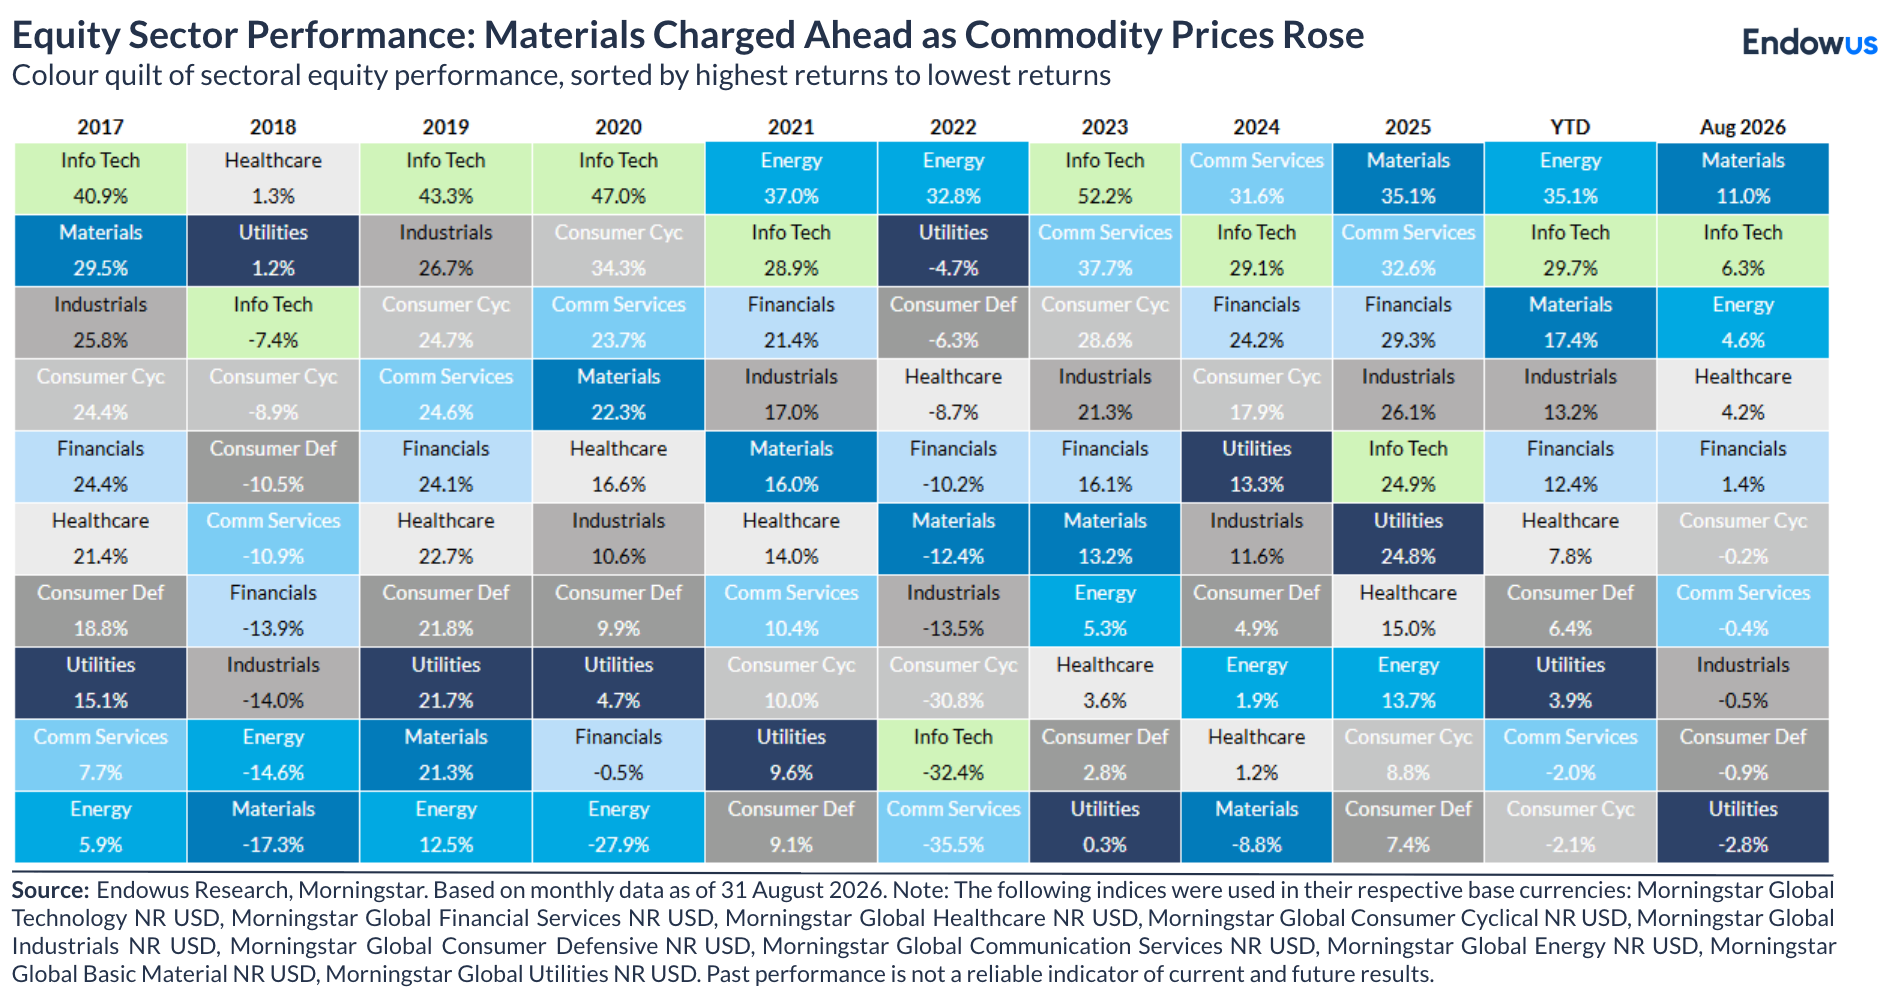
On a sector basis, energy continued to be strong. However, it was joined by materials, technology and healthcare, highlighting a broadening rally. Consumer staples, utilities and industrials lagged.
Global fixed income
Fixed income markets were considerably calmer compared to July’s selloff, also due to a mid-month intervention by the US Treasury, whose effects were, however, short-lived. By month-end, Warsh’s hawkish Jackson Hole remarks had reversed much of that move at the short end with the 2-year yield jumping on the news. The 10-year treasury finished August at roughly 4.75% its highest close since January 2025 and modestly above July’s 4.73%
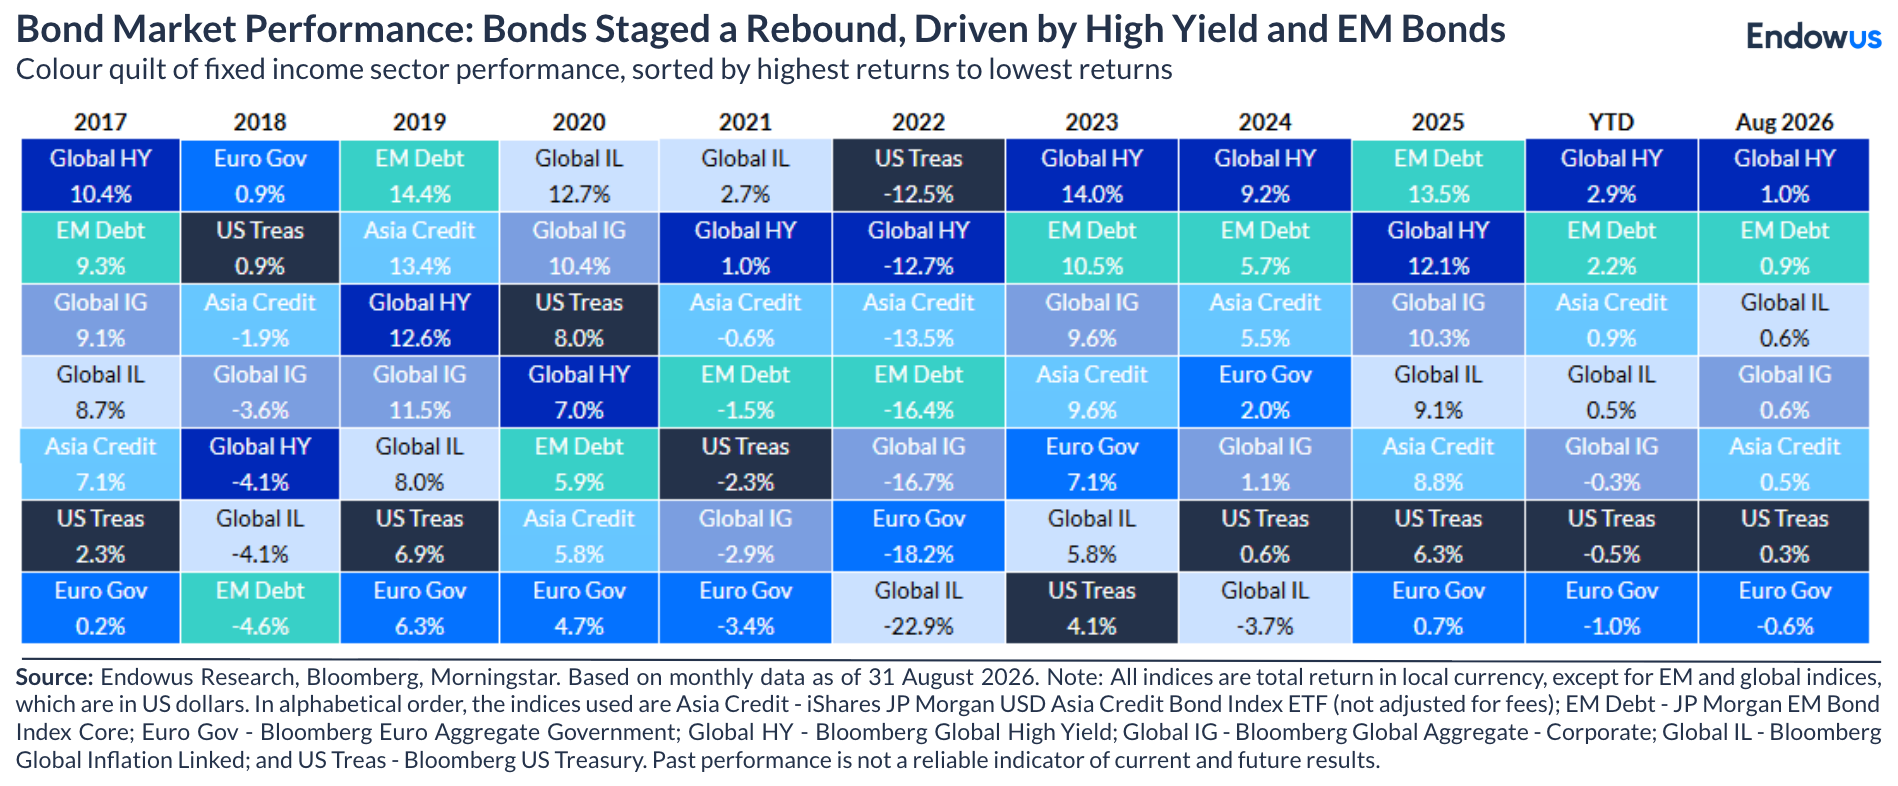
The Bloomberg Global Aggregate (unhedged on a USD basis) rose 0.5% in August, an improvement from its 0.5% and 0.7% decline in July and June, respectively. Global and US high yield led as spreads narrowed and emerging market debt also outperformed, though buying has become more selective after a strong run. Core government bond yields outside the US continued to grind higher with the German 10-year Bund rising 12 bps to 3.32% and Japan’s 10-year JGB rising 14bps to a multi-decade high of 2.94%.
Commodities
Commodities extended their run as the best-performing asset class for a second consecutive month with the Bloomberg Commodity Index (BCOM) up 7.1% (+29% YTD). Gold was the standout, surging 9.7% to end August near USD4,437 and in positive territory YTD.
Oil was comparatively subdued after July’s round trip volatility. Brent held mostly in an $87-95/barrel range (except earlier in the month) through August, ending the month near $91, as the Strait of Hormuz standoff between the US and Iran remained unresolved.
Note: Figures in this article are based on Morningstar and Bloomberg data.
Disclaimer
Risk Warnings
Investment involves risk. Past performance is not an indicator nor a guarantee of future performance. The value of investments and the income from them can go down as well as up, and you may not get the full amount you invested.
Opinions
Whilst Endowus HK Limited (“Endowus”) has tried to provide accurate and timely information, there may be inadvertent delays, omissions, technical or factual inaccuracies or typographical errors.
Any forward-looking statements, prediction, projection or forecast on the economy, stock market, bond market or economic trends of the markets contained in this material are subject to market influences and contingent upon matters outside the control of Endowus and therefore may not be realised in the future. Further, any opinion or estimate is made on a general basis and subject to change without notice. In presenting the information above, none of Endowus, its affiliates, directors, employees, representatives or agents have given any consideration to, nor have made any investigation of the objective, financial situation or particular need of any user, reader, any specific person or group of persons. Therefore, no representation is made as to the completeness and adequacy of the information to make an informed decision. You should carefully consider (i) whether any investment views and products/ services are appropriate in view of your investment experience, objectives, financial resources and relevant circumstances.
o invitation or solicitation
Neither the information, nor any opinion, contained in this article constitutes a promotion, recommendation, solicitation, invitation or offer by Endowus or its affiliates to buy or sell any securities, collective investment schemes or other financial instruments or services, nor shall any such security, collective investment scheme, or other financial instruments or services be offered or sold to any person in any jurisdiction in which such offer, solicitation, purchase, or sale would be unlawful under the securities laws of such jurisdiction. This is not intended to be an invitation or offer made to the public to subscribe for any financial product or other transaction.
This advertisement has not been reviewed by the Securities and Futures Commission or any regulatory authority in Hong Kong.