

The original version of this article first appeared in The Business Times.
For most of 2026, the market's working assumption was that the Federal Reserve's next move would be a cut. As recently as April, a Reuters poll of economists had the Fed on hold until September and then easing. Traders positioned for it, strategists wrote around it, and investors tilted towards it. Another reminder of why forecasting is a dangerous profession and potentially a costly one.
Then, on Sept 16, the Fed raised rates instead—its first in more than three years. Fed Chair Warsh was blunt: inflation is too high and has been for too long with higher oil prices. By early October, the 10-year US Treasury yield had climbed to around 5.3 per cent, near its highest level in more than two decades.
The interesting part is not the 0.25 per cent increase. It is how confidently the consensus had drifted the other way before it.
Professional forecasters, with every data feed available to them, still get the direction of the next rate move wrong often enough that building a portfolio around "what the Fed will do next" is literally a “bet”.
Behavioural economists call this overconfidence, and its costs are well documented. A Morningstar study found that over the 10 years to end-2024, the average active US fund manager underperformed their benchmarks by around 1.2 per cent per year that led to a total difference of roughly 15 per cent of total returns, which came largely from buying and selling at the wrong times.
The cost of being wrong twice, first repositioning for the predicted move and then unwinding when it does not arrive, compounds too in the wrong direction.
It’s not just about the Fed
There is a second reason to be humble about trying to get the rate call right. The Fed sets only the overnight rate. The long end of the yield curve is set by the market, and the market is being asked to absorb a great deal more than Treasury bills.
Much of the commentary attributes the rise in long-dated yields to rising rate expectations driven by inflation. That is part of the story. There has also been a wave of debt being issued to fund the artificial intelligence build-out.
Alphabet, Amazon, Meta, Microsoft and Oracle had issued around US$220 billion of bonds by mid-August this year, roughly three times what they raised in all of 2025. Because data centres are expected to last for decades, much of this debt is long-dated. Amazon’s US$25 billion deal in July stretched to 2066, and it had to offer around 20 basis points of extra yield. Investor orders per dollar of hyperscaler bonds fell from almost five times in February to under two by July.
Long-dated corporate bonds and Treasuries compete for the same pool of patient capital: pension funds, insurers and other liability-matching buyers. When a few of the world's largest companies arrive with hundreds of billions of 30- and 40-year paper, every borrower at the long end, including the US government, sees a crowding out effect and has to pay more to clear the market. That is called the term premium.
The Fed's own Kim-Wright model attributes about 60 per cent of the 10-year yield's rise over the past year to the term premium rather than to expected policy rates. The New York Fed's model sees far less. That two respected models disagree so sharply itself says a lot. Experts cannot even agree on why yields moved. Predicting where they go next is harder still.
When everyone hates bonds
Admittedly, the past five years have been one of the most difficult stretches for bonds in the 50-year history of the Bloomberg US Aggregate bond index, with its first-ever negative rolling five-year return. There is a growing chorus that is naming bonds as the most hated asset class right now maybe together with private credit.
That is precisely when the evidence is worth revisiting. Historical empirical studies clearly show that for high-quality bonds, the single best predictor of future returns is not the Fed, the economy or the consensus. It is the starting yield. Since 1976, the US Aggregate Bond Index shows a 0.94 correlation between starting yield and annualised returns over the following five years. Vanguard's work on 10-year Treasuries over three decades shows the same: starting yield and subsequent 10-year returns track each other closely.
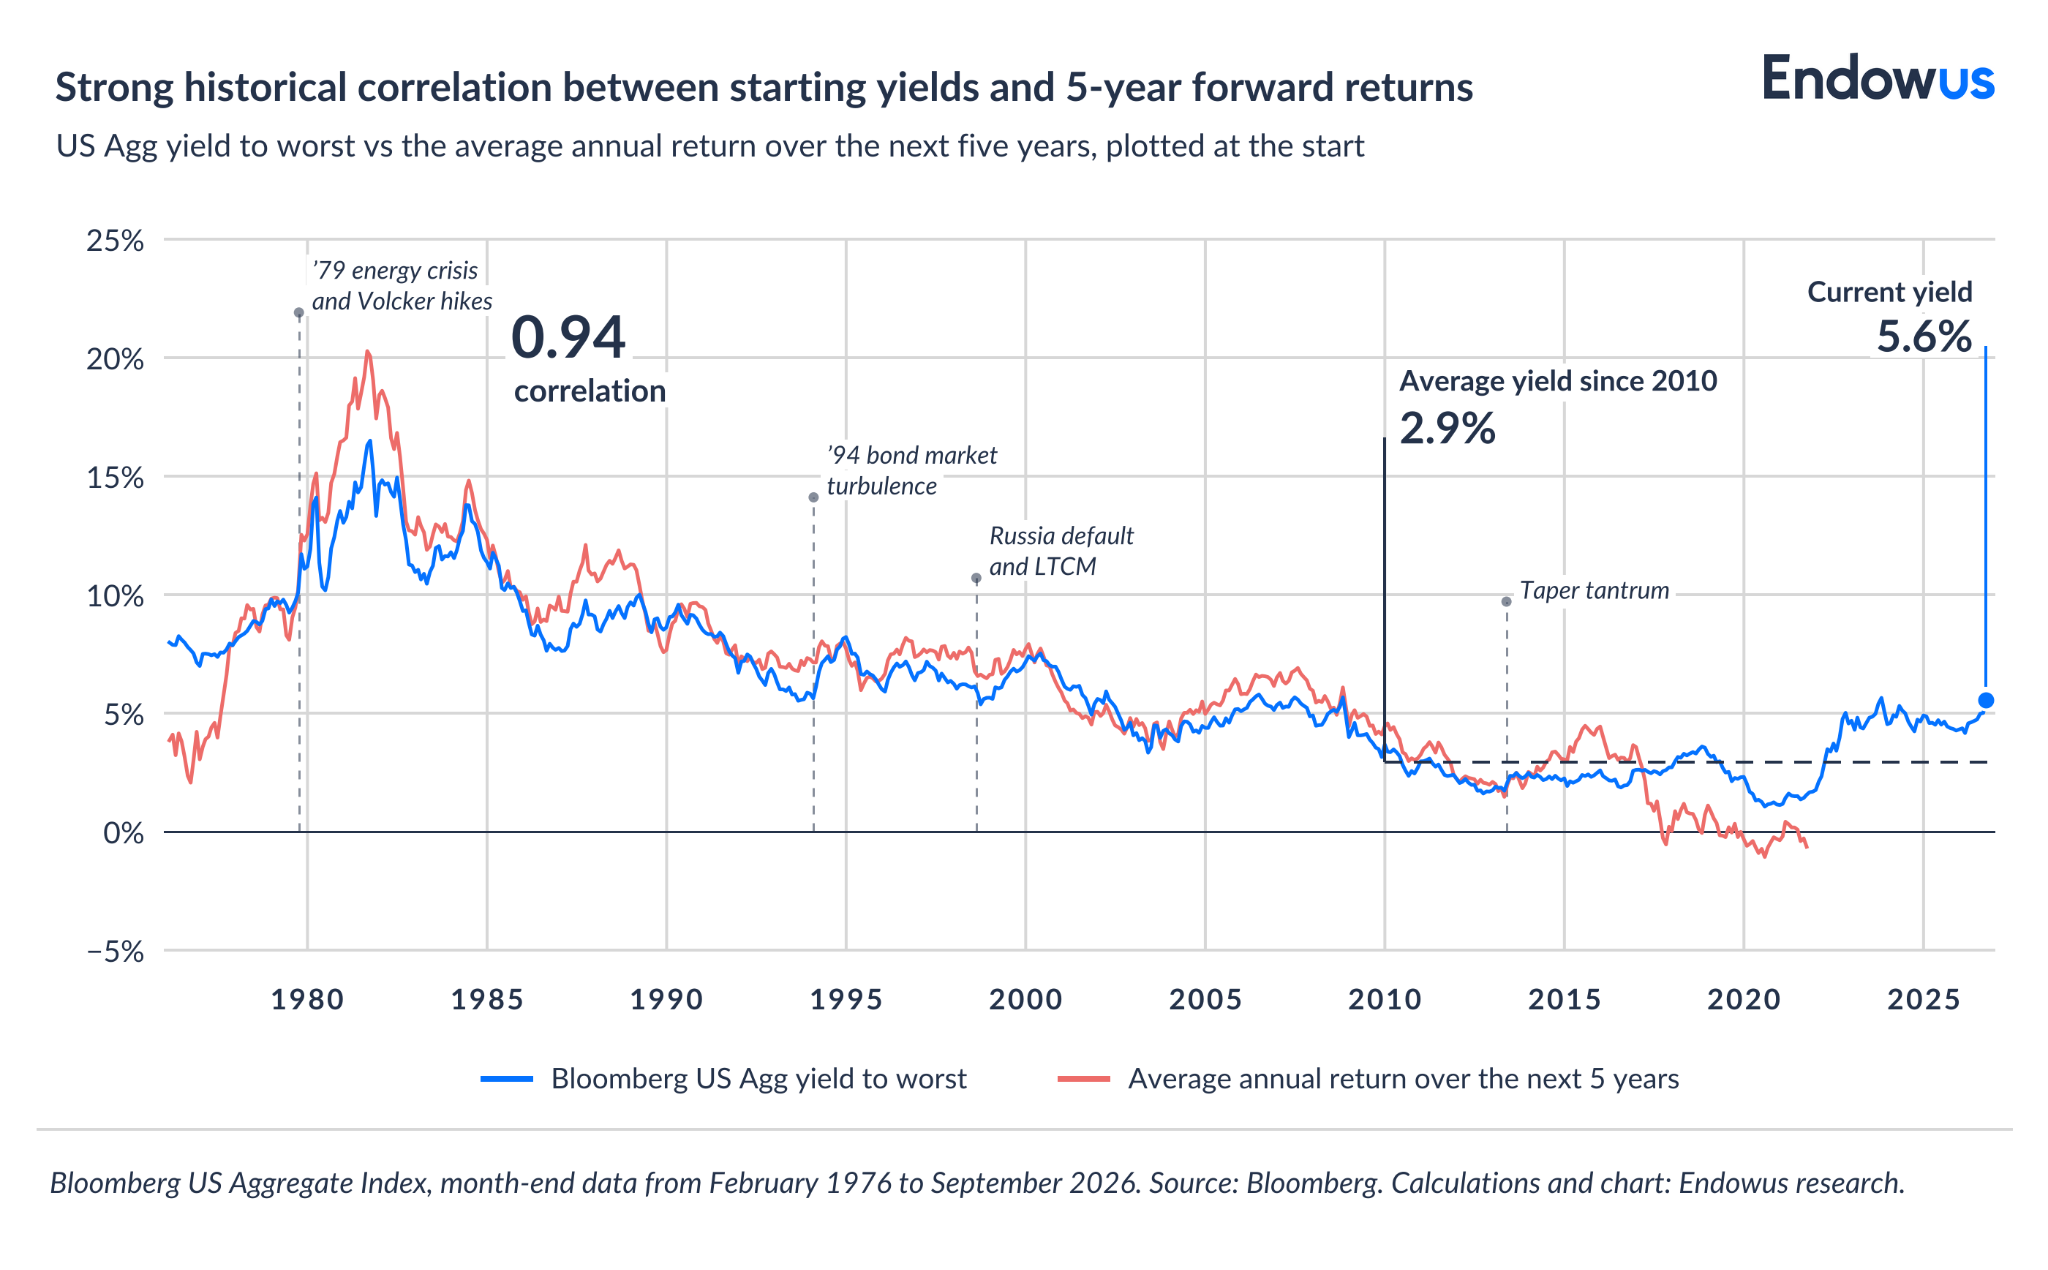
Five years ago, investors were paid under 2 per cent to own high-quality bonds and bore all the risk of rising rates. Today, the starting yield is around 5 per cent, with a meaningful cushion against further price falls.
In more than three decades of investing, I have found that the moments when an asset class is most universally disliked have rarely been the worst time to own it.
The difference between 2022 and now is that the upside on rates is much smaller and inflation is lower and we are much further along the growth cycle. But the reason for holding bonds has not changed even if it has disappointed many. It would still need to be an asset that would soften the blow of equities through drawdowns, and the source of predictable income for those nearing or in retirement.
A good fiduciary advisor does a handful of unglamorous things: builds a globally diversified portfolio at low cost, matches bond exposure to your actual goals and horizon rather than to the latest Fed headline, and looks at your multiple pots of money together rather than in silos. An advisor without conflict also helps you rebalance into the asset class everyone is fleeing, when instinct says the opposite.
The Fed surprised the consensus this time. It may do so again. The science of wealth is not an exception—no one can predict the future. The starting point for bonds is generous and the diversification benefits remain relevant. When and not if, equities eventually sees a wobble, as it inevitably will based on history, the diversification benefit will be needed most at a time we cannot predict.
Disclaimer
Risk Warnings
Investment involves risk. Past performance is not an indicator nor a guarantee of future performance. The value of investments and the income from them can go down as well as up, and you may not get the full amount you invested. Rates of exchange may cause the value of investments to go up or down.
This article is not intended to be relied upon as a forecast or research or investment advice, and should not form the basis of any investment or other decisions. The information contained herein is not intended, and should not be construed, as any legal, tax, regulatory, accounting or financial advice. If you would like investment, accounting, tax or legal advice, you should consult with your own professional advisors regarding your individual circumstances and needs.
The information in this article may not be suitable for all investors. You are responsible for any action that you take or decision that you make in reliance on any content in this article, and you agree that Endowus HK Limited (“Endowus”) is not liable under any circumstances.
No invitation or solicitation
Neither the information, nor any opinion, contained in this article constitutes a recommendation, offer or solicitation by Endowus or its affiliates to you to buy or sell any securities, collective investment schemes or other financial instruments or services, nor shall any such security, collective investment scheme, or other financial instruments or services be offered or sold to any person in any jurisdiction in which such offer, solicitation, purchase, or sale would be unlawful under the securities laws of such jurisdiction.
This is not intended to be an invitation or offer made to the public to subscribe for any financial product or to enter into any transaction.
Accuracy of Information
Whilst Endowus has made reasonable efforts to provide accurate and timely information, there may be inadvertent delays, omissions, technical or factual inaccuracies or errors in any such information. Endowus does not warrant or represent that the information in this article is correct, accurate or reliable.
Opinions
Any opinion or estimate above is made on a general basis and none of Endowus, nor any of its affiliates, representatives or agents have given any consideration to nor have made any investigation of the objective, financial situation or particular need of any user, reader, any specific person or group of persons. Opinions expressed herein are subject to change without notice.
Any forward-looking statements, prediction, projection or forecast on the economy, stock market, bond market or economic trends of the markets contained in this article are subject to market influences and contingent upon matters outside the control of Endowus and therefore may not be realised in the future.
In presenting the information above, none of Endowus, its affiliates, directors, employees, representatives or agents have given any consideration to, nor have made any investigation of the objective, financial situation or particular need of any user, reader, any specific person or group of persons. Therefore, no representation is made as to the completeness and adequacy of the information to make an informed decision. You should carefully consider whether any investment views and products/ services are appropriate in view of your investment experience, objectives, financial resources and relevant circumstances.
This article has not been reviewed by the Securities and Futures Commission of Hong Kong.