

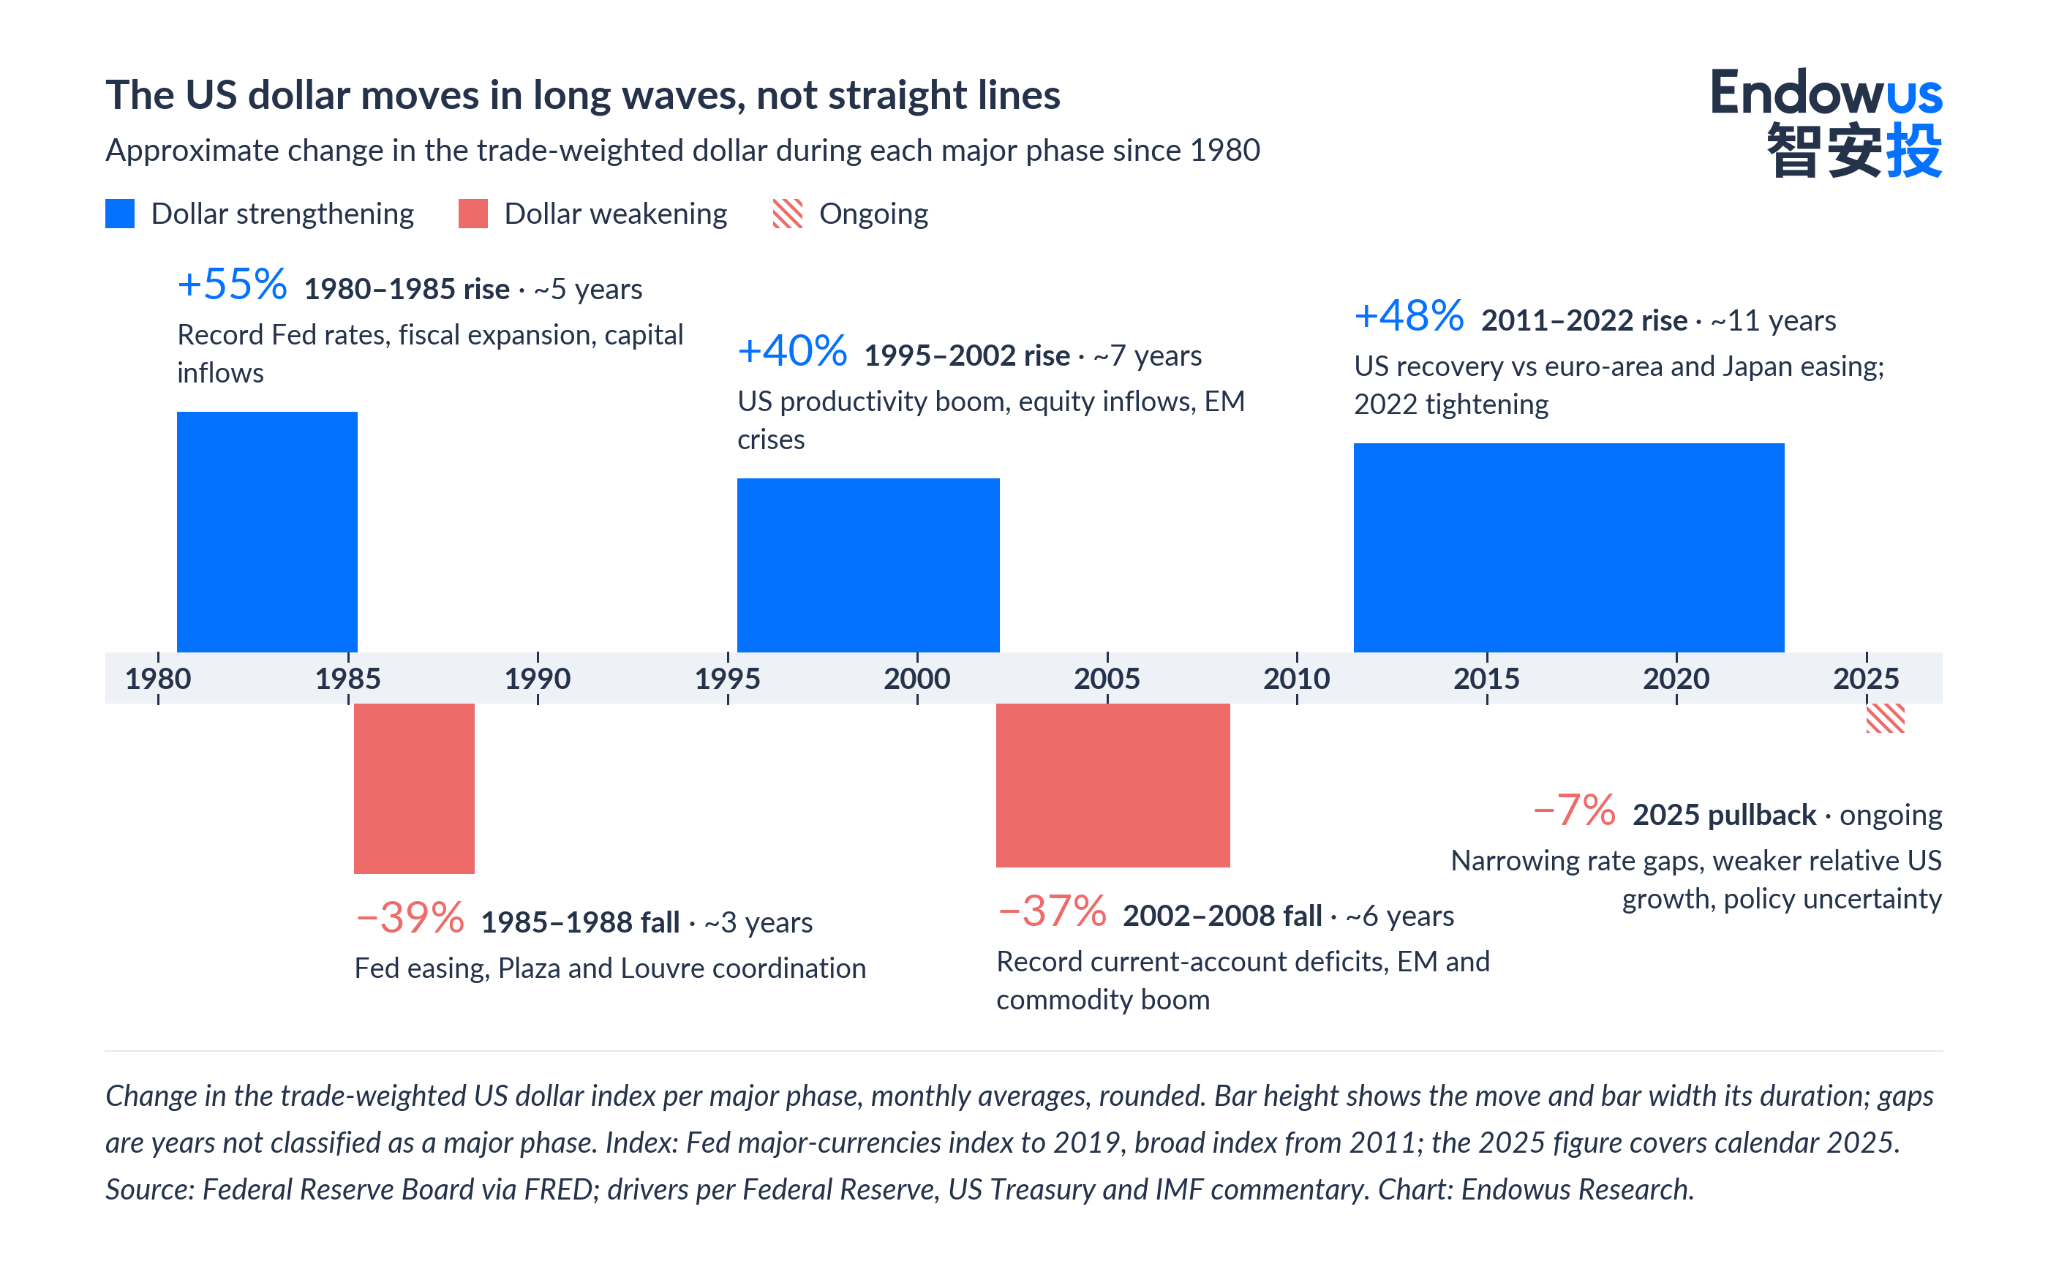
- Since 1980 the trade-weighted dollar has moved in three broad multi-year rising phases and three falling phases, each of roughly 35% to 55% on Federal Reserve data, a fairly large source of return variation.
- The euro is 57.6% of the widely quoted dollar index (DXY), so most of DXY’s movements are actually dollar-euro FX moves. An additional finding is that a stronger dollar tightens financial conditions across emerging markets.
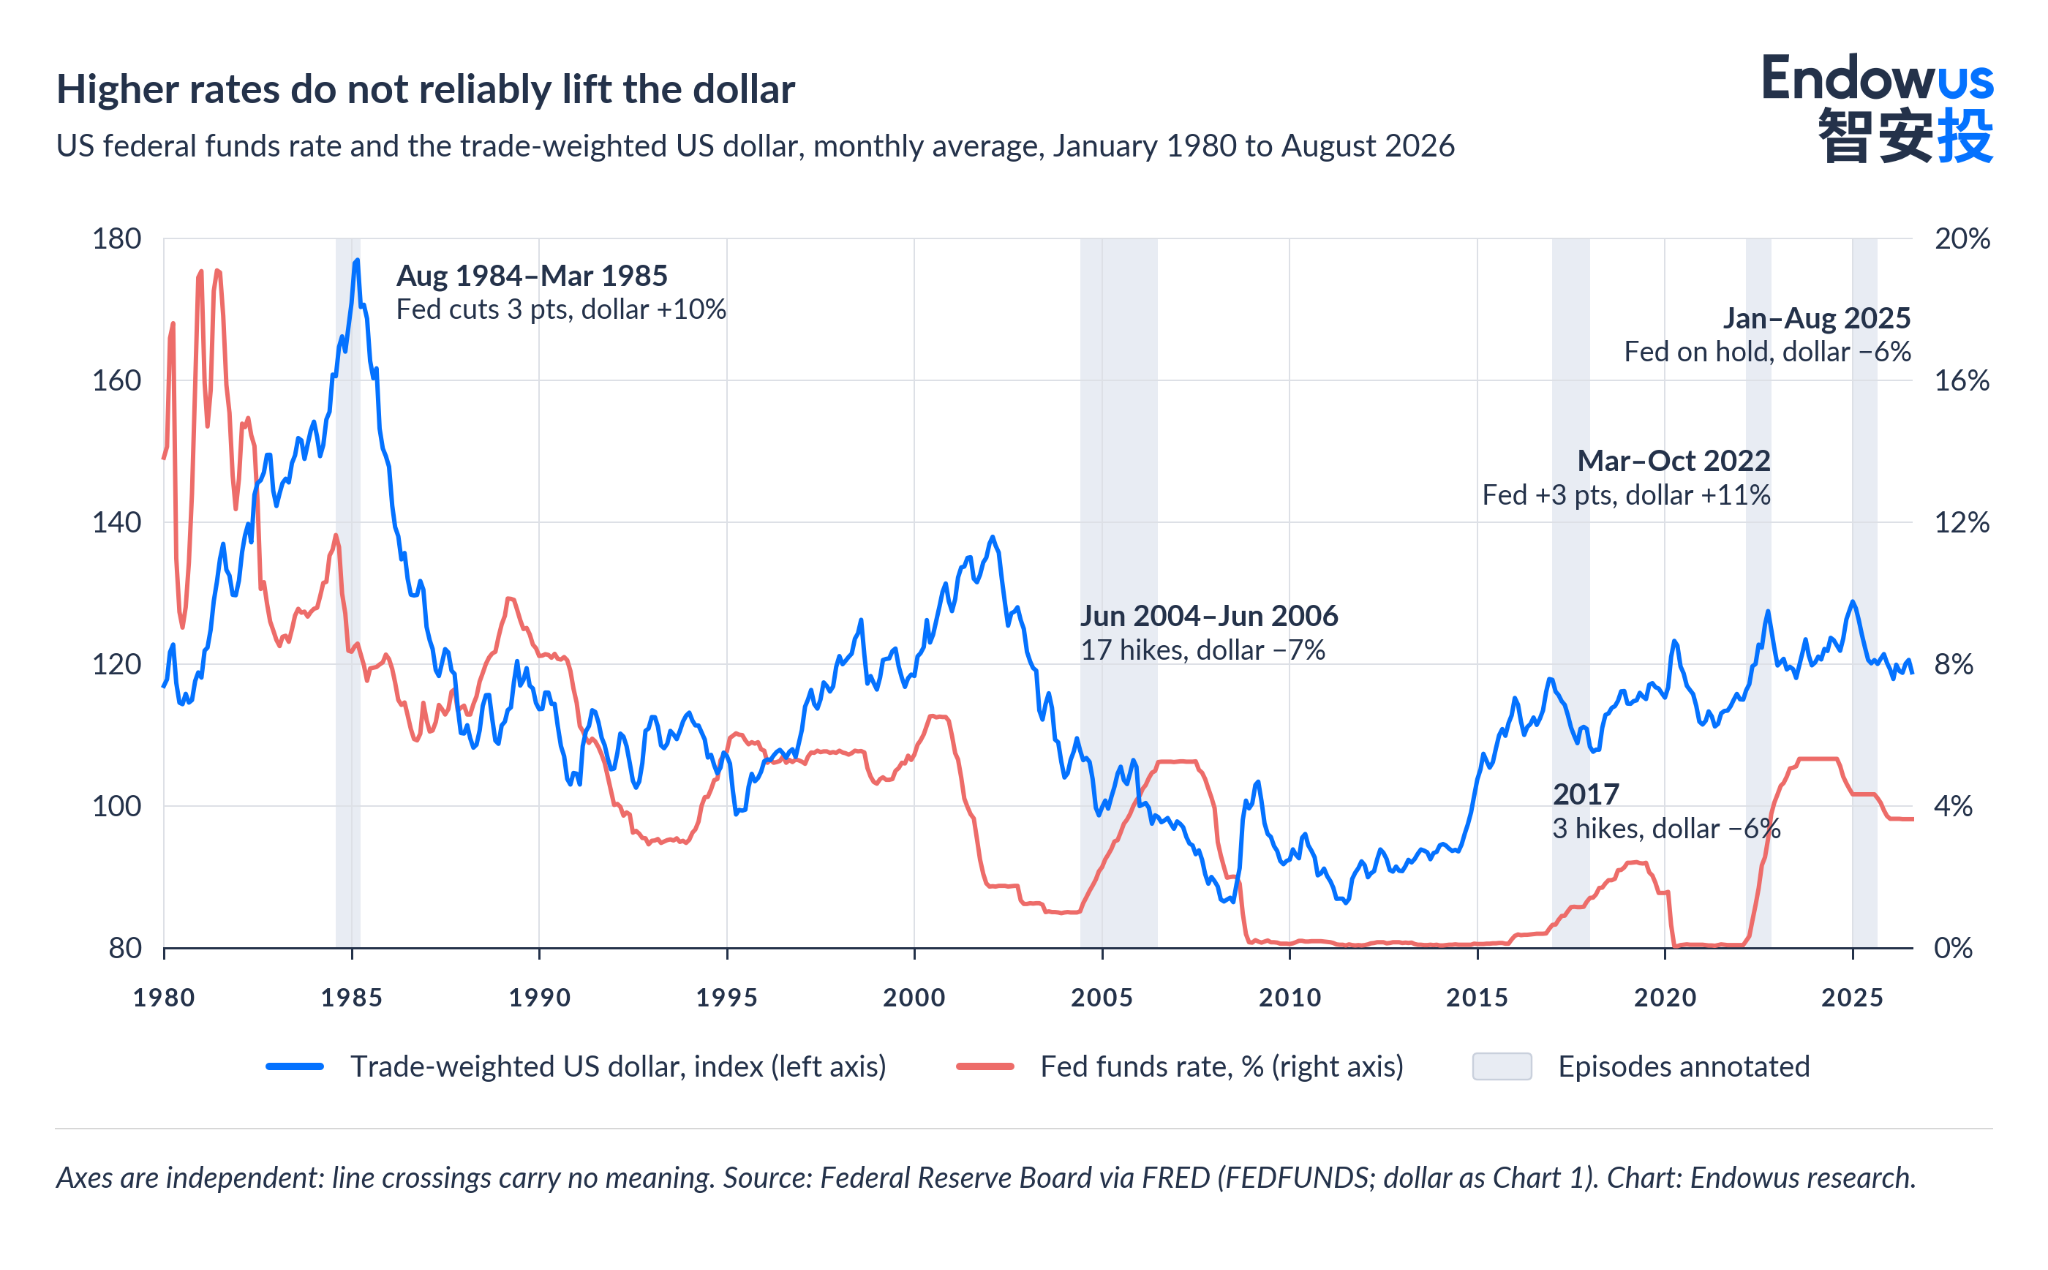
- Interest rates have an impact on dollar strength, but the channel is not always straightforward. The dollar has risen after US rates peaked, fallen through multi-year hiking cycles, and, in 2025, weakened while the Federal Reserve was on hold.
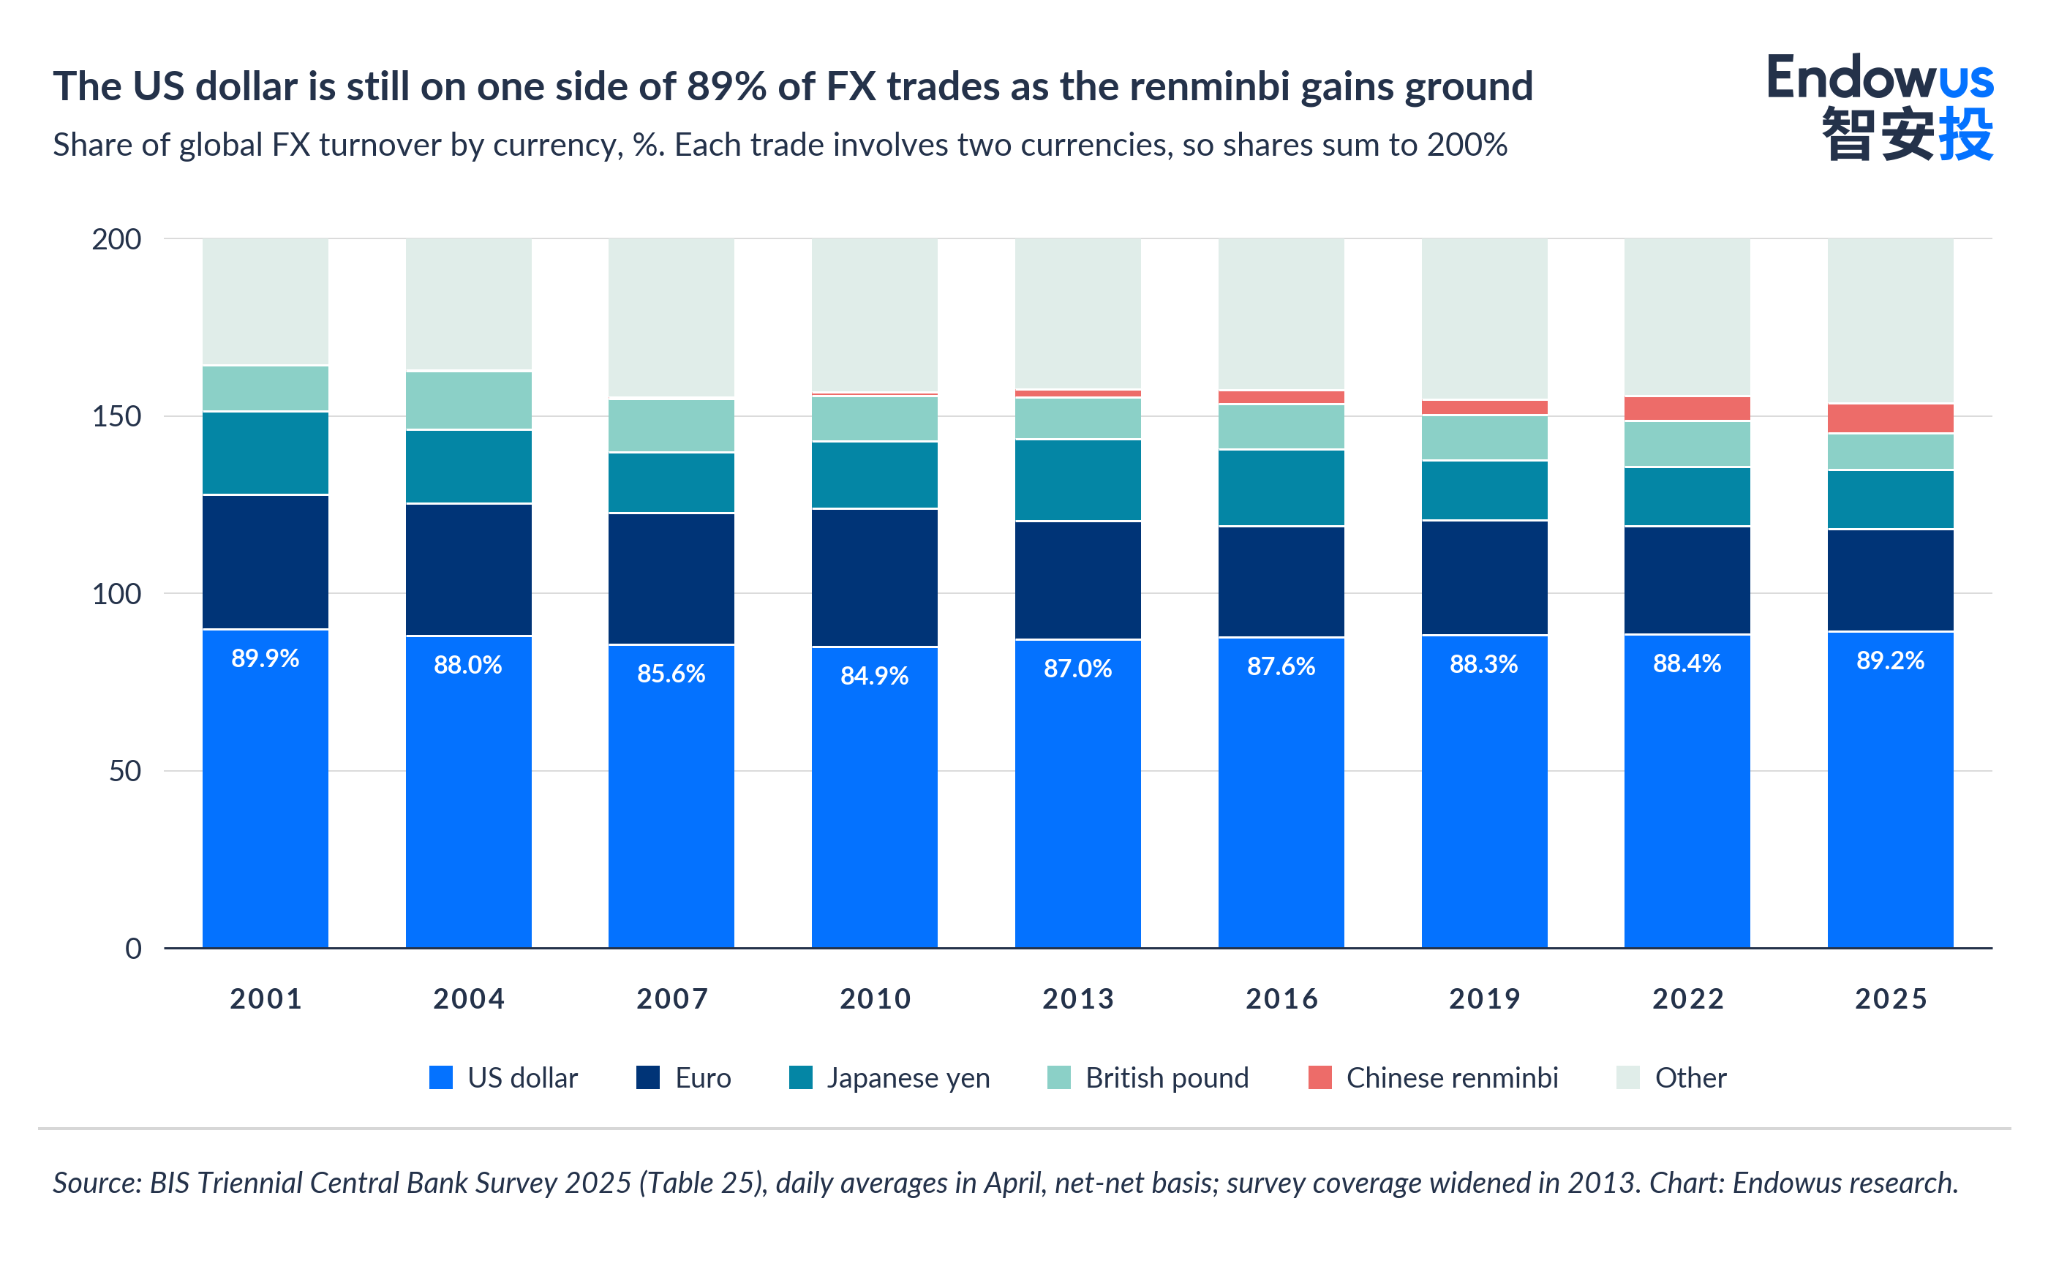
The US dollar underpins much of the global financial system. It denominates roughly half of all cross-border bank loans and international debt securities, prices most commodities, and sits on either side of the majority of the world's currency transactions. When the dollar strengthens or weakens across a multi-year cycle, the consequences reach well beyond the United States into the euro, into the borrowing costs of emerging economies, and into the returns of a globally diversified portfolio.
This article’s goal is to identify and explain long-term dollar move cycles, which can have an impact on the performance of other currencies - the euro first and foremost, and beyond that, other developed and emerging market currencies.
The main point here is that US interest rates explain only part of the picture. A wider US rate advantage has, against the foundational theory of uncovered interest rate parity (UIP), often supported the dollar, but the link is loose and changes over time. The dollar has climbed while rates fell, weakened while the Federal Reserve raised them, and responded to growth, risk appetite, and policy credibility at least as much as to the yield gap between the US and other countries.
The practical conclusion is that forecasting the cycle is a tall order, and some of the best analysts and chief economists often miss the mark. Most importantly, rate differentials are not necessarily a predictor of dollar moves.
The analysis draws on four decades of Federal Reserve data and on research from the Bank for International Settlements (BIS), the International Monetary Fund (IMF), as well as academic literature. It traces the major cycles since 1980, explains why the euro and emerging-market currencies tend to be correlated and mirror the dollar, examines what interest rates do and do not account for, and closes with the implications for portfolio construction and currency hedging.
The dollar moves in long cycles
Evidence from historical data shows that the dollar broadly moves in long cycles of appreciation and depreciation.
We’ve looked at two different indices, two gauges of the dollar exchange rate with other currencies.
- The ICE US Dollar Index (DXY) is more narrow. It is a fixed-weight basket of six currencies whose composition has changed only once, in January 1999, when the euro replaced its predecessor currencies (but without deviating from their collective weight). The DXY is the most utilized proxy for US dollar strength. Futures and options on the DXY trade on the Intercontinental Exchange (ICE), and the index updates in real time. That makes it the most widely used gauge of US dollar strength in markets and financial media.
- The Federal Reserve's trade-weighted broad dollar index, which covers 26 economies (including China, Mexico, and other emerging markets), is a more comprehensive signal. Its weights are updated annually to reflect US trade flows. The Federal Reserve publishes the index (which is not traded), and economists and policymakers use it to assess how the dollar affects US trade, inflation and global financial conditions.
Looking at the trade-weighted dollar, we can clearly recognize alternating rising and falling phases, each lasting around five to seven years, with the amplitude of a full swing typically between 35% and 55%. Past performance is not necessarily a guide to future performance or returns, but the regularity of the cycle across very different macro regimes is difficult to dismiss.
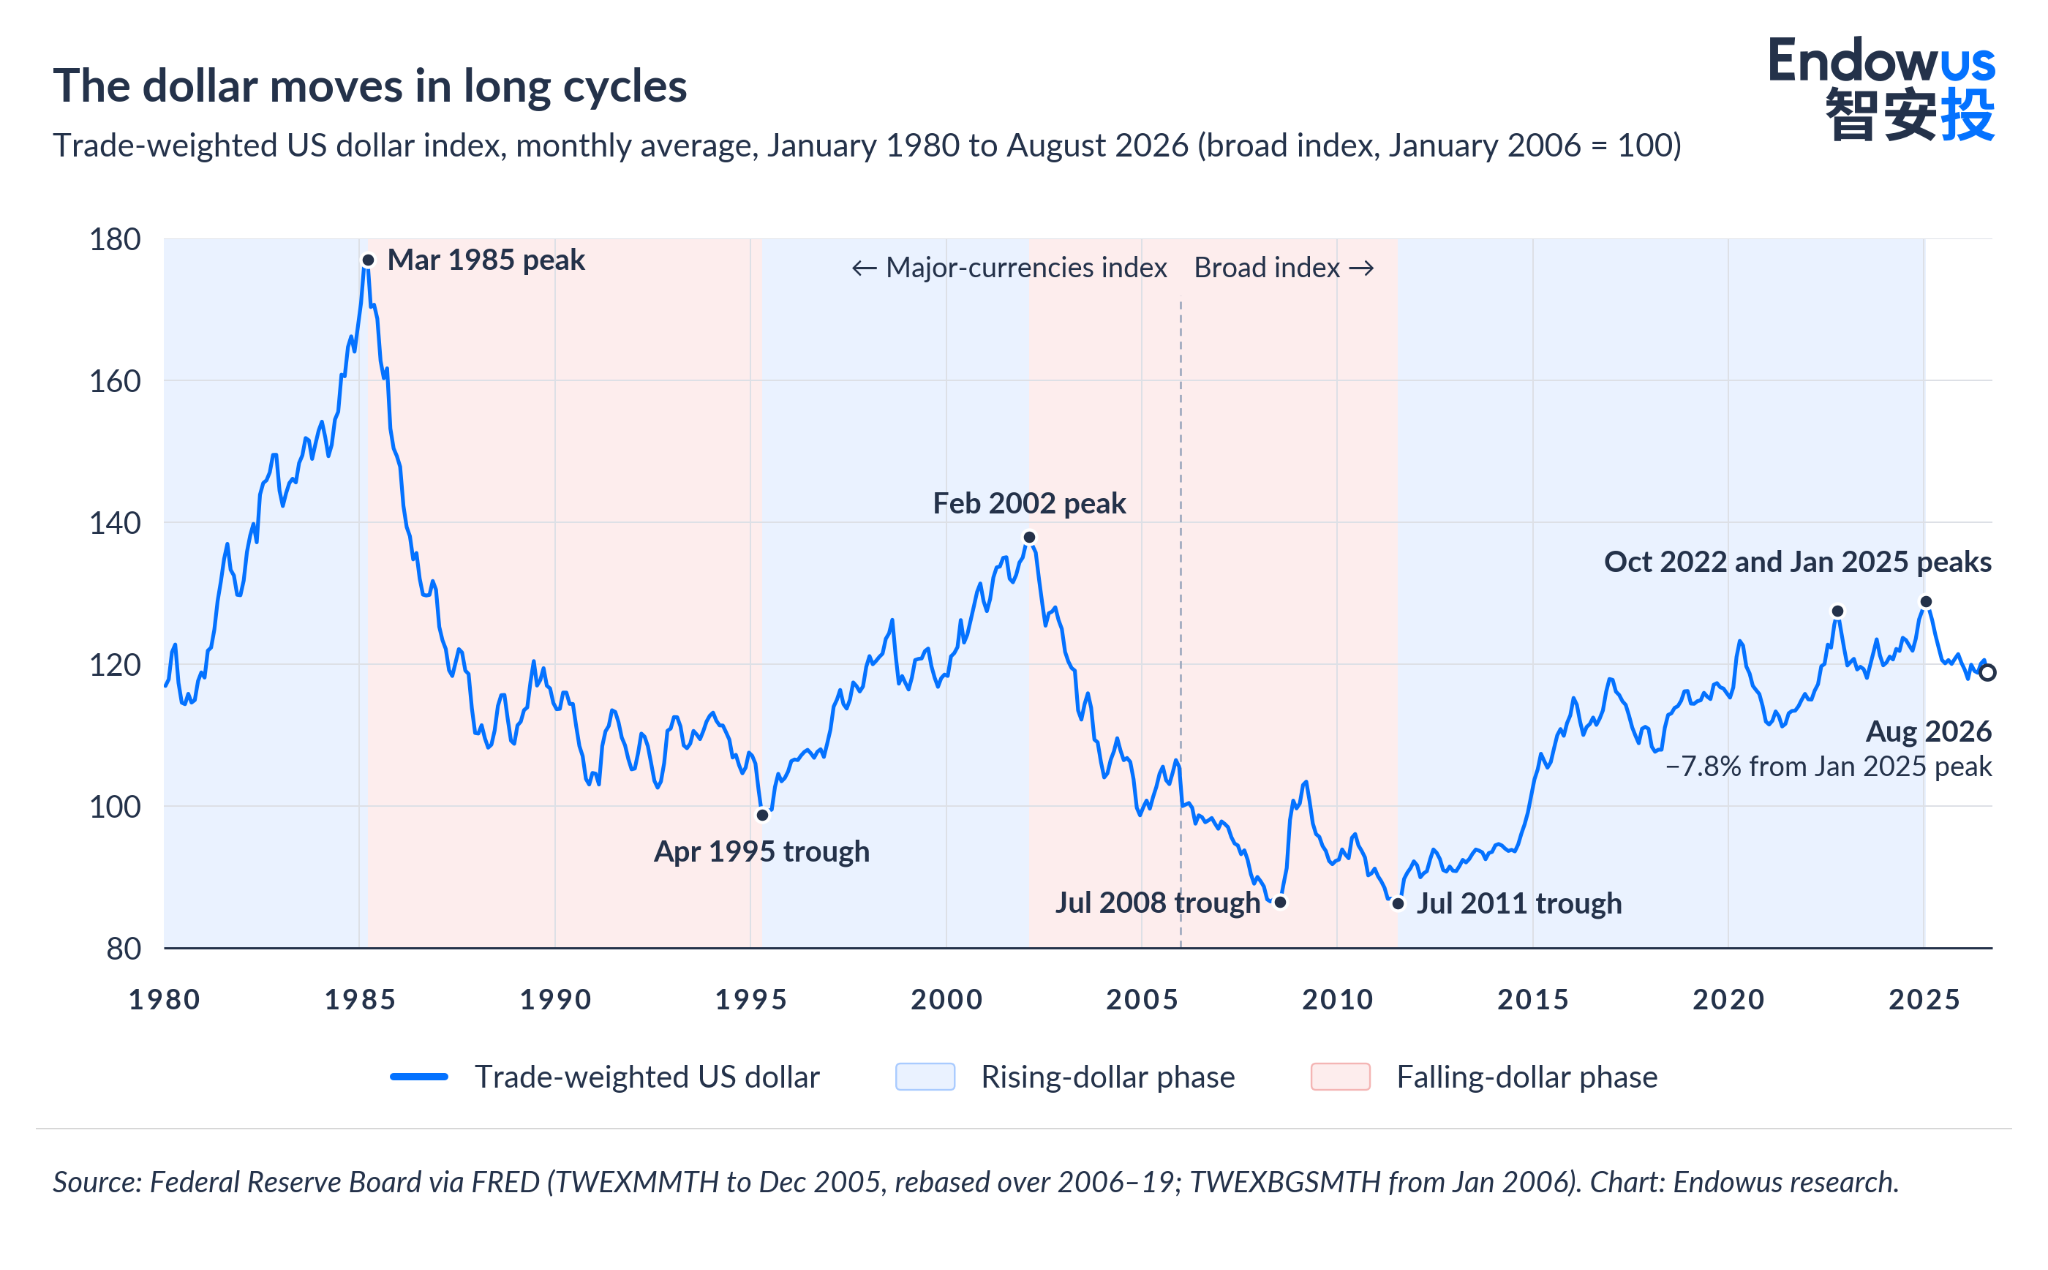
The surge of the early 1980s coincided with Chair Paul Volcker’s Federal Reserve pushing policy rates to record highs, a large US fiscal expansion, and heavy capital inflows (which increased the demand for dollars). The decline that followed the 1985 peak began after the Fed started easing, and post the coordinated intervention of the Plaza Accord in September 1985 (“...some further orderly appreciation of the main non-dollar currencies is desirable…” - Paragraph 18 of the Plaza Accord), later stabilised at the Louvre Accord in February 1987 (“...They agreed to cooperate closely to foster stability of exchange rates around current levels…”)
The dollar bottomed in April 1995 (within weeks of US Treasury Secretary Robert Rubin articulating what became the "strong dollar" policy) then rose through the late-1990s productivity boom and through the US turning fiscal deficit into surplus, peaking in early 2002. The long slide to 2008 tracked record US current-account deficits (primarily led by post-9/11 foreign policy and, namely, the Iraq war) and a commodity-led emerging-market boom.
The most recent phase has been an unusually long cycle. On the broad index, the dollar appreciated for more than a decade from 2011, with some interruptions, reaching its highest monthly readings in late 2022 and again in early 2025 before falling back through 2025 and 2026. In reality, the inflation-adjusted broad dollar also reached a series high in January 2025, so this was a genuine appreciation rather than a nominal artefact. The episode shows that cycles can run longer and further than any single driver would predict.
The effect on the euro
Much of what is described as "dollar strength" is, arithmetically, also euro weakness (and the reverse). The euro carries a 57.6% weight in the DXY, so a 1% move in the euro against the dollar shifts the index by roughly 0.58% in the opposite direction before any other currency moves. The most-quoted barometer of the dollar is therefore, to a first approximation, an inverted chart of the euro.
The Fed's broad index dilutes this by giving the euro a smaller weight and adding China, Mexico, and other economies, which is one more reason the two measures can tell slightly different stories.
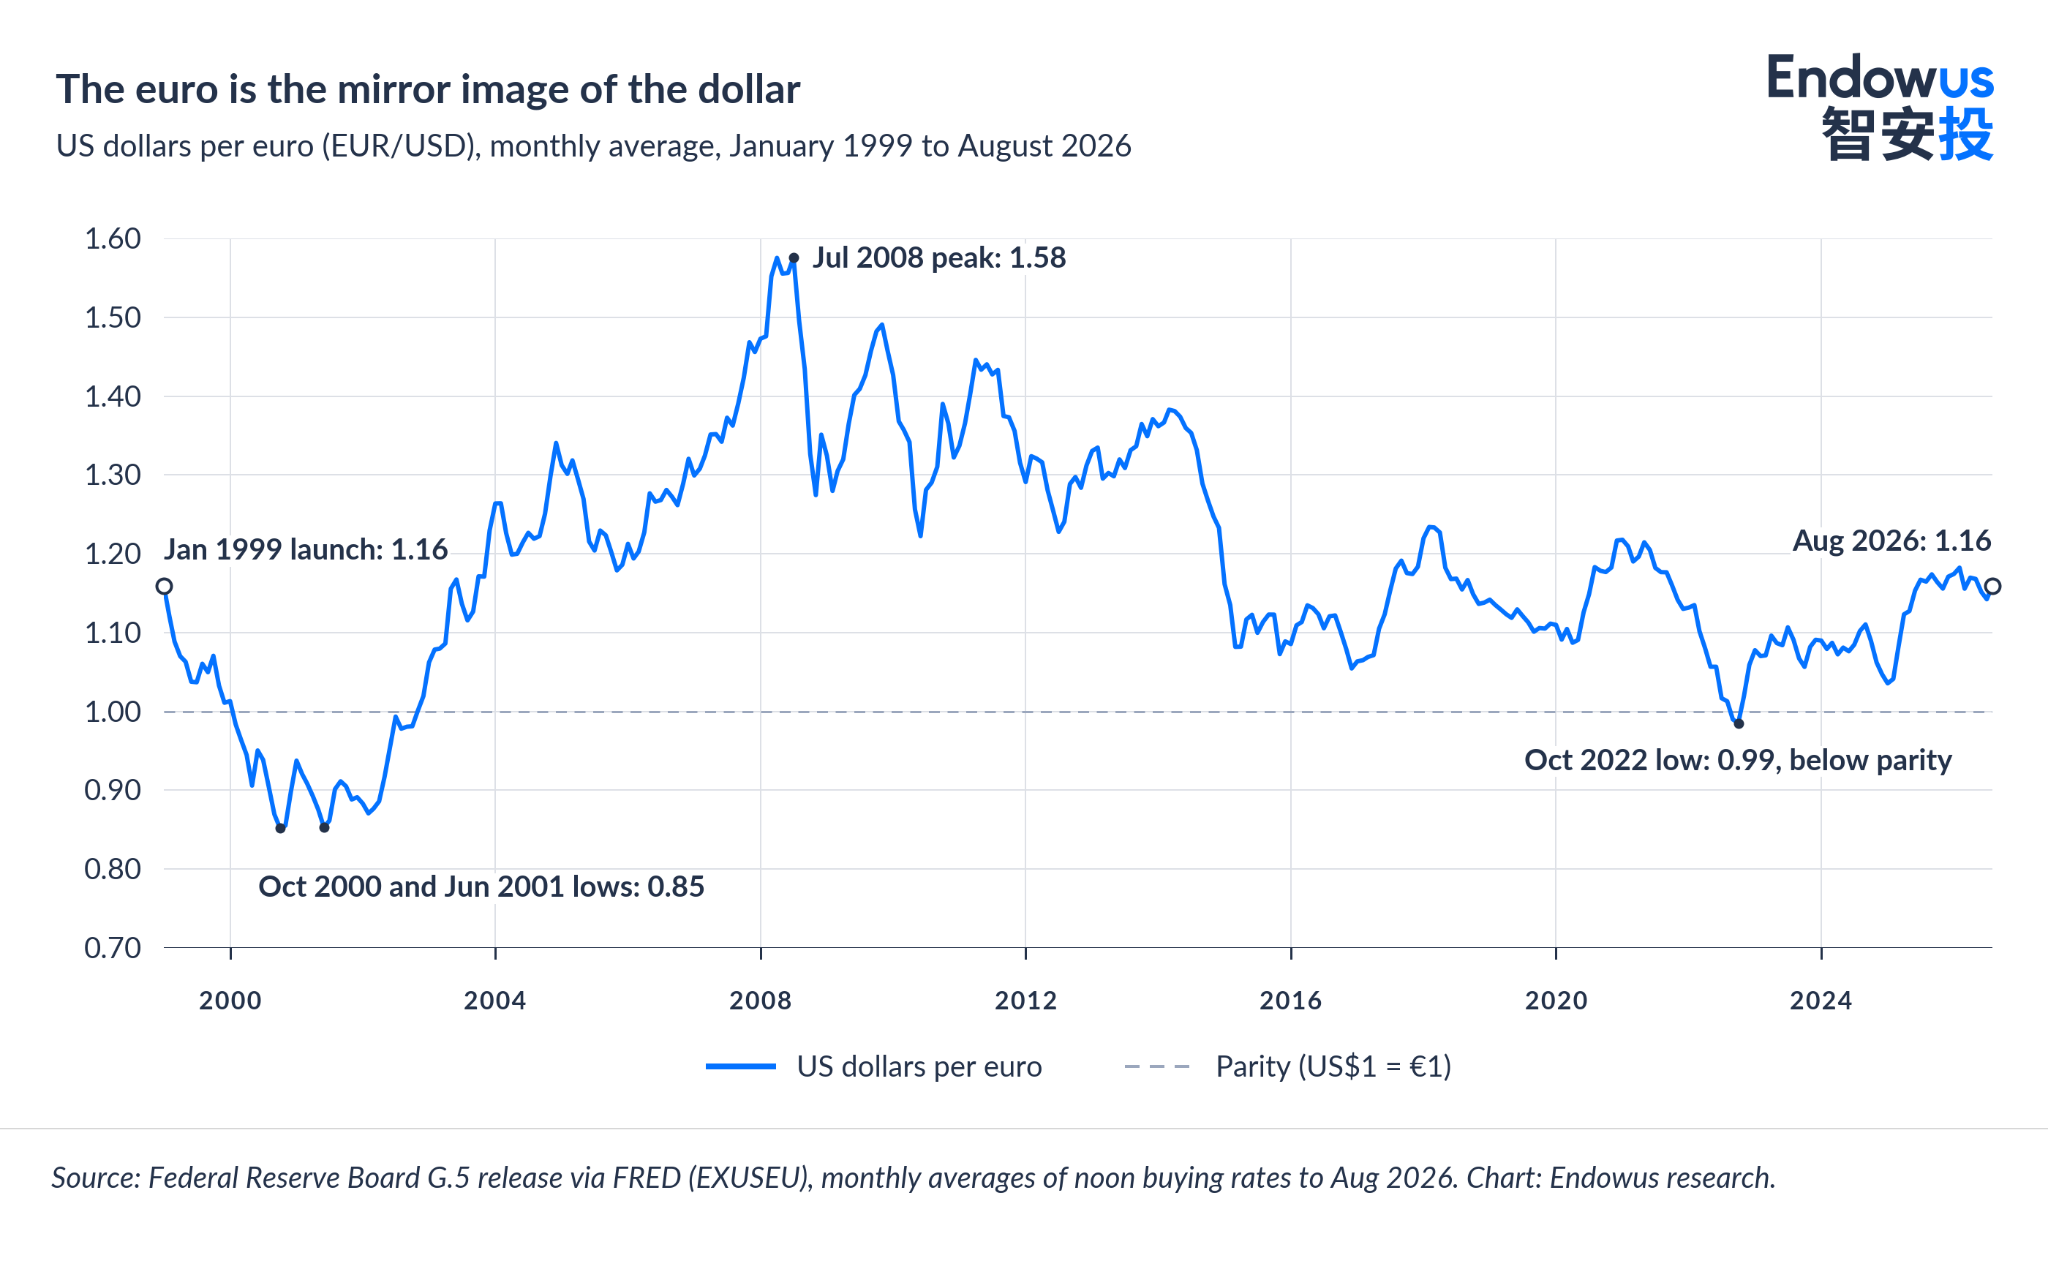
The euro launched near US$1.16 in January 1999, fell to about US$0.85 in 2000, and climbed to roughly US$1.58 in 2008 before the swings of the eurozone sovereign-debt crisis. It traded below parity in October 2022 and had recovered to around US$1.16 by August 2026. Reading this chart alongside the dollar cycle makes the mirror relationship easier to understand.
There is, however, a distinction between broad dollar moves and euro-specific moves. In the first quarter of 2025, the Federal Reserve Bank of New York attributed a decline in the dollar against the euro to narrowing interest-rate differentials, a weaker outlook for US growth relative to Europe, and uncertainty over US trade policy — a broad dollar story that happened to run through the euro. Other episodes were euro-specific: the currency's 2010–2012 weakness reflected the euro-area sovereign-debt crisis, and its softness in early 2026 reflected the region's exposure to an energy-price shock rather than any change in the dollar itself.
For an investor, the difference determines whether a move is likely to extend across other currencies or remain limited to the euro-dollar pair.
Euro dollar index and usd index comparison
A stronger dollar tightens the world's financial conditions
Whether dollar strength or weakness impacts emerging market currencies (beyond the euro) is extremely important.
Textbook trade theory suggests a stronger dollar should help emerging-market exporters by making their goods cheaper; in practice, the financial channel tends to dominate, and a strong dollar tightens financial conditions in EM, typically causing a squeeze in lending amidst capital outflows.
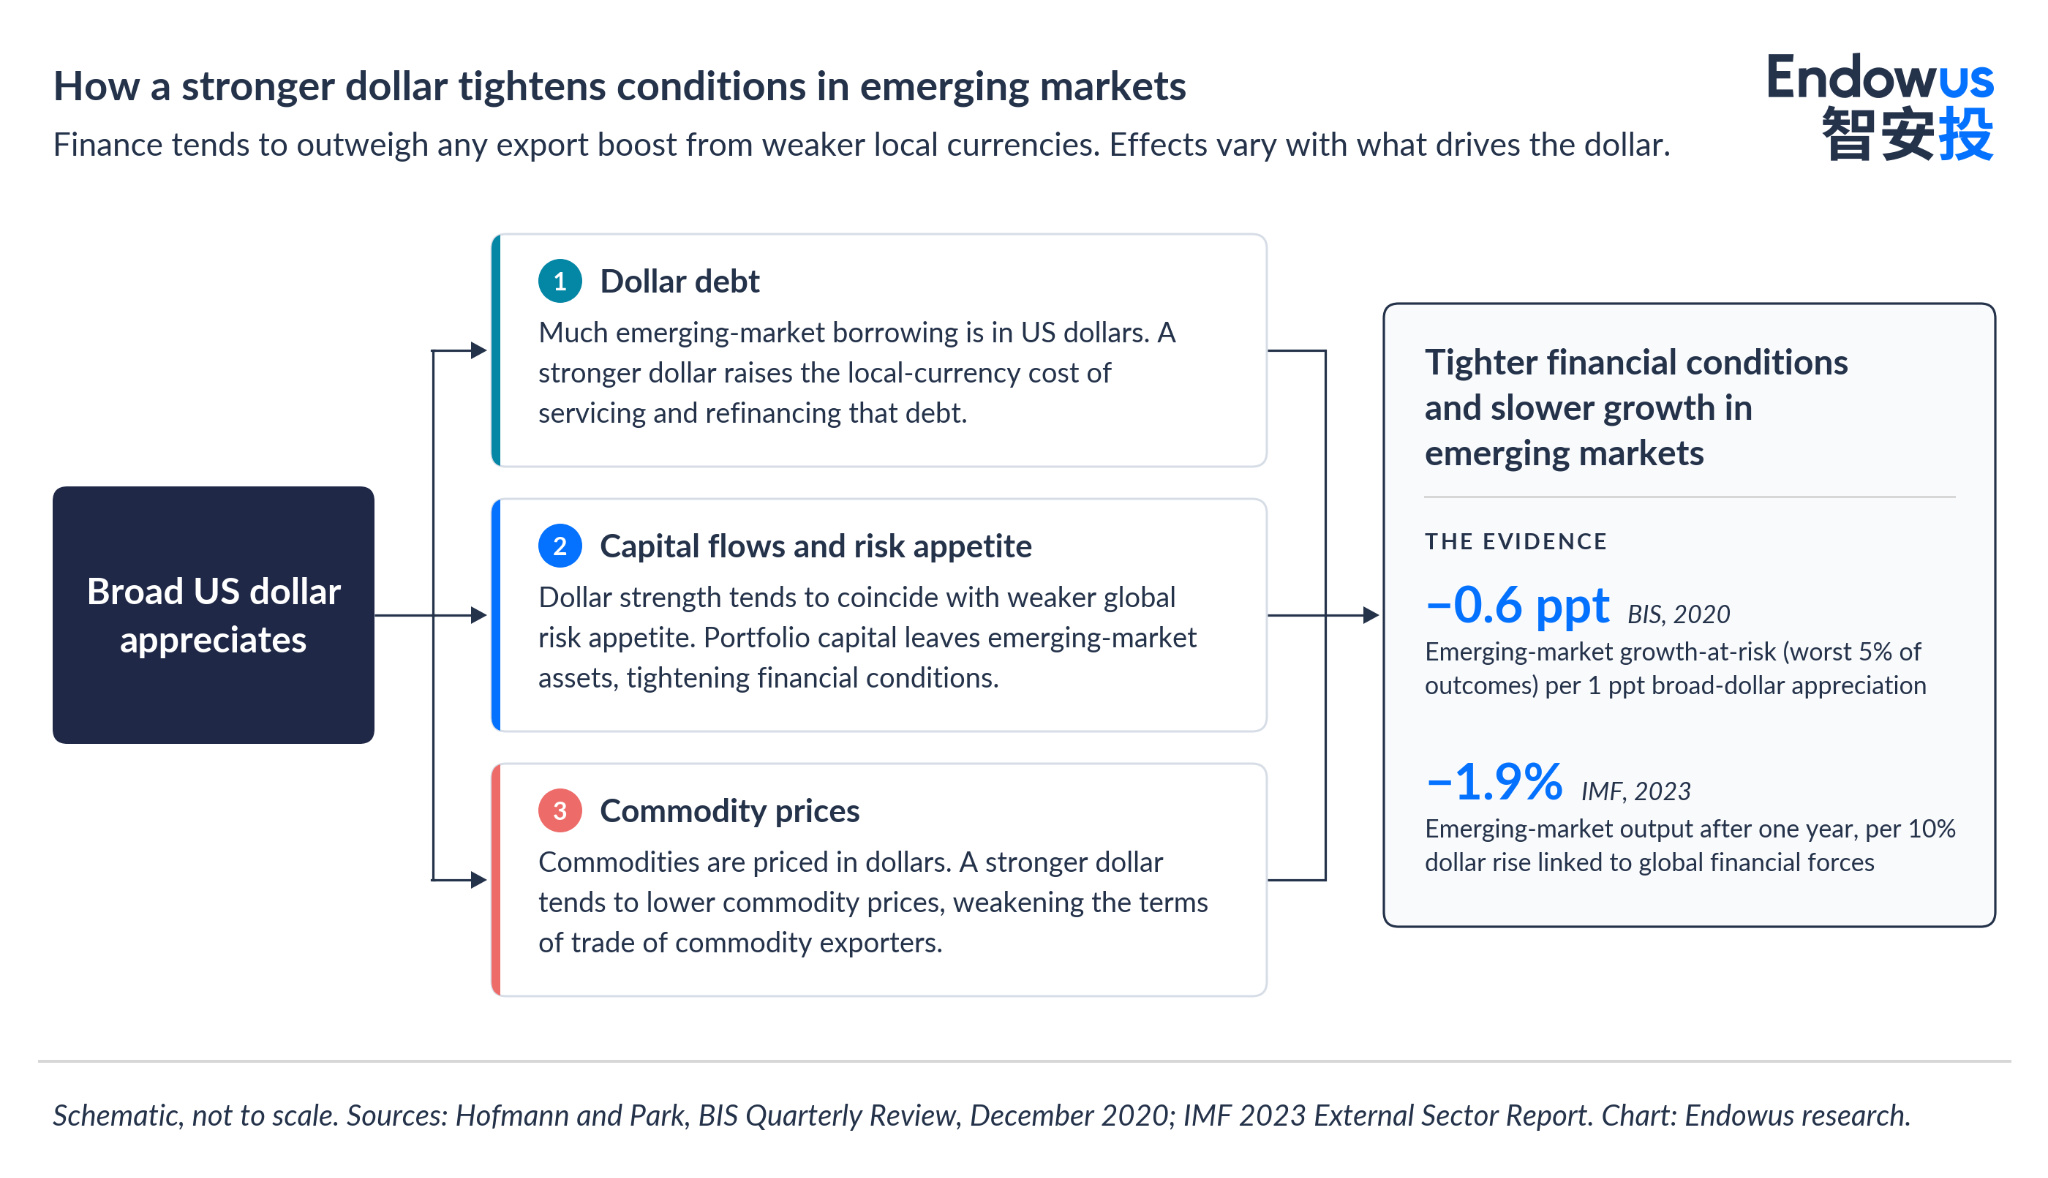
More in detail, when the dollar strengthens, three things typically happen in emerging markets that more than offset the benefits of - potentially - cheaper exports.
- First, dollar-denominated debt becomes more expensive to service: much emerging-market borrowing is denominated in dollars, so a stronger dollar raises the local-currency cost of servicing and refinancing that debt. Bruno and Shin, in BIS research, find that a stronger dollar is associated with tighter dollar credit conditions and, following appreciation, some declines in bank credit and exports for firms that rely on dollar funding.
- Second, capital flows into the United States and away from emerging markets: dollar strength tends to coincide (though this is not always the case) with weaker global risk appetite - “risk-off” market sentiment, basically - which leads portfolio capital to leave emerging-market assets and seek safe haven in developed markets, especially the US.
- Third, commodities depreciate as the dollar appreciates: priced in dollars, they tend to weaken as the dollar rises, eroding the terms of trade of commodity-exporting economies - which many emerging markets are.
Academic research has time and again supported these findings. Hofmann and Park estimate that a one percentage point appreciation shock to the broad dollar lowers emerging-market growth-at-risk — the weak tail of the growth distribution — by about 0.6 percentage points, with a larger effect where dollar debt or foreign ownership of local-currency bonds is high. Obstfeld and Zhou, in work on the "global dollar cycle," find that dollar appreciation shocks predict downturns across emerging and developing economies and correlate with measures of dollar-funding stress that reflect global investors' risk appetite. The IMF estimates that a 10% dollar appreciation driven by global financial forces reduces emerging-market output by 1.9% after one year, with the drag lingering for two and a half years.
The distinction between a broad dollar move and a pure rate shock is again instructive: in the 2013 "taper tantrum," the ten-year US Treasury yield rose about a full percentage point while the broad dollar barely moved, yet emerging-market currencies with weak external buffers fell far more than those with strong ones. Local fundamentals decide who suffers most.
Interest rates drive the dollar — until they don't
The intuition that higher US rates lift the dollar is reasonable and often correct. A wider expected return on US assets, relative to the rest of the world, attracts capital and bids up the currency. The problem is that it works only some of the time. In other circumstances, different forces prevail.
As financial professionals know, theory supports the exact opposite thesis. Uncovered interest parity (UIP) states that - in the long run - a higher-yielding currency should be expected to depreciate by the size of the interest gap, leaving expected returns equal.
UIP has been contradicted by data since Fama's foundational 1984 study. High-rate currencies have often appreciated, or at least not fallen as predicted, a result known as the forward premium puzzle. Later work by Bussière, Chinn, and co-authors shows the relationship is unstable and shifted after the global financial crisis (GFC), while Chinn and Meredith find that parity holds better over long horizons than short ones - which was the assumption of the theory in the first place.
All that aside, the key point here is not that rates are irrelevant, but that the rate-to-currency link is weak and time-varying (especially in the short-to-medium run), which is precisely the opposite of a dependable trading rule.
When rates and the dollar move together
The clearest alignments share three features:
- US tightening that is faster or more unexpected than tightening abroad, or
- a backdrop of US growth outperformance, or
- an environment of risk aversion.
The early 1980s fit the first two; the dollar rose as the Fed drove rates to record highs. In 2016 the Fed moved towards its first hike while the European Central Bank (ECB) and the Bank of Japan (BoJ) eased, and the broad dollar rose about 23%. In 2022 the Fed tightened faster than its peers, and the broad dollar rose about 10% to its October peak. In the final quarter of 2024 the dollar posted its largest quarterly gain since early 2020 on US growth outperformance and a repricing of the Fed's path.
When rates and the dollar diverge
In the final leg of the early-1980s bull run, the dollar rose about 17% between March 1984 and February 1985 even though, as Frankel documents, the US interest-rate differential had peaked in June 1984 and moved the opposite way thereafter. Between June 2004 and June 2006 the Fed raised its target 17 consecutive times, from 1% to 5.25%, yet the dollar fell and the euro rose, likely as a result of widening US fiscal deficit. In 2017 the Fed hiked three times while the broad dollar dropped nearly 9%, as growth in the euro area and elsewhere caught up and narrowed the forward-looking rate gap. And in the first half of 2025 the broad dollar fell around 6% while the Fed held rates steady — a move the New York Fed linked not only to narrowing differentials but to a weaker relative US growth outlook and heightened policy uncertainty.
Drawing some conclusions from our analysis, we can identify a loose pattern - without venturing into predictions: and that is that the rate “transmission channel” tends to dominate when a widening US rate advantage (higher rates in the US) coincides with relative US strength or with global risk aversion, especially if that rate advantage is unexpected. The same channel tends to be overwhelmed when growth abroad is catching up, when US fiscal or policy uncertainty raises the risk premium on dollar assets, when valuation is already stretched, or when the market looks past the level of rates to the end of the cycle. This is an interpretation of the historical pattern rather but importantly, not a rule.
Where the cycle stands now
The current setting illustrates the multiple channels at work - none of them being truly the sole driver of dollar strength and weakness.
After cutting rates from a peak of 5.25% to 5.50% starting in September 2024 and holding through much of 2025, the Federal Reserve resumed easing late in 2025. The dollar, meanwhile, fell about 7% over 2025 (despite no rate cuts), then firmed in early 2026 (without any rate hikes) as an energy-price shock following the US–Iran conflict favoured the United States as a net energy exporter. The Fed reversed course later in 2026: on 16 September, it raised the target range by a quarter point to 3.75% to 4.00%, its first increase since 2023.
The driver in 2025 was, presumably, political instability and some vague threats of a US debt default, which would have undermined the credibility of the dollar. Those rumors quickly faded, which stabilized the currency.
As of 18 September 2026, the broad dollar index stood about 7% below its January 2025 monthly peak — well off its 2022 and 2025 highs, but comfortably above its 2008 and 2011 lows (and unchanged since 2025).
The dollar is, in other words, mid-range rather than at an extreme. With the Fed, the ECB, and the BoJ all having moved rates over the past year, the rate-differential story is once again two-sided (thus less important) and geopolitics and energy prices have been the swing factors of 2026.
Going forward, it remains to be seen whether the dollar will appreciate following a potential rate hike cycle, or if other factors - separate from rates - dominate the narrative instead.
Investment implications for investors using non-USD-pegged currencies
Something clear emerges from this analysis of US dollar appreciation and depreciation cycles - that investors need to avoid drawing an automatic connection between rate hikes and dollar strength.
That said, for a globally diversified investor, the dollar cycle can be an additional source of volatility. Swings of 35% to 55% in the trade-weighted dollar over multi-year periods can add to, or subtract from, local-currency returns on foreign assets for years at a stretch. That makes it all the more important to gauge the amount of currency exposure in a portfolio, and to what currency(ies) the portfolio is exposed.
One caveat: currency volatility does not necessarily add to asset volatility. The two interact just as the volatility of two assets - which, in fact, they are. So it is important to measure correlation between the two to assess the volatility of an investor’s foreign currency-denominated asset exposure.
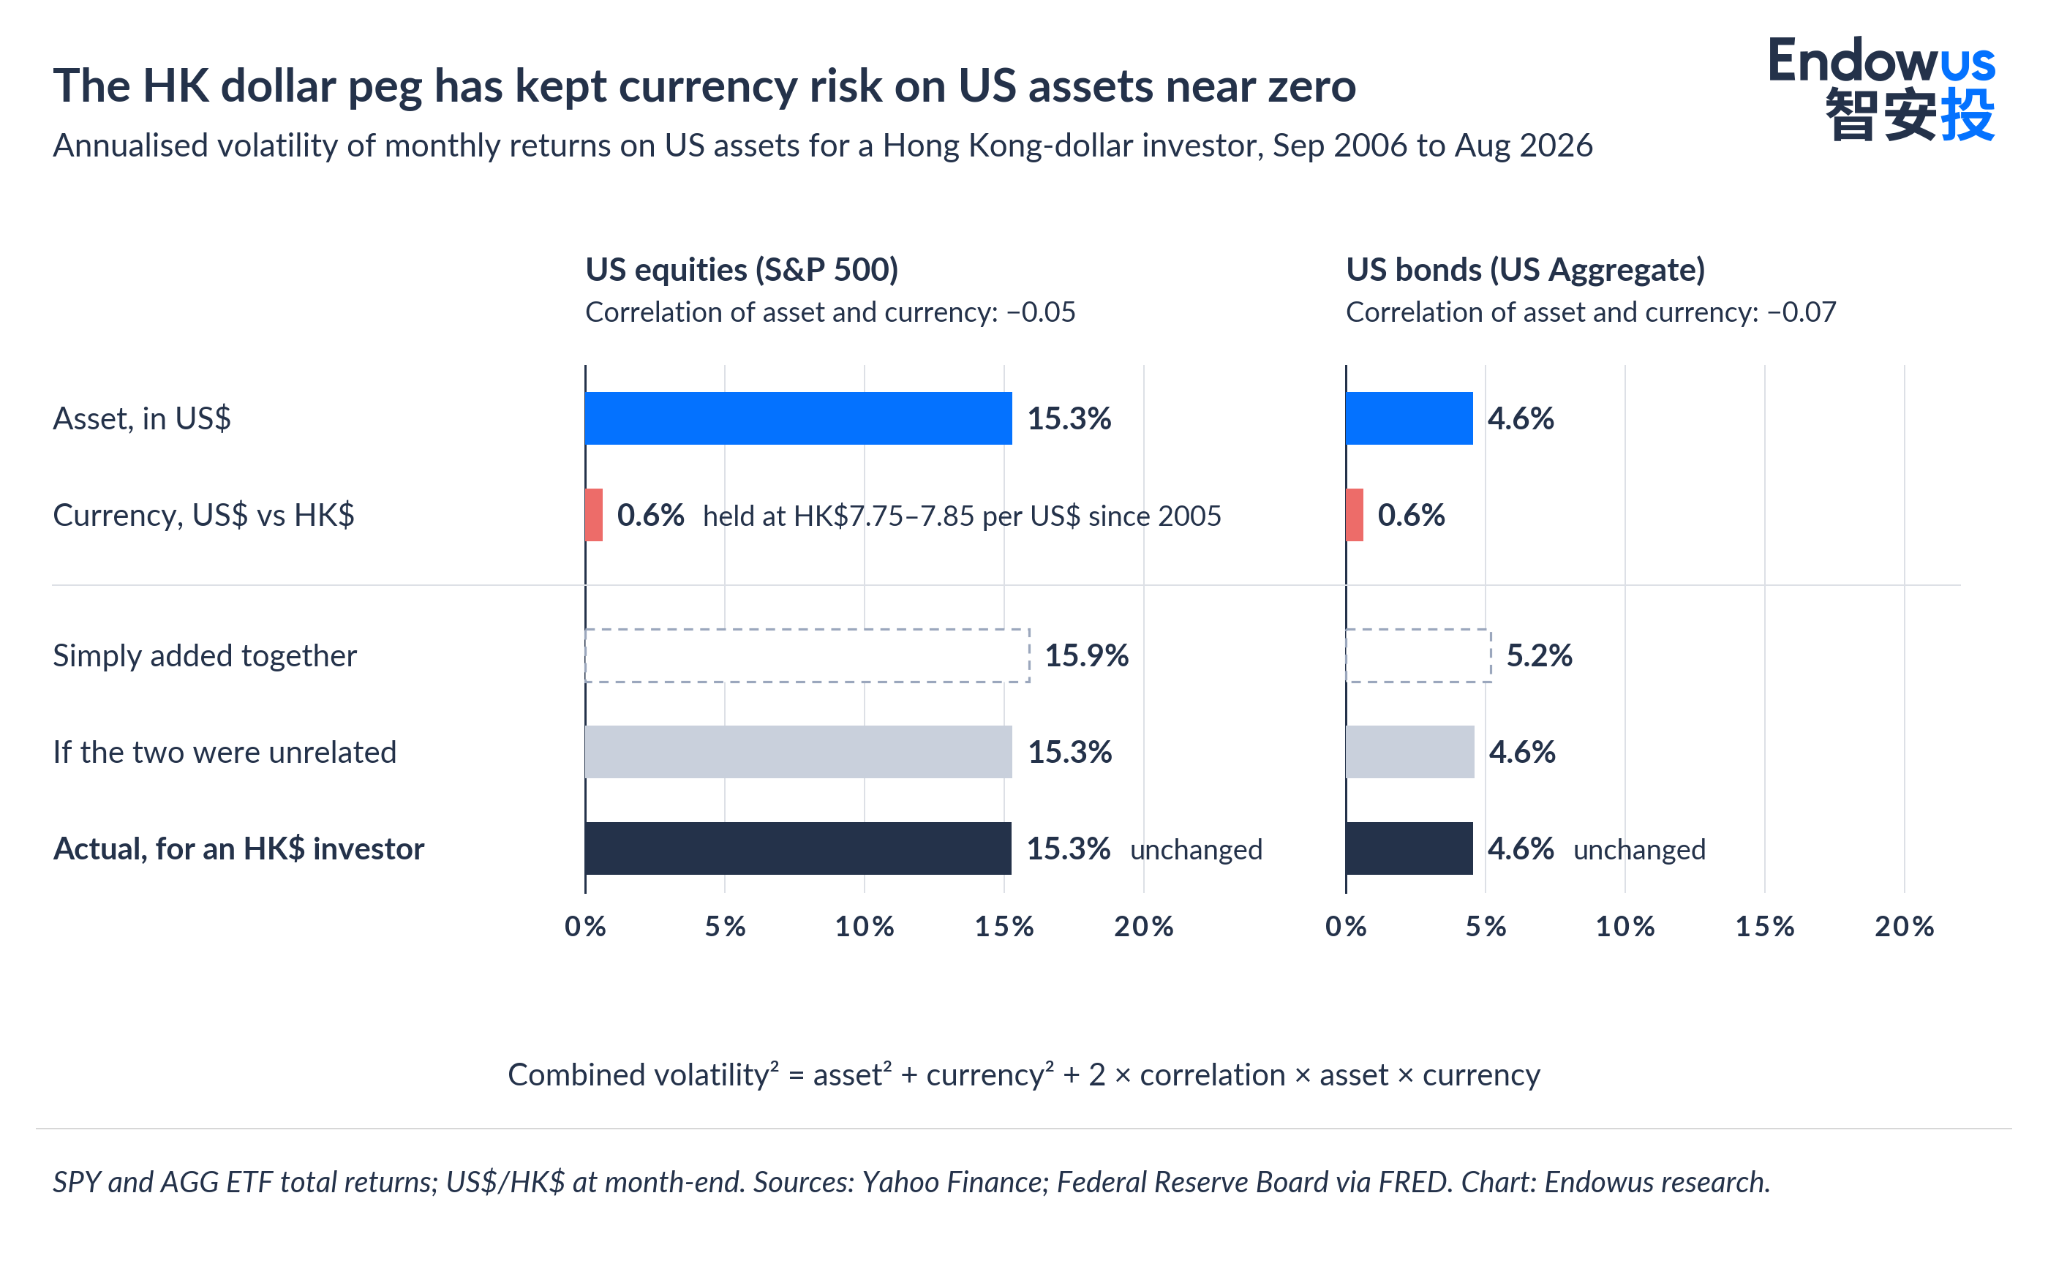
However, if the exchange rate - such as in the case of the HK dollar with the US dollar - is managed through a peg, the need for a hedge is limited. Factually, a HK dollar and a US dollar exposure will look the same - except for a different yield curve.
Investment implications for investors using HK dollar
For a HK dollar investor, the currency component that adds 5.6% of volatility for a Singapore-dollar investor shrinks to almost nothing: the Hong Kong dollar's annualised volatility against the US dollar barely existed over the same period. This is because of Hong Kong's Linked Exchange Rate System: the Hong Kong Monetary Authority (HKMA) keeps the Hong Kong dollar within a band of HK$7.75 to HK$7.85 per US dollar, so a Hong Kong-dollar investor's US dollar exposure is, in effect, close to fixed.
Because both the currency term and the correlation term in the formula scale with currency volatility, they all but disappear regardless of how the two are correlated, and a correlation measured on such small moves within a narrow band carries little meaning in any case. The result is that, for as long as the peg holds, a Hong Kong-dollar investor's volatility on US assets is in practice about the same as a US-dollar investor's.
Emerging-market allocations deserve particular scrutiny in this light. Because the broad dollar behaves as a risk factor for emerging economies, emerging-market equity and local-currency bond returns have historically been, in part, an investor’s position on the dollar cycle.
A useful implication would be to hold currency exposure across several currencies, or under a consistent hedging policy, so that no part of the portfolio depends on a single call about the dollar's direction.
Key takeaways
- The dollar moves in long cycles of large amplitude. Recognising the cycle matters more for portfolio construction than predicting its next turn.
- The euro is the mirror image of the dollar by construction, while a stronger dollar tightens emerging-market conditions mainly through dollar debt, capital flows, and commodity prices.
- Interest rates are an important but unreliable driver; growth, risk appetite, valuation, and policy credibility can and do override the rate gap.
- Currency exposure is a deliberate portfolio decision. Diversifying across currencies, or applying a consistent hedging policy, avoids depending on a single view of the dollar.
Disclaimer
Risk Warnings
Investment involves risk. Past performance is not an indicator nor a guarantee of future performance. The value of investments and the income from them can go down as well as up, and you may not get the full amount you invested. Rates of exchange may cause the value of investments to go up or down.
This article is not intended to be relied upon as a forecast or research or investment advice, and should not form the basis of any investment or other decisions. The information contained herein is not intended, and should not be construed, as any legal, tax, regulatory, accounting or financial advice. If you would like investment, accounting, tax or legal advice, you should consult with your own professional advisors regarding your individual circumstances and needs.
The information in this article may not be suitable for all investors. You are responsible for any action that you take or decision that you make in reliance on any content in this article, and you agree that Endowus HK Limited ("Endowus") is not liable under any circumstances.
No invitation or solicitation
Neither the information, nor any opinion, contained in this article constitutes a recommendation, offer or solicitation by Endowus or its affiliates to you to buy or sell any securities, collective investment schemes or other financial instruments or services, nor shall any such security, collective investment scheme, or other financial instruments or services be offered or sold to any person in any jurisdiction in which such offer, solicitation, purchase, or sale would be unlawful under the securities laws of such jurisdiction.
This is not intended to be an invitation or offer made to the public to subscribe for any financial product or to enter into any transaction.
Accuracy of Information
Whilst Endowus has made reasonable efforts to provide accurate and timely information, there may be inadvertent delays, omissions, technical or factual inaccuracies or errors in any such information. Endowus does not warrant or represent that the information in this article is correct, accurate or reliable.
Opinions
Any opinion or estimate above is made on a general basis and none of Endowus, nor any of its affiliates, representatives or agents have given any consideration to nor have made any investigation of the objective, financial situation or particular need of any user, reader, any specific person or group of persons. Opinions expressed herein are subject to change without notice.
Any forward-looking statements, prediction, projection or forecast on the economy, stock market, bond market or economic trends of the markets contained in this article are subject to market influences and contingent upon matters outside the control of Endowus and therefore may not be realised in the future.
In presenting the information above, none of Endowus, its affiliates, directors, employees, representatives or agents have given any consideration to, nor have made any investigation of the objective, financial situation or particular need of any user, reader, any specific person or group of persons. Therefore, no representation is made as to the completeness and adequacy of the information to make an informed decision. You should carefully consider whether any investment views and products/services are appropriate in view of your investment experience, objectives, financial resources and relevant circumstances.
This article has not been reviewed by the Securities and Futures Commission of Hong Kong.