

- Chief Executive John Lee delivered the 2026 Policy Address on 16 September 2026, the first presented alongside a five-year development plan, against a firmer economy that grew 5.1% in the first half of 2026.
- For investors, the relevant information is the pledge to keep Hong Kong’s position as the world’s largest cross-boundary wealth management centre, a broader tax regime for funds and family offices, and further steps to deepen the offshore renminbi, fixed income, gold, and digital-asset markets.
- For households, what matters are the Address widens Mandatory Provident Fund (MPF) investment options, raises public housing supply, and adds targeted property and tax support for families with newborns — though several measures still require legislation.
Chief Executive John Lee delivered his 2026 Policy Address to the Legislative Council on 16 September 2026, the first to be presented alongside a five-year development plan for the city. The backdrop was firmer than in recent years: the economy grew 5.1% year on year in the first half of 2026, and the government raised its full-year growth forecast to a range of 3.5% to 4.5% in August.
The Address ran across housing, the economy, talent, and Hong Kong’s standing as an international financial centre. Below, we set out the five measures most relevant to investors and to anyone planning their finances in Hong Kong.
Housing supply rises, with targeted help for young families
Public housing production over the next five years is set to reach about 196,000 units, including 30,000 Light Public Housing units. That is an increase of more than 80% on the current administration’s first five-year period, according to the Housing Authority. The Composite Waiting Time for subsidised rental housing is targeted to fall to 4.5 years in 2026-27, and below four years by 2030-31.
The demand-side measures are narrow and aimed at families with newborns. From the next Home Ownership Scheme (HOS) sale, White Form family applicants with a newborn may borrow up to 95% of a flat’s price, above the usual 90% White Form ceiling. Families with a child born in Hong Kong on or after 16 September 2026 may also claim a stamp duty concession of up to HK$20,000 when buying a residential property, provided the purchase falls within one year before to two years after the birth and at least one parent is a Hong Kong permanent resident. The Inland Revenue Department has confirmed that this concession requires a stamp duty amendment bill before it takes effect.
Broader stamp duty settings were fixed at the February 2026 Budget rather than in this Address. For investors, the housing package is supply-led; the new demand measures are targeted rather than a broad stimulus, and the two newborn measures are not yet law.
MPF reform widens retirement investment options
The Address confirmed that the government aims to lift the total investment limit on eligible index-tracking exchange-traded funds (ETFs) held by MPF funds, giving schemes more room to use low-cost local ETFs. This follows the Mandatory Provident Fund Schemes Authority (MPFA) streamlining approval for gold ETFs within MPF portfolios in July 2026.
These changes build on structural reforms already under way. Phase One of MPF “Full Portability,” which lets members transfer a larger share of their benefits to a scheme of their choice, was approved by the Legislative Council in September 2025 and is expected to take effect in 2026. The eMPF Platform has now onboarded all schemes, and the government expects more than 10 million member accounts to benefit from lower fees. You can read more on how to consolidate and manage your MPF.
Costs compound over a working life, so a wider and potentially cheaper menu of MPF options matters for long-term retirement outcomes. The salaries-tax deduction for Tax-Deductible Voluntary Contributions and qualifying deferred annuity premiums remains capped at HK$60,000 a year in aggregate.
Hong Kong cements its lead in wealth and asset management
The Address states that Hong Kong has become the world’s largest cross-boundary wealth management centre. It follows the passage of a bill enhancing preferential tax treatment for funds, single-family offices, and carried interest, and the government plans to step up efforts to attract more global capital to be managed in the city.
The base is already sizeable. A study commissioned by Invest Hong Kong counted more than 3,380 single-family offices operating in the city at the end of 2025. On the investor-migration side, the New Capital Investment Entrant Scheme (New CIES) had drawn nearly 3,200 applications, representing about HK$95 billion of anticipated investment, as of March 2026.
The Address also set out reforms to the real estate investment trust (REIT) market, including a bill to allow REIT restructuring and a later proposal to waive stamp duty on non-residential property transferred into a REIT seeking to list. For high-net-worth and family-office investors, the direction is a deeper product ecosystem and more routes to access it.
The offshore renminbi and fixed income market deepens
Hong Kong remains the main offshore hub for the renminbi (RMB), and the Address set out several steps to broaden the market. Offshore RMB lending reached a record RMB 935 billion in 2025, and dim sum bond issuance has held at around RMB 1 trillion for two consecutive years. The RMB Business Facility in Hong Kong has been expanded to RMB 500 billion, with the lending tenor extended to three years.
The cross-boundary connect schemes are being extended in turn. The authorities plan to broaden the range of products under Bond Connect (Southbound Trading), develop a repurchase business using Southbound bonds as collateral, and prepare to include RMB counters under Stock Connect (Southbound Trading). Swap Connect is expected to add a new reference rate in the fourth quarter of 2026.
Hong Kong also captured close to half of global digital bond issuance between 2025 and the first half of 2026, and the government intends to make such issuance a regular feature. For income-oriented and diversified portfolios, these steps may widen the set of RMB and fixed income instruments available over time.
Capital markets, gold, and digital assets modernise
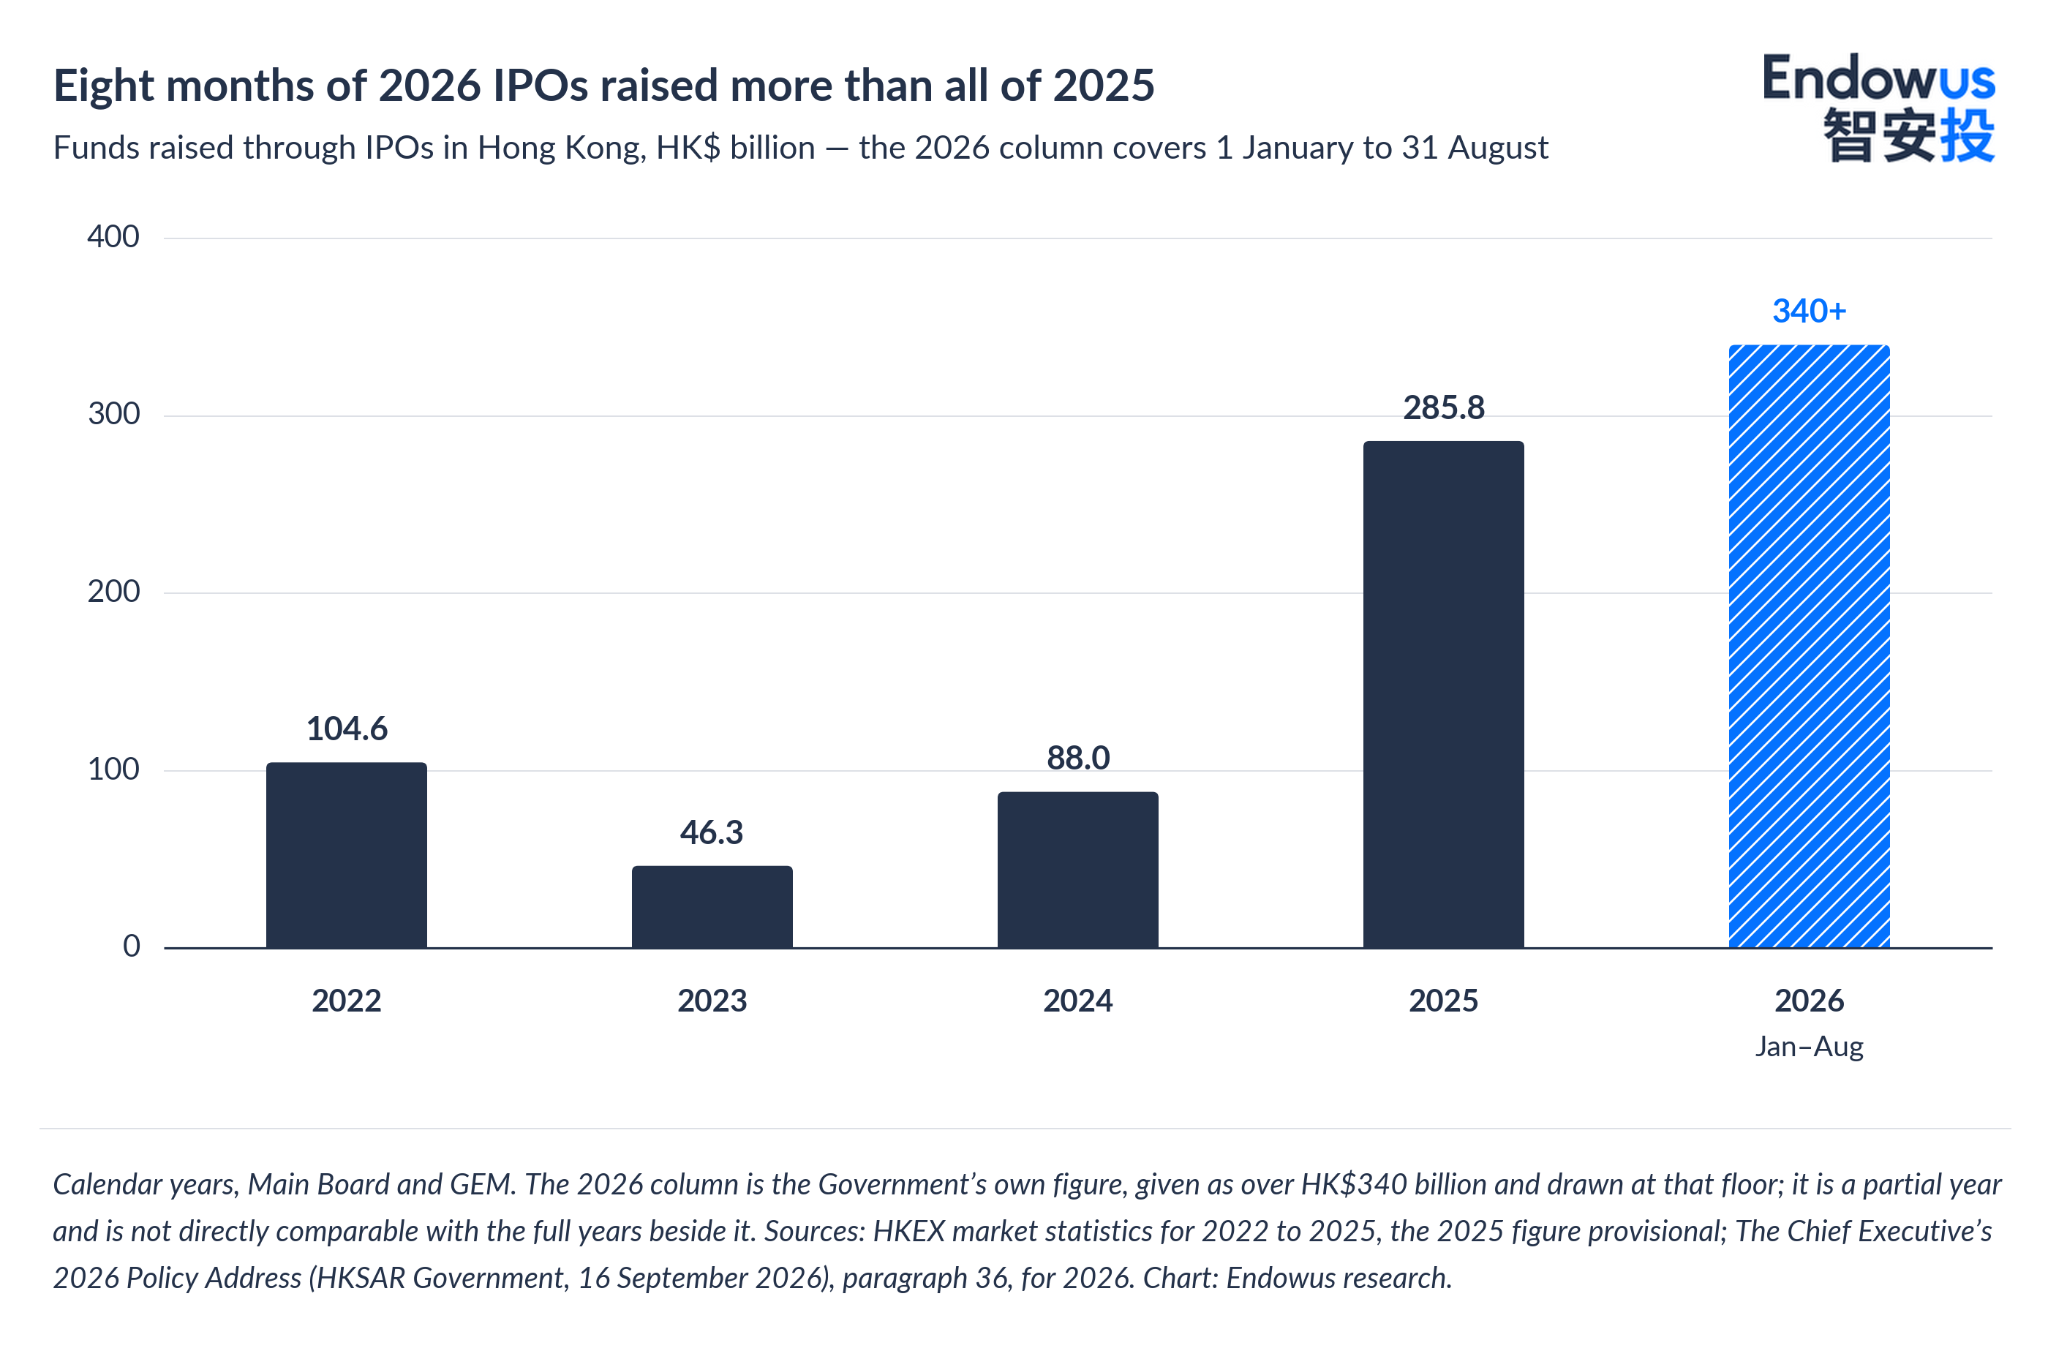
The listing pipeline has been strong: funds raised through initial public offerings (IPOs) passed HK$340 billion by the end of August 2026, already above the full-year 2025 total. The Securities and Futures Commission (SFC) and Hong Kong Exchanges and Clearing plan further listing reforms, and the exchange is preparing a “T+1” settlement cycle for the cash market.
Gold and commodities feature more prominently than in past addresses. A central clearing and settlement system for gold is due to launch in the first quarter of 2027, the exchange plans to introduce RMB-denominated, physically settled gold futures, and the Hong Kong Monetary Authority (HKMA) is exploring an increase in the Exchange Fund’s gold holdings.
On digital assets, the SFC plans to enhance the virtual-asset licensing regime, refine the framework for tokenised investment products, and support trading of regulated stablecoins, including their use in settling tokenised money market funds. Newer and more complex instruments carry their own risks, and warrant the same diligence as any other holding.
Planning your financial future
The 2026 Policy Address is, on balance, a continuity document. It builds on existing reforms in wealth management, retirement, and the fixed income market rather than changing course, and set against a five-year plan and a firmer economy, its investor-relevant measures are mostly structural and medium-term.
The practical point is that many of the headline items are proposals or bills that have yet to become law, so their timing may shift. On one hand, a broader MPF menu, deeper capital markets, and targeted household support may all widen the options available to investors over time. On the other hand, the near-term effect on any individual portfolio is likely to be modest, and the sensible response is to keep decisions anchored to your own goals, time horizon, and risk tolerance rather than to any single announcement.
At Endowus, our licensed advisers can help you consider how these developments fit your circumstances — from building a globally diversified core portfolio to reviewing your MPF, exploring private market funds, or checking which CIES-eligible funds are available on the platform.
Disclaimer
Risk Warnings
Investment involves risk. Past performance is not an indicator nor a guarantee of future performance. The value of investments and the income from them can go down as well as up, and you may not get the full amount you invested. Rates of exchange may cause the value of investments to go up or down.
This article is not intended to be relied upon as a forecast or research or investment advice, and should not form the basis of any investment or other decisions. The information contained herein is not intended, and should not be construed, as any legal, tax, regulatory, accounting or financial advice. If you would like investment, accounting, tax or legal advice, you should consult with your own professional advisors regarding your individual circumstances and needs.
The information in this article may not be suitable for all investors. You are responsible for any action that you take or decision that you make in reliance on any content in this article, and you agree that Endowus HK Limited (“Endowus”) is not liable under any circumstances.
No invitation or solicitation
Neither the information, nor any opinion, contained in this article constitutes a recommendation, offer or solicitation by Endowus or its affiliates to you to buy or sell any securities, collective investment schemes or other financial instruments or services, nor shall any such security, collective investment scheme, or other financial instruments or services be offered or sold to any person in any jurisdiction in which such offer, solicitation, purchase, or sale would be unlawful under the securities laws of such jurisdiction.
This is not intended to be an invitation or offer made to the public to subscribe for any financial product or to enter into any transaction.
Accuracy of Information
Whilst Endowus has made reasonable efforts to provide accurate and timely information, there may be inadvertent delays, omissions, technical or factual inaccuracies or errors in any such information. Endowus does not warrant or represent that the information in this article is correct, accurate or reliable.
Opinions
Any opinion or estimate above is made on a general basis and none of Endowus, nor any of its affiliates, representatives or agents have given any consideration to nor have made any investigation of the objective, financial situation or particular need of any user, reader, any specific person or group of persons. Opinions expressed herein are subject to change without notice.
Any forward-looking statements, prediction, projection or forecast on the economy, stock market, bond market or economic trends of the markets contained in this article are subject to market influences and contingent upon matters outside the control of Endowus and therefore may not be realised in the future.
In presenting the information above, none of Endowus, its affiliates, directors, employees, representatives or agents have given any consideration to, nor have made any investigation of the objective, financial situation or particular need of any user, reader, any specific person or group of persons. Therefore, no representation is made as to the completeness and adequacy of the information to make an informed decision. You should carefully consider whether any investment views and products/services are appropriate in view of your investment experience, objectives, financial resources and relevant circumstances.
This article has not been reviewed by the Securities and Futures Commission of Hong Kong.