








Register for the event
Endowus invites you to our exclusive event with Macquarie Asset Management, as we discuss unlocking opportunities in Infrastructure- a $1.3tn asset class.
This event is reserved for Accredited Investors (AIs) only. To register for the event, please indicate one of the following:
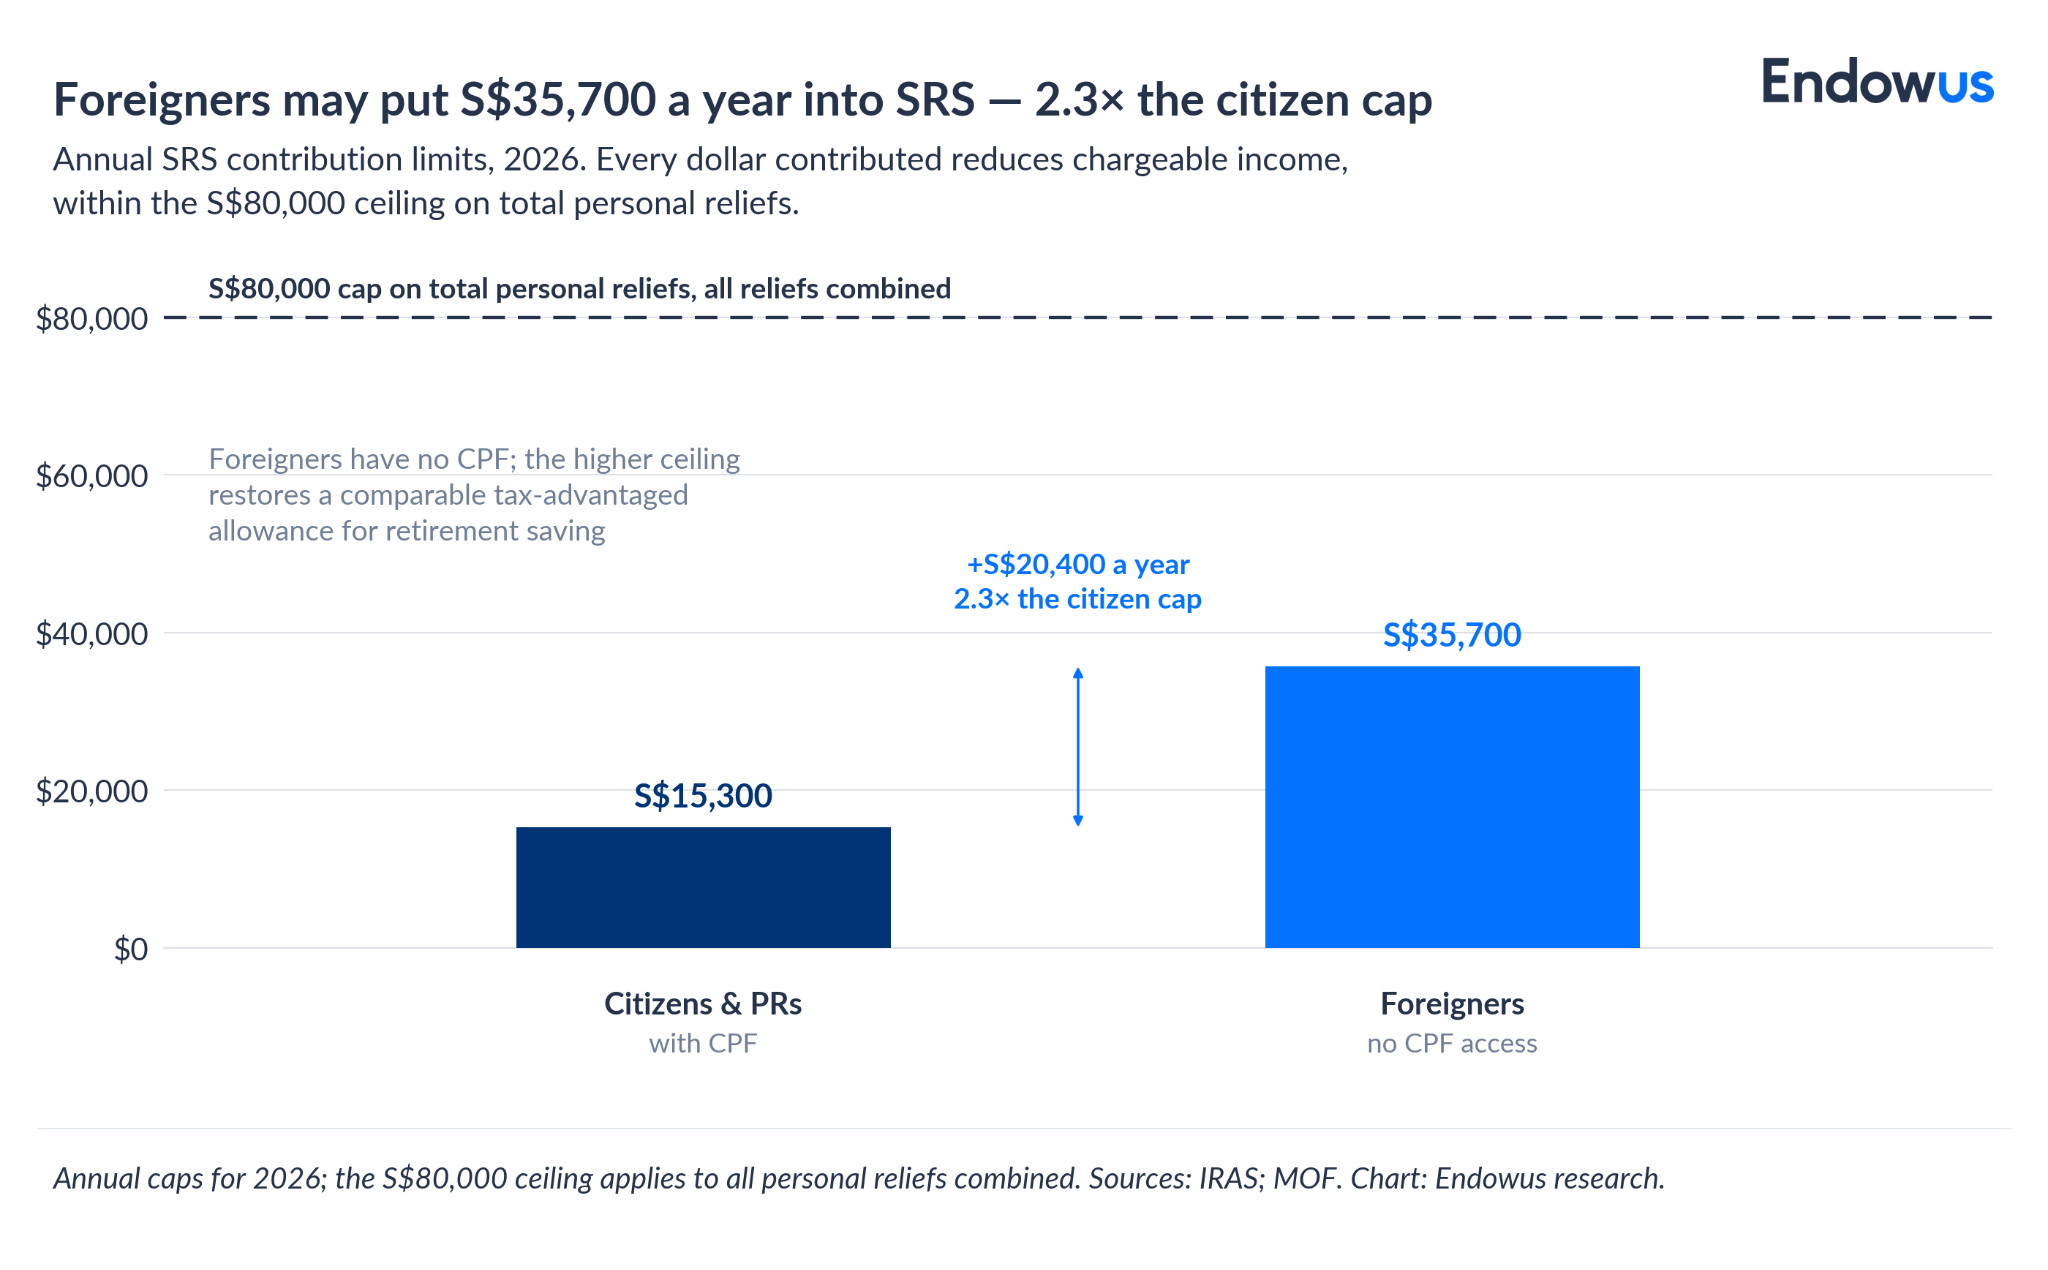
- Foreigners may contribute up to S$35,700 to the Supplementary Retirement Scheme (SRS) each year (more than double the S$15,300 cap for citizens and permanent residents) and each dollar contributed reduces chargeable income, up to the S$80,000 personal income tax relief cap.
- SRS is a tax deferral rather than a rebate, and its value turns on the exit: withdrawals taken on or after the statutory retirement age are only 50% taxable, whereas a premature withdrawal is fully taxable and carries a 5% penalty.
- A foreigner who has held an SRS account for at least 10 years from the first contribution may withdraw the full balance without penalty after leaving Singapore, but the operator withholds tax at the 24% non-resident rate at the point of withdrawal, recoverable only after filing a return.
For a foreign professional with no access to the Central Provident Fund (CPF), the Supplementary Retirement Scheme (SRS) can offer tax savings and the basis to build up a retirement income.
The scheme is often presented to foreigners as a simple deduction. That framing is incomplete. SRS is a deferral, not a rebate. The variable is how and when money leaves the account, a distinction that weighs more heavily on foreigners who face a higher contribution cap, a specific withholding regime, and the likelihood of eventually leaving Singapore.
This article sets out how much a foreigner may contribute in 2026, how the relief works and for whom it is worth claiming, what happens to the account on withdrawal, and how the rules treat those who leave—including the withholding tax that applies at the point of exit.
What is the SRS contribution limit for foreigners?
The annual SRS contribution limit is S$35,700 for foreigners, against S$15,300 for Singapore citizens and permanent residents. The gap is deliberate. Foreigners do not contribute to the Central Provident Fund (CPF), Singapore’s mandatory retirement savings system, so the higher SRS ceiling restores a comparable allowance for tax-advantaged retirement savings.
SRS contributions must reach the account by 31 December to count towards that year’s relief, and a foreigner must file the annual Declaration Form for SRS so the operator applies the higher SRS contribution limit rather than defaulting to the citizen limit.
An SRS account is opened with one of the three operator banks (DBS, OCBC, or UOB) and an individual may hold only one account at a time.
How much SRS tax savings can you get as a foreigner?
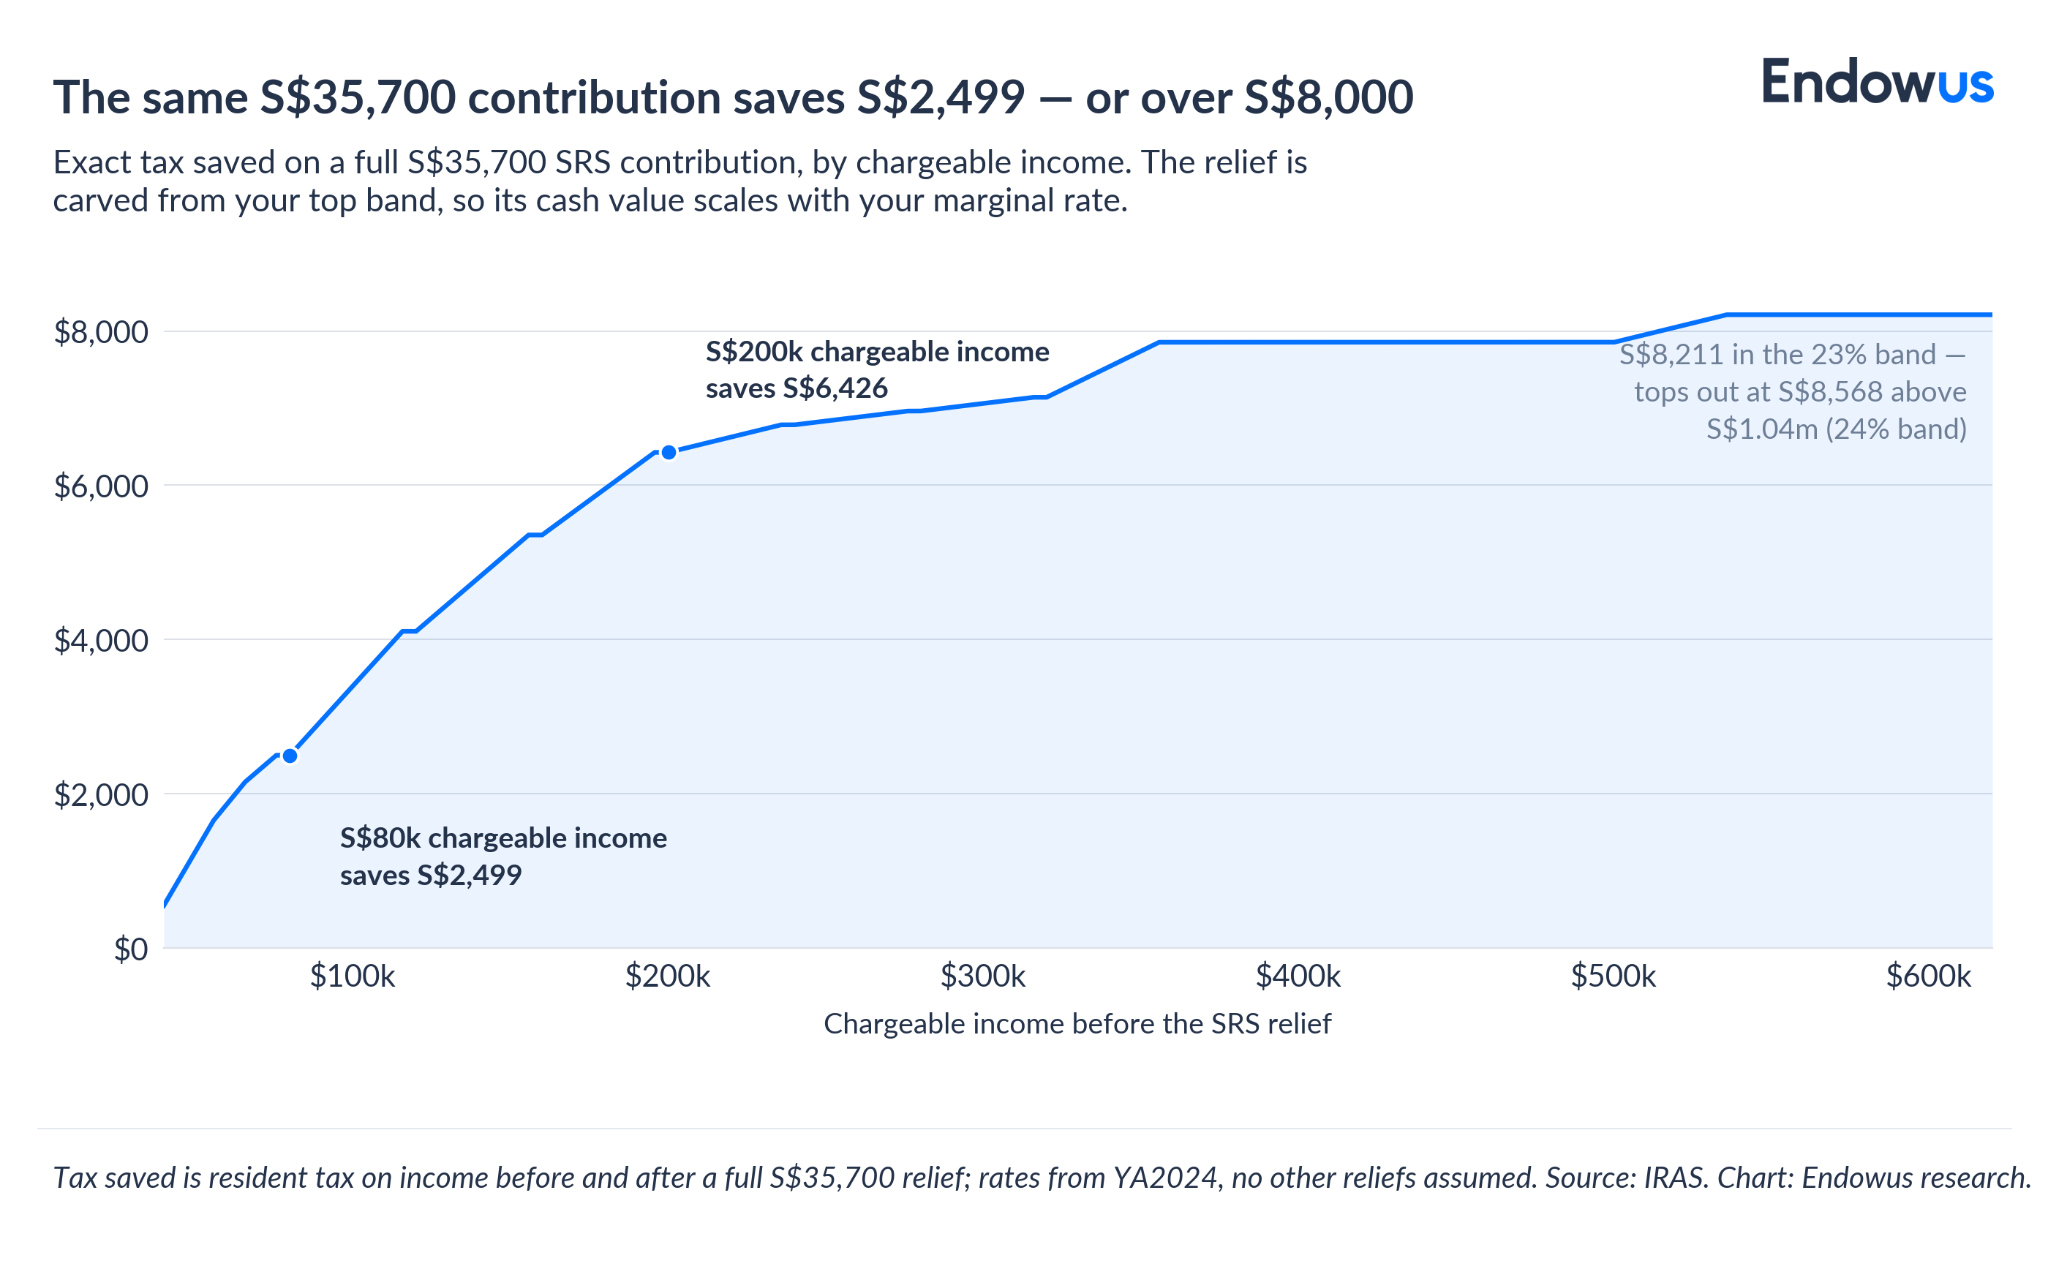
SRS relief reduces chargeable income, which means its cash value equals the amount contributed multiplied by the contributor’s marginal tax rate. For a Singapore tax resident taxed on the progressive resident scale, that can be substantial; for income taxed at a flat non-resident rate, the mechanics differ and the benefit may be different.
Consider a tax-resident foreigner with S$200,000 in chargeable income who contributes the full S$35,700. The contribution is carved from the top of their income, which sits in the 18% band, so the tax relief is worth roughly S$6,426. The same contribution made by someone in the 7% band saves closer to S$2,499. These are just illustrative examples. Please check your individual situation with a licensed tax advisor.
There are two constraints.
- The S$80,000 personal income tax relief cap applies to the sum of all reliefs claimed in a Year of Assessment, so a full SRS contribution stacked on other reliefs may exceed it and deliver no further benefit.
- Unlike a rebate, an SRS contribution that produces no usable relief is not refunded—the money is simply locked in the scheme.
In other words, SRS tax relief is only as valuable as your marginal tax rate.
Tax on SRS withdrawal for foreigners: how much do you have to pay?
The exit rules are quite important. The pivot is the statutory retirement age (64 from 1 July 2026). As a reminder, the age that applies to you as an individual is the one prevailing when you make (or have made) your first contribution, unaffected by later increases.
Each withdrawal made on or after that age is 50% taxable (half of it will be taxed at the prevailing rate at the time of withdrawal). However, withdrawals can also be spread over up to 10 years, with the account deemed closed in the tenth year. This allows the taxable half to be drawn down across low or zero-rate bands, especially if the individual has no other income.
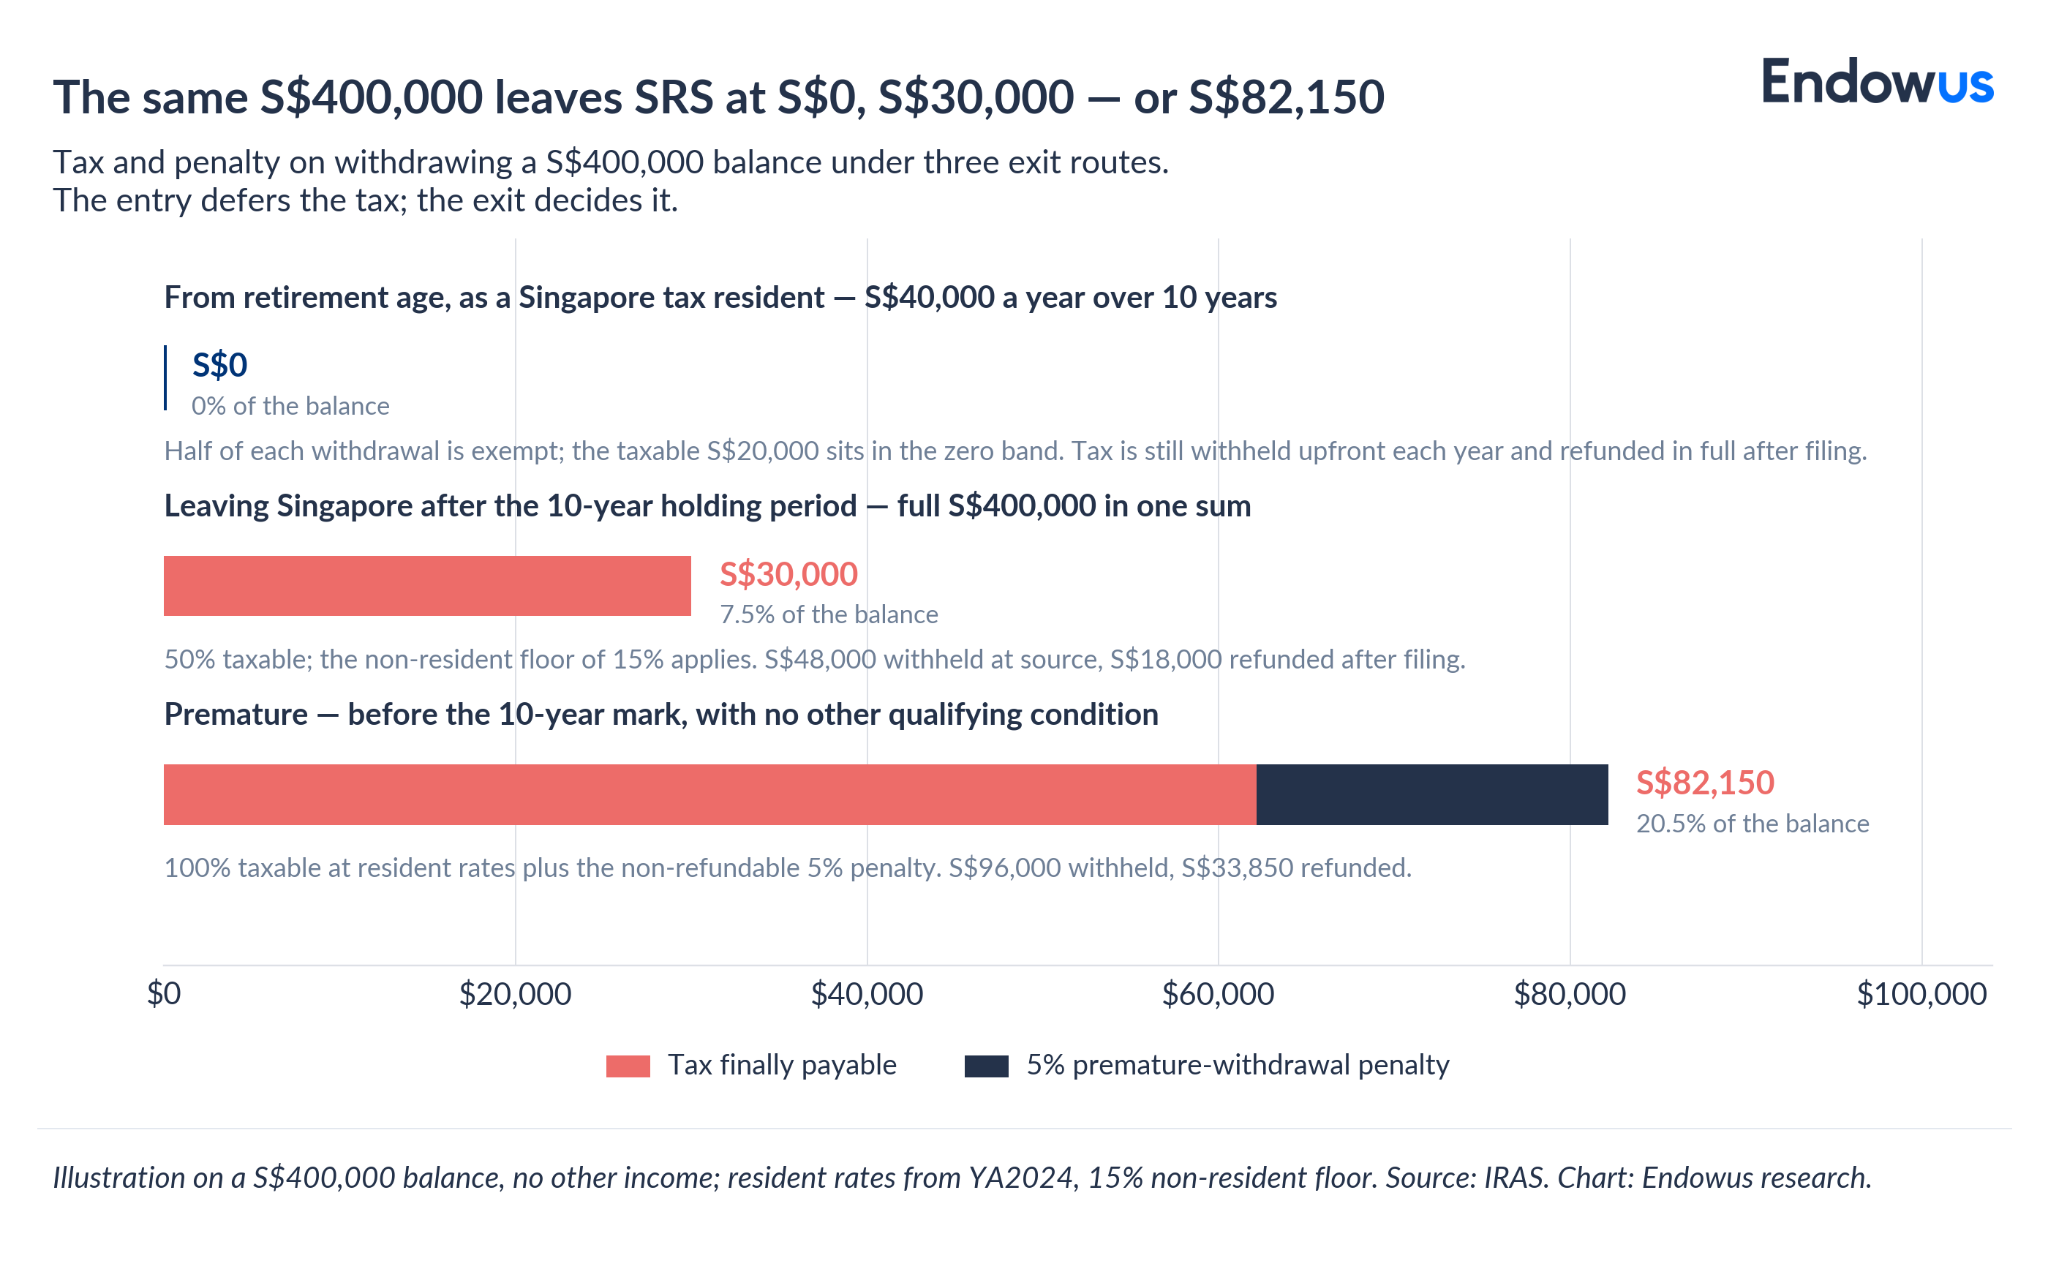
A retiree with no other taxable income may withdraw up to S$40,000 a year without tax (because half is exempt and the taxable S$20,000 falls within the zero-rate band) or up to S$400,000 across the 10-year window.
Withdraw before retirement age and the treatment inverts: the full amount is taxable, and a 5% penalty applies on top. Investments need not be sold to withdraw—the scheme permits withdrawals in kind, transferring holdings out without forcing a disposal at an inopportune time.
All the abovementioned information, as well as the chart, are illustrative and not exhaustive. You should consult a tax advisor to take into consideration your specific situation.
Foreigners leaving Singapore: what to know about SRS withdrawal rules and withholding tax
A foreigner who is neither a citizen nor a permanent resident, has left Singapore, and has held the SRS account for at least 10 years from the date of the first contribution may withdraw the entire balance in a single sum, with the 50% concession applicable (so only half of the withdrawal is taxable) and without penalty.
The 10-year clock is the binding constraint. It starts at the first contribution, not at account opening, so the timing of that first dollar sets the earliest date for a penalty-free full withdrawal (assuming the individual is leaving the country). If the departure is prior to the 10 year freeze, and does not meet any other qualifying condition, the withdrawal is fully taxable, with an added 5% penalty.
At the point of withdrawal, the operator withholds tax at the prevailing non-resident rate of 24% on the taxable portion. A concessionary 15% rate may apply where cumulative withdrawals in a calendar year do not exceed S$200,000 and the holder has no other Singapore income that year.
Either way, the amount withheld is a credit against final tax, not the final tax itself. For tax residents, the tax payable is based on the progressive resident rates. For a non-resident, it is assessed at the higher of 15% or the resident progressive rates. Any over-withholding is refunded once a return is filed.
The practical implication is that a clean exit rewards planning. The 10-year threshold, the S$200,000 annual ceiling, and the no-other-income condition are variables a departing contributor can sequence deliberately, if they plan ahead.
All the abovementioned information is illustrative and not exhaustive. You should consult a tax advisor to take into consideration your specific situation.
Why you should consider SRS investing as a foreigner
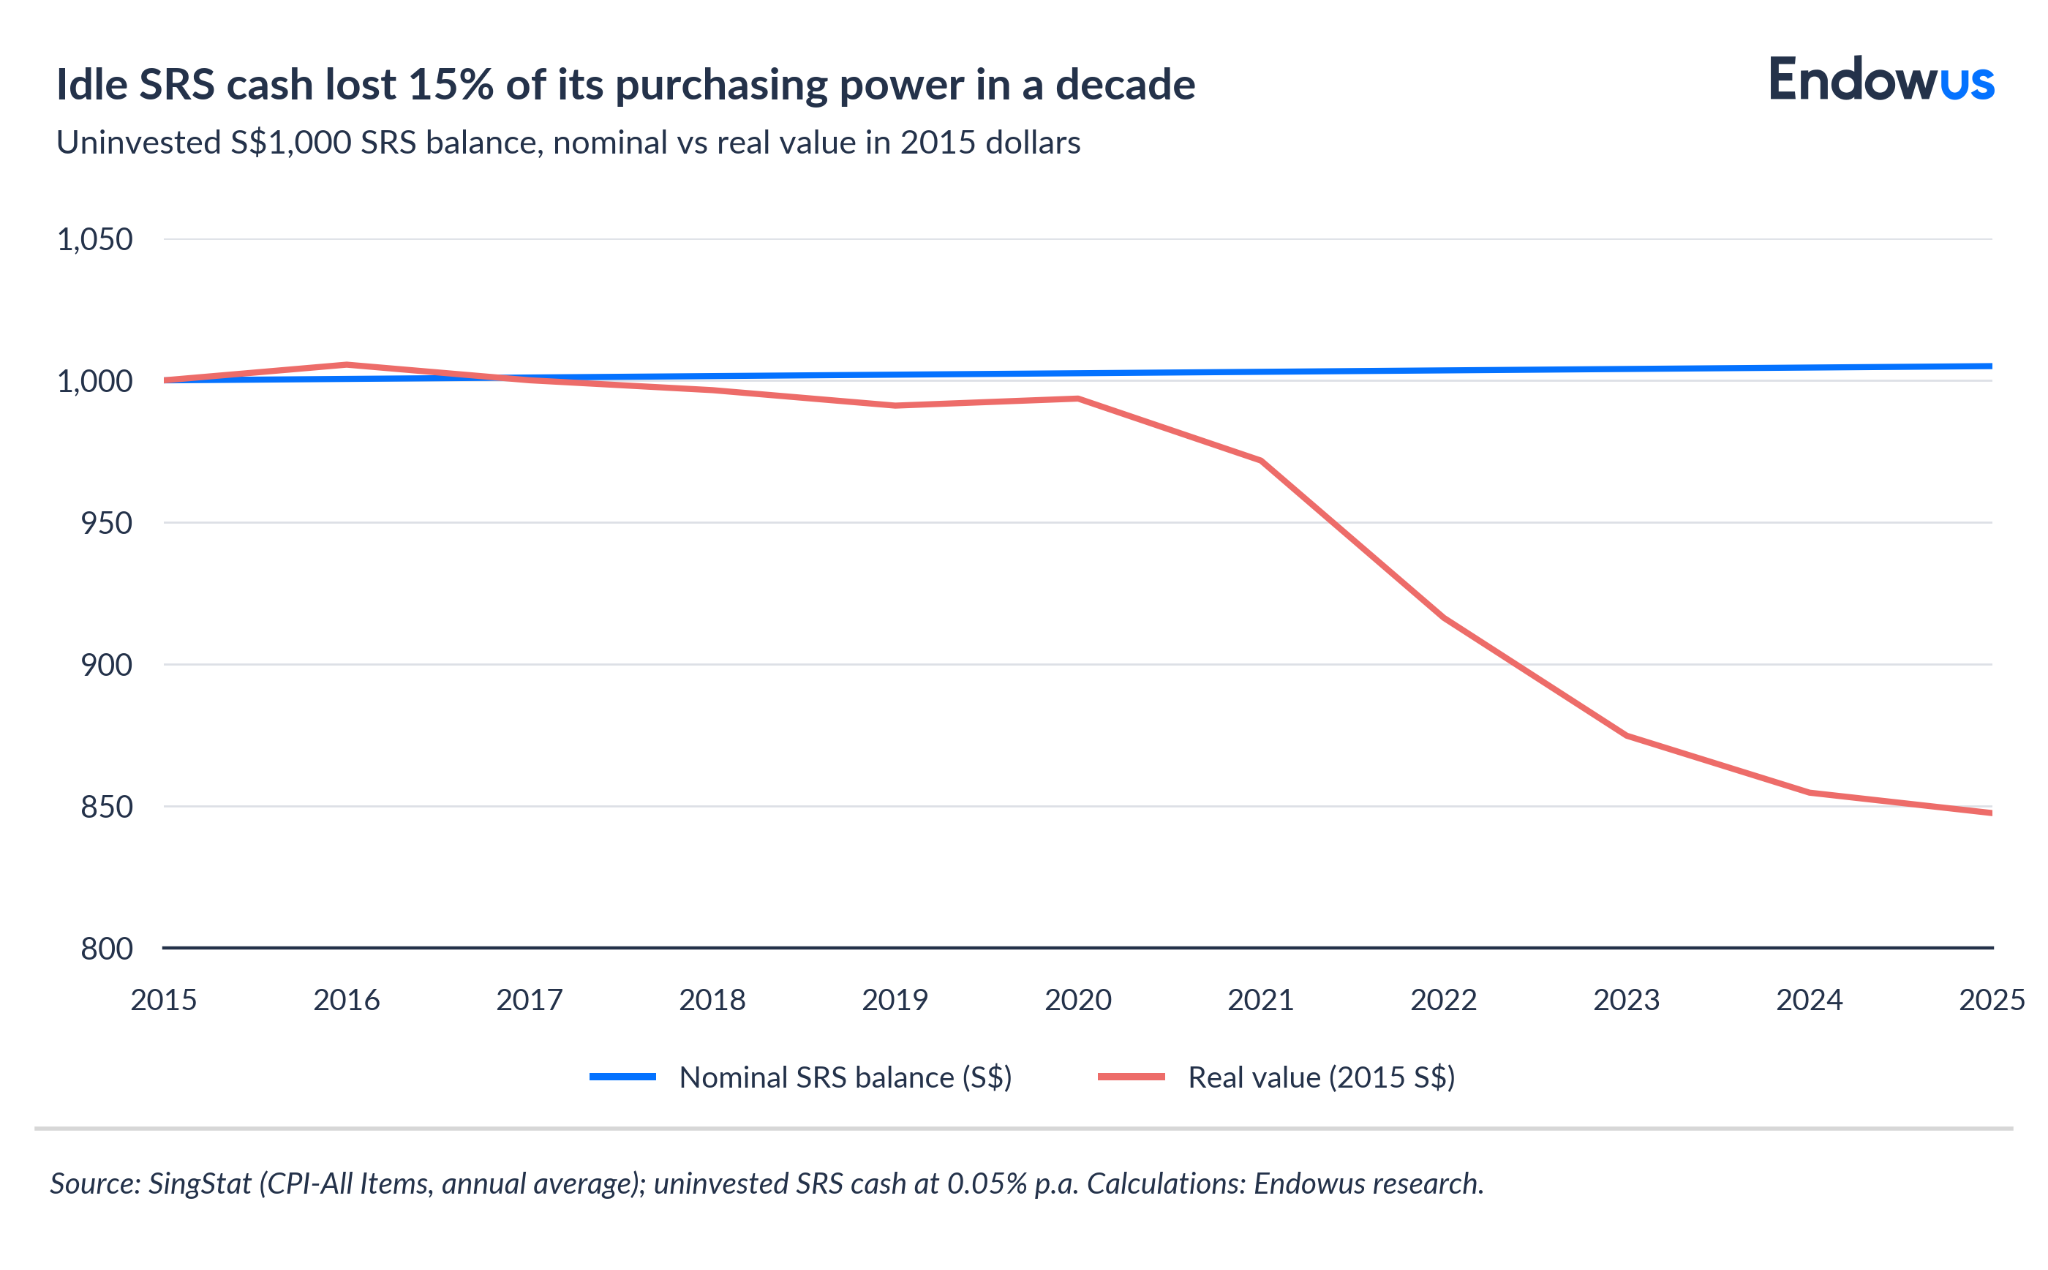
Any balance left sitting as cash inside the account earns almost nothing at 0.05% interest rate per annum, and if you account for inflation, it actually loses money.
For what to do with the money once it is in the account, see our companion guide to the best SRS investment options. Endowus offers one route to invest SRS funds in globally diversified, low-cost portfolios, with trailer fees rebated in full.
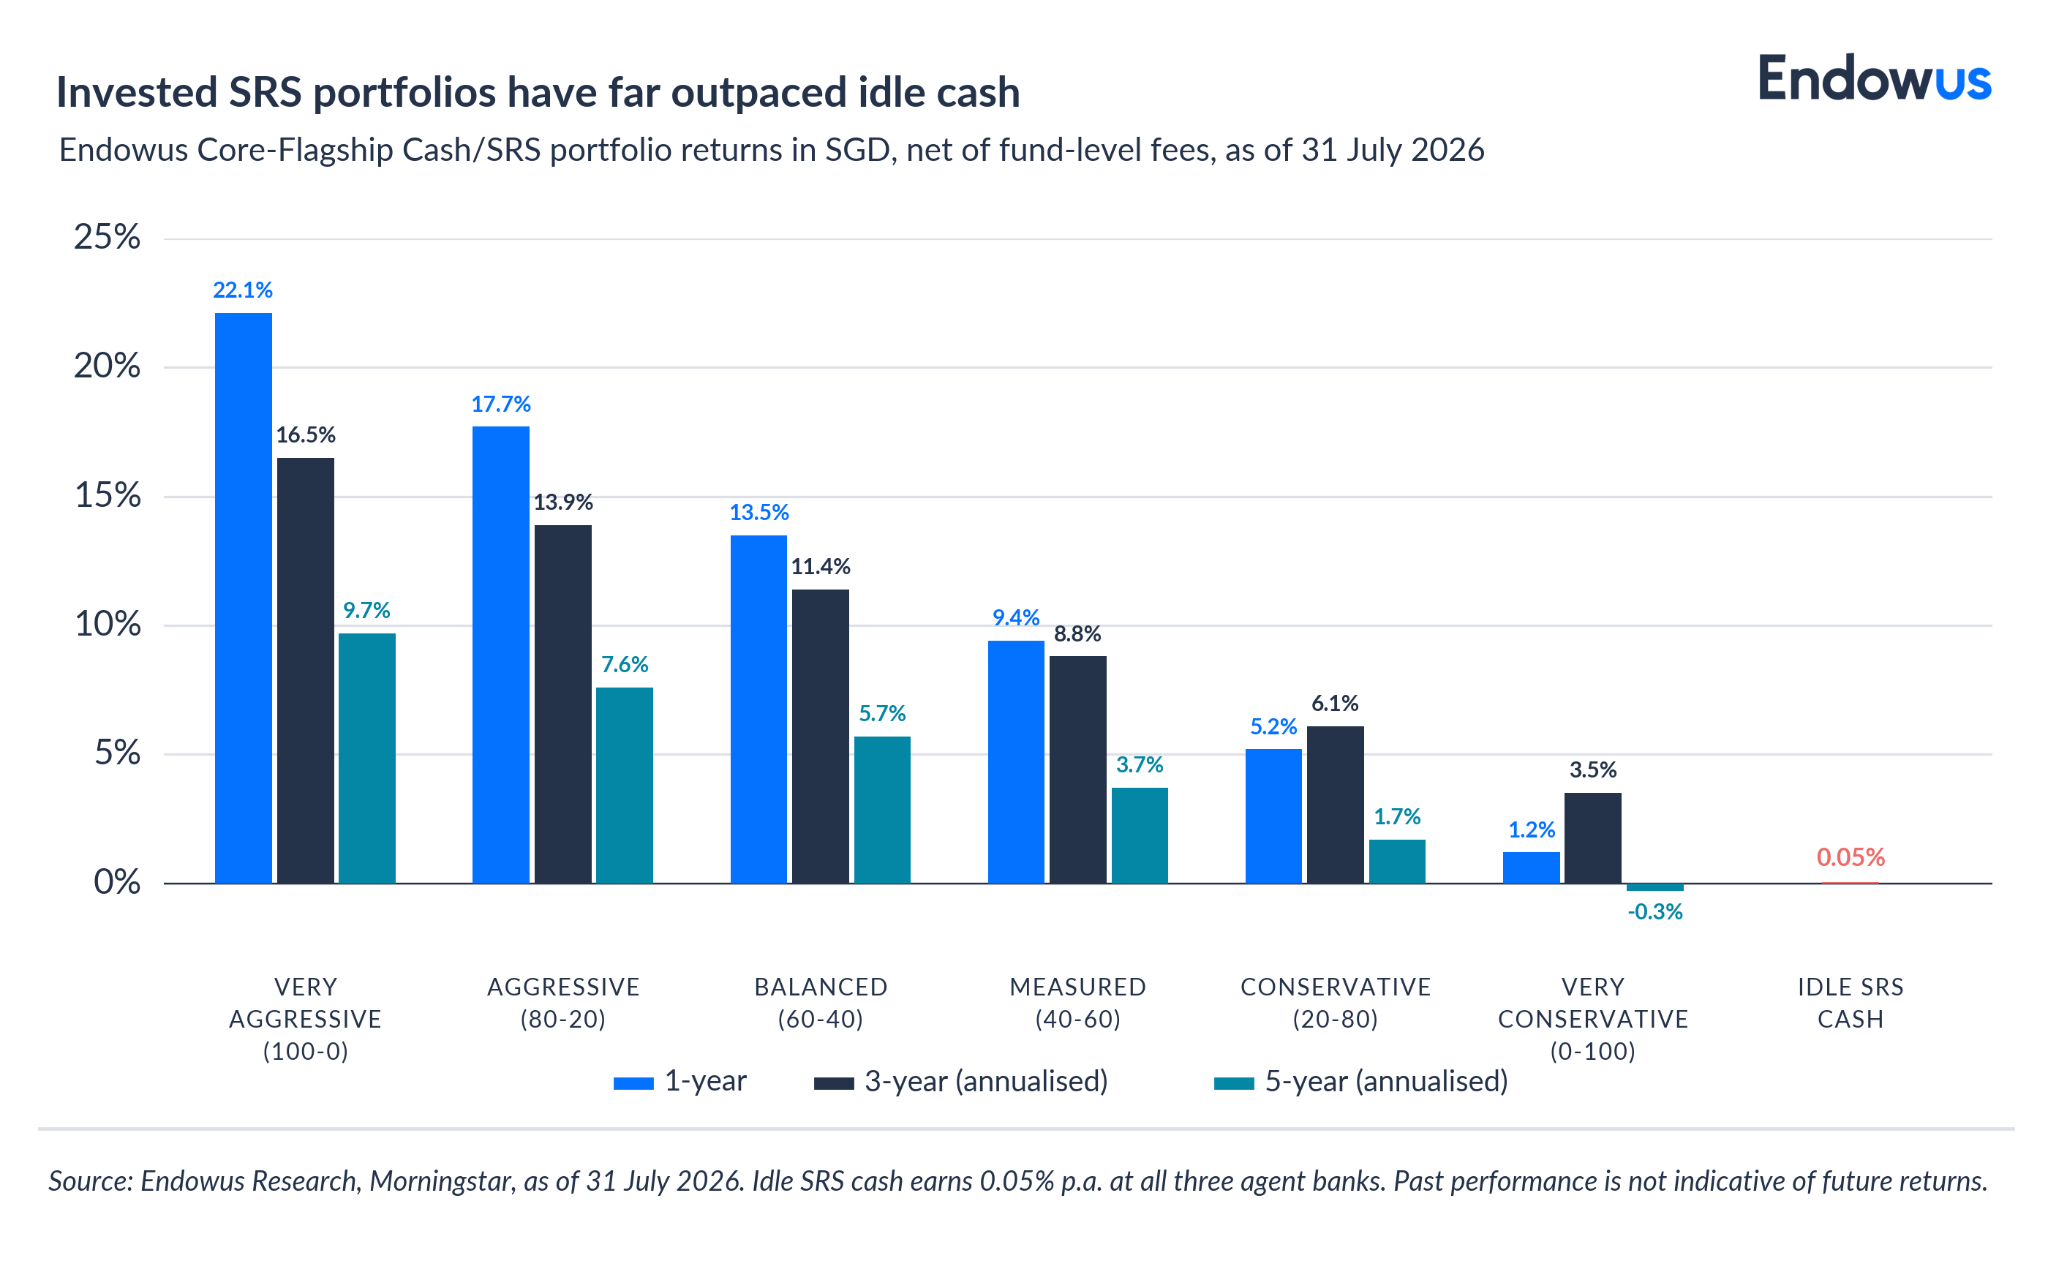
The case to save and invest in SRS, for a foreigner, is real but rests on some conditions. On one hand, the S$35,700 cap and the immediate relief make it one of the few levers to compress a Singapore tax bill during a foreign posting, and potential returns from investments compound untaxed until the money comes out (tax deferral).
On the other hand, the same features that make entry attractive—the deferral, the 24% withholding, the 10-year clock—mean the scheme penalises an unplanned exit.
In our view, the decision for SRS contribution is less important than two other decisions that should follow: which financial instrument to invest in (a contribution claimed for the relief and then left idle can be a missed opportunity), and whether the exit will be timed with the withdrawal rules in mind.
Frequently asked questions about SRS for foreigners
What is the SRS contribution limit for foreigners in 2026?
S$35,700 a year, compared with S$15,300 for Singapore citizens and permanent residents. Contributions must be made by 31 December to qualify for that year’s tax relief.
Can a foreigner claim SRS tax relief without being a Singapore tax resident?
The relief reduces chargeable income, so it produces a cash benefit only for those taxed on the resident progressive scale. Income taxed at a flat non-resident rate does not benefit in the same way, so the value of contributing depends on your residency and how your income is assessed.
Does Endowus offer SRS investing opportunities for foreigners?
Endowus offers one route to invest SRS funds in globally diversified, low-cost portfolios, with trailer fees rebated in full.
What happens to an SRS account when a foreigner leaves Singapore?
If you are no longer a citizen or permanent resident, have left Singapore, and have held the account for at least 10 years from your first contribution, you may withdraw the full balance in one sum, with only 50% of it taxable. The operator withholds tax at 24% at the point of withdrawal, refundable in part once you file.
Is SRS withholding tax the final amount of tax foreigners have to pay?
No. The 24% withheld is a credit against your final assessed tax, not the final liability. A non-resident is taxed at the higher of 15% or the resident progressive rates, and any amount over-withheld is refunded after filing.
What is the penalty for early SRS withdrawal for foreigners?
A premature withdrawal is fully taxable and carries a 5% penalty on the amount withdrawn. The penalty is separate from, and in addition to, the tax due.
Should a new Singapore Permanent Resident make voluntary contributions to CPF accounts?

Understanding the different returns for CPF SA through a MCQ question

Webinar: Tax hacks: Pay less tax with CPF & SRS top-ups