









Register for the event
Endowus invites you to our exclusive event with Macquarie Asset Management, as we discuss unlocking opportunities in Infrastructure- a $1.3tn asset class.
This event is reserved for Accredited Investors (AIs) only. To register for the event, please indicate one of the following:
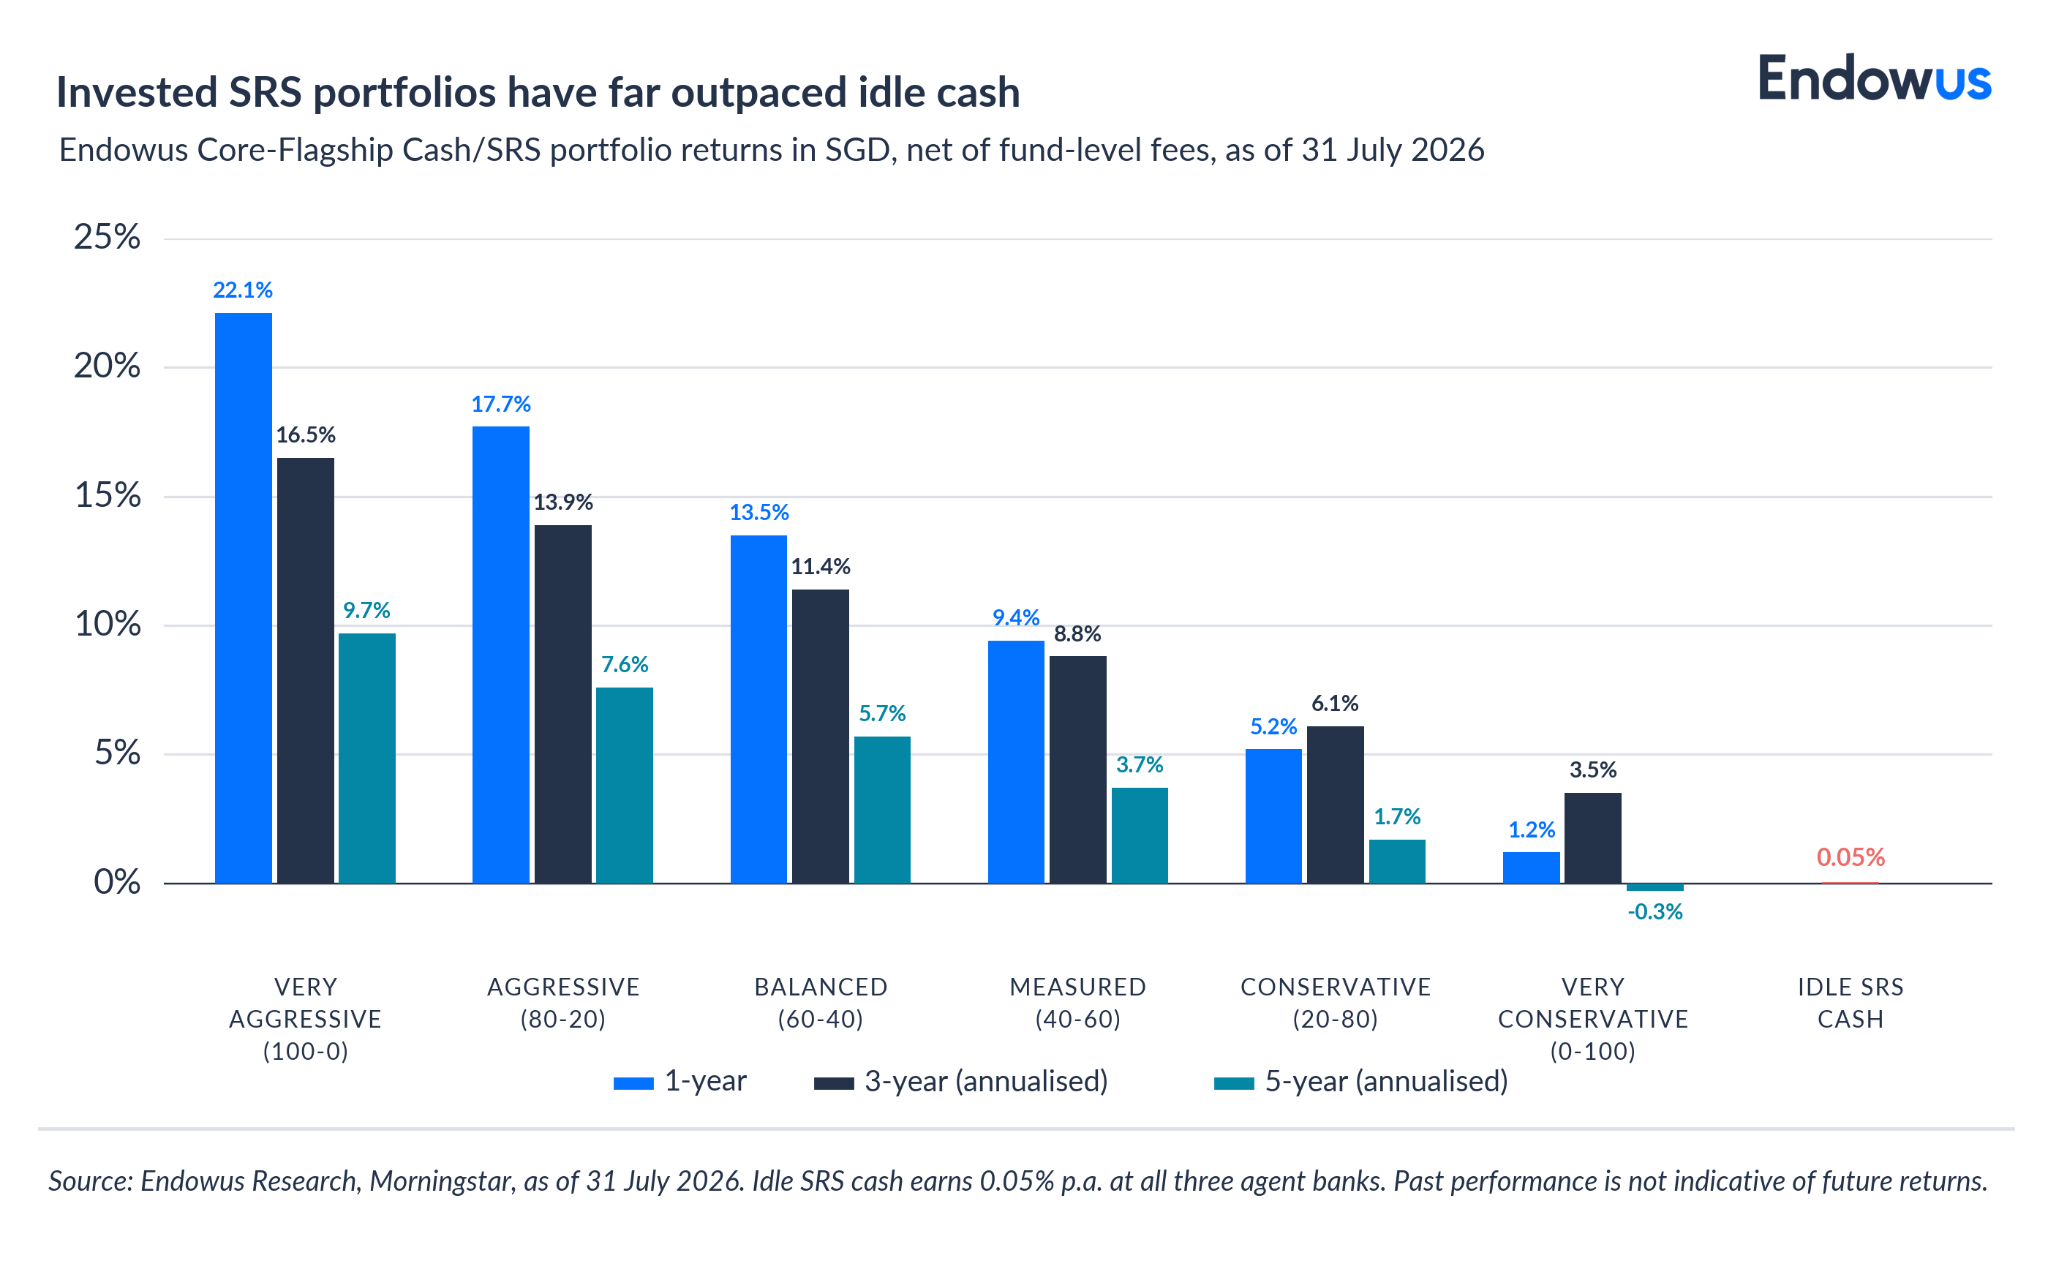
- Uninvested SRS cash earns just 0.05% a year with the operator bank, before inflation, yet at the end of 2025 roughly 21% of all Supplementary Retirement Scheme (SRS) balances were still held as cash, which is a potential net loss.
- The SRS-eligible menu spans safer options (fixed deposits, Treasury bills, and Singapore Savings Bonds) to unit trusts, exchange-traded funds, insurance, and single shares.
- Because SRS is retirement money with a multi-decade horizon for most contributors, matching the instrument to the time horizon matters more than chasing the highest current yield. Over that horizon the gap between cash and a diversified portfolio may compound.
The Supplementary Retirement Scheme (SRS) is an efficient tax shelter available to Singapore residents, but it is often overlooked as an investment scheme.
The inefficiency is what happens after the money is set aside for tax purposes. A large share of SRS money is contributed for the tax relief and then left as cash, potentially losing to inflation despite the very modest (0.05%) return rate. The account banks the tax break at the front end while forgoing the potential compounding that is supposed to justify locking the money away until retirement.
This article maps the full SRS-eligible universe (from fixed deposits and government securities to funds, insurance, and shares) places each by time horizon and risk, and quantifies what the choice between cash and a diversified portfolio may mean over a multi-decade holding period.
Cash is the default, and the default is the problem
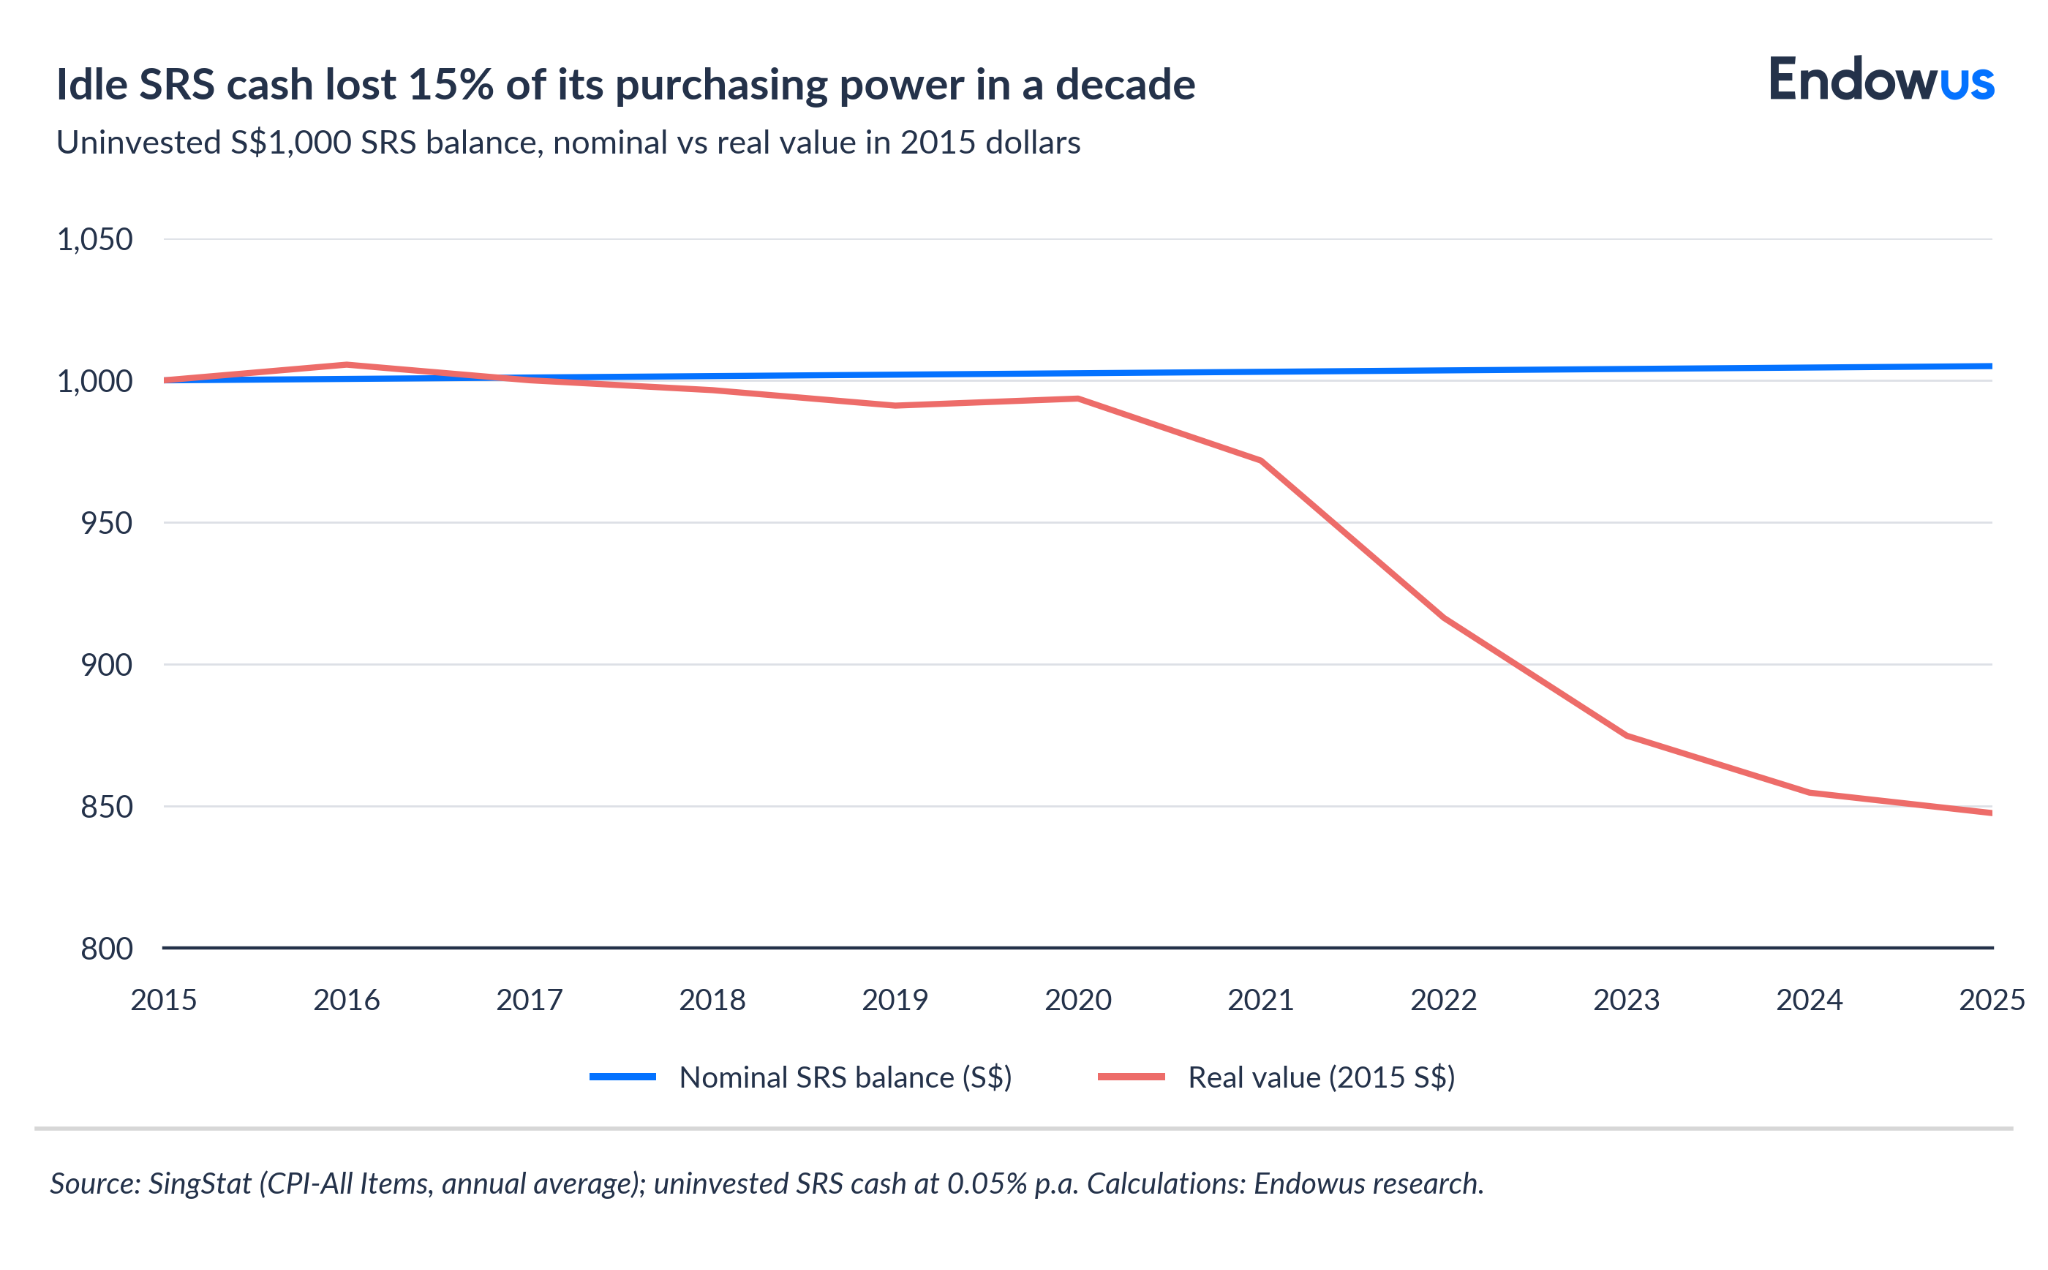
Money contributed to SRS and left uninvested earns 0.05% a year — the base rate the operator banks pay on idle balances - before inflation.
At the end of 2025, cash made up about 21% of all SRS balances, across 516,376 account holders and S$23.88 billion in cumulative contributions. The proportion had risen from 19% a year earlier. In other words, roughly a fifth of the money placed in the scheme for its tax efficiency is earning a return that does not keep pace with inflation.
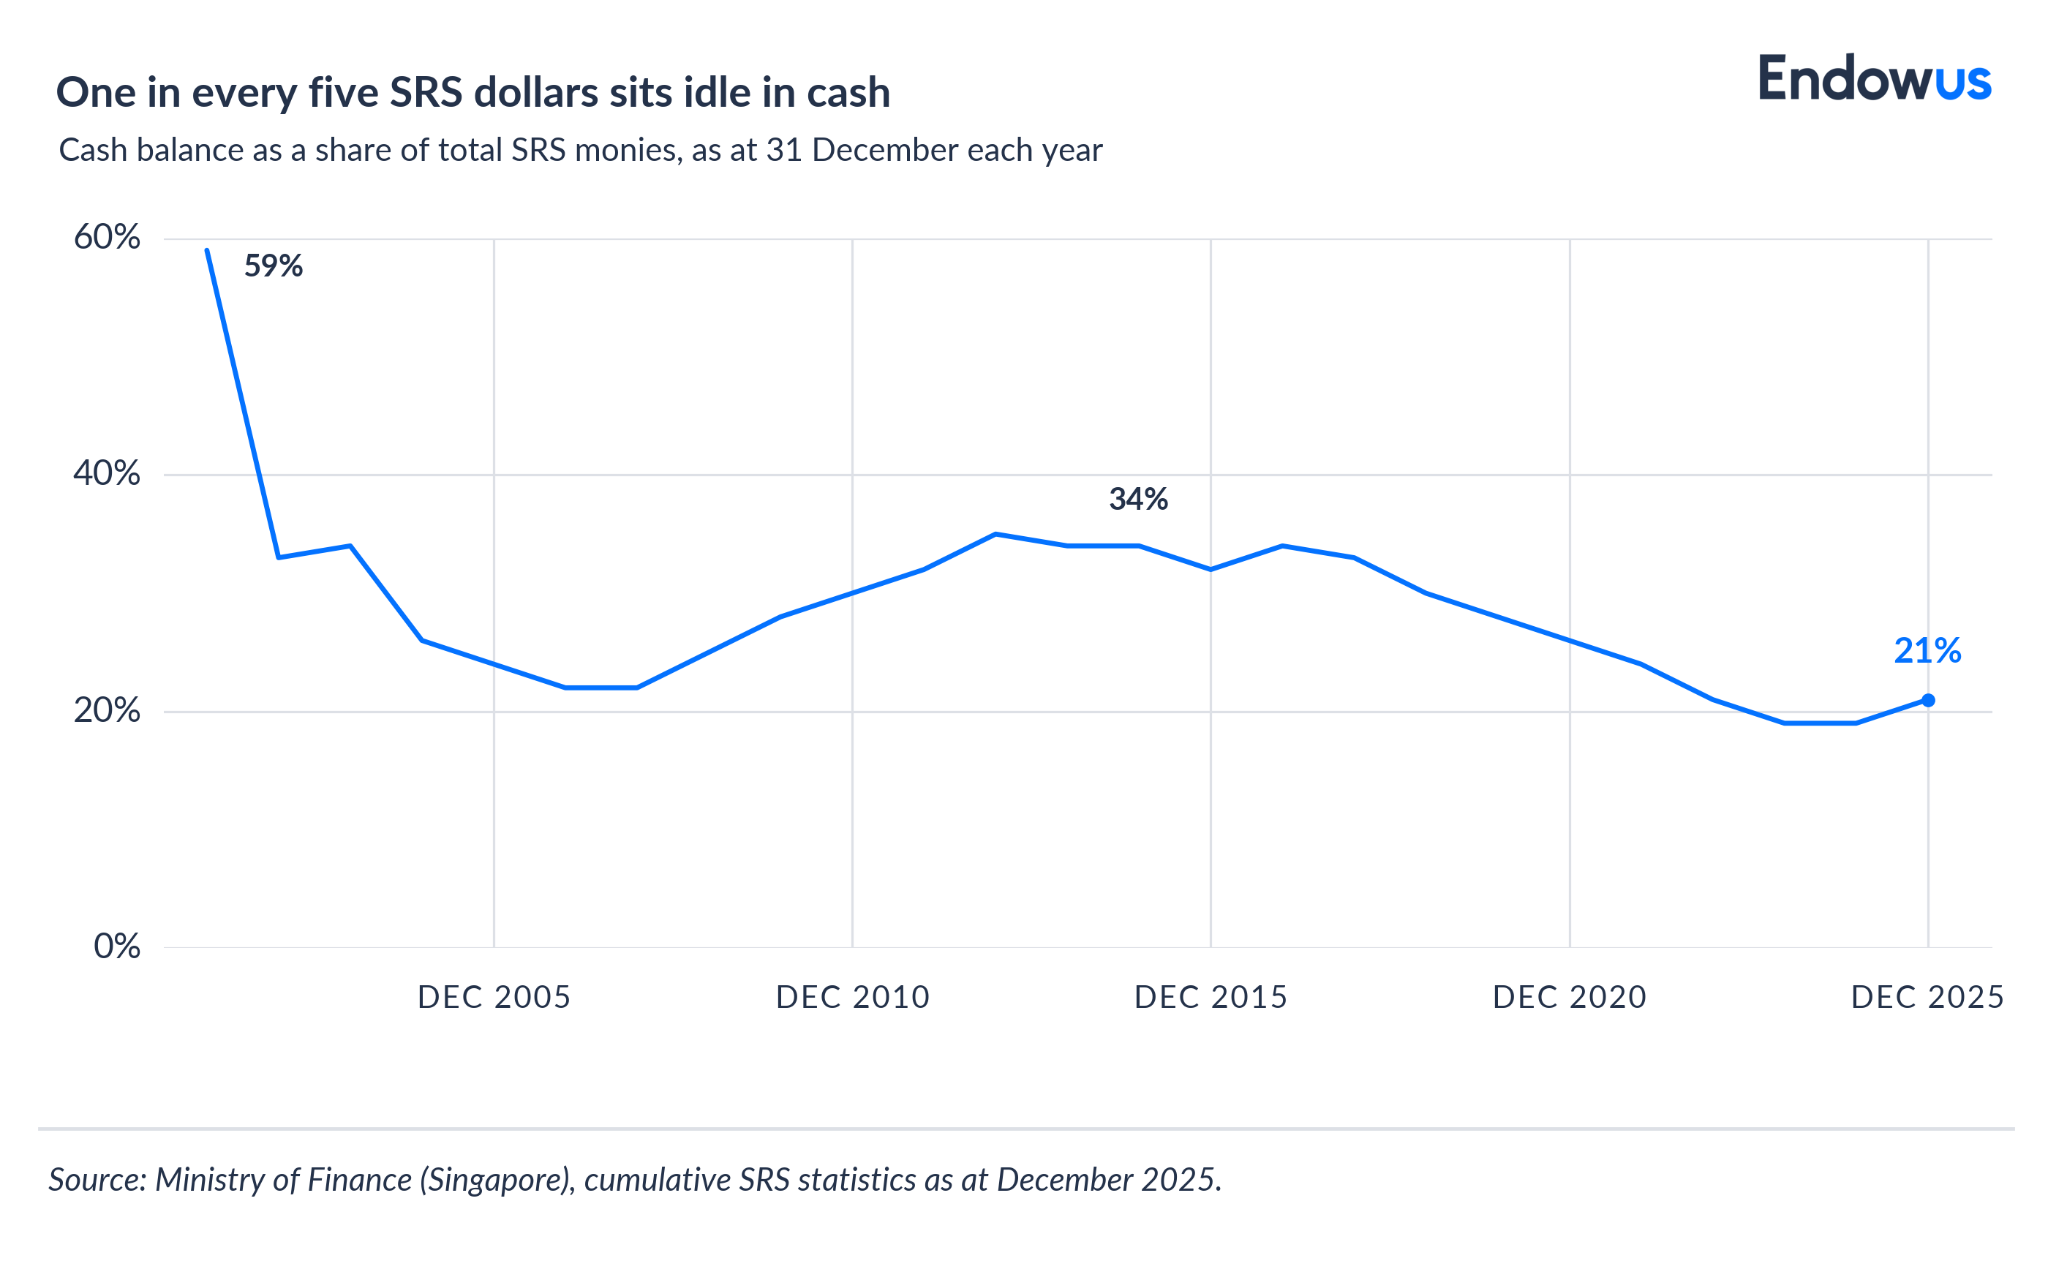
The logic of SRS is a two-part bargain: relief at the front, compounding over time. The relief is banked the moment you contribute. Leaving the balance in cash forfeits the second half, which may turn a modest annual contribution into a retirement sum. But if the second part of the decision is not made, the effect of the tax relief may be offset by inflation destroying value.
Safer options: fixed deposits, T-bills, and Savings Bonds
For contributors who want to preserve capital — because retirement or a departure from Singapore is near, or because a portion of the portfolio is meant to be defensive — there are three bank or government-linked options.
Fixed deposits are the most familiar. SRS funds may be placed on deposit with the operator banks, but the rates offered on SRS deposits differ from the headline promotional rates advertised to the public, which generally exclude SRS money — so the applicable rate should be confirmed directly with the operator rather than assumed from a marketing page.
Singapore Treasury bills (T-bills) are short-dated Singapore Government Securities sold at auction, and SRS holders may apply through the operator bank. The most recent six-month T-bill was issued at a cut-off yield of 1.70% on 15 September 2026, and the latest one-year T-bill cleared at 1.68%.
Singapore Savings Bonds (SSBs) are frequently, and wrongly, assumed to be off-limits to SRS. They are not. SSBs may be bought with SRS funds through the operator’s internet banking portal, with the funds earmarked on application. The October 2026 issue pays 1.65% in the first year, stepping up to a 2.32% average over 10 years, subject to the S$200,000 combined holding limit that applies across cash and SRS holdings.
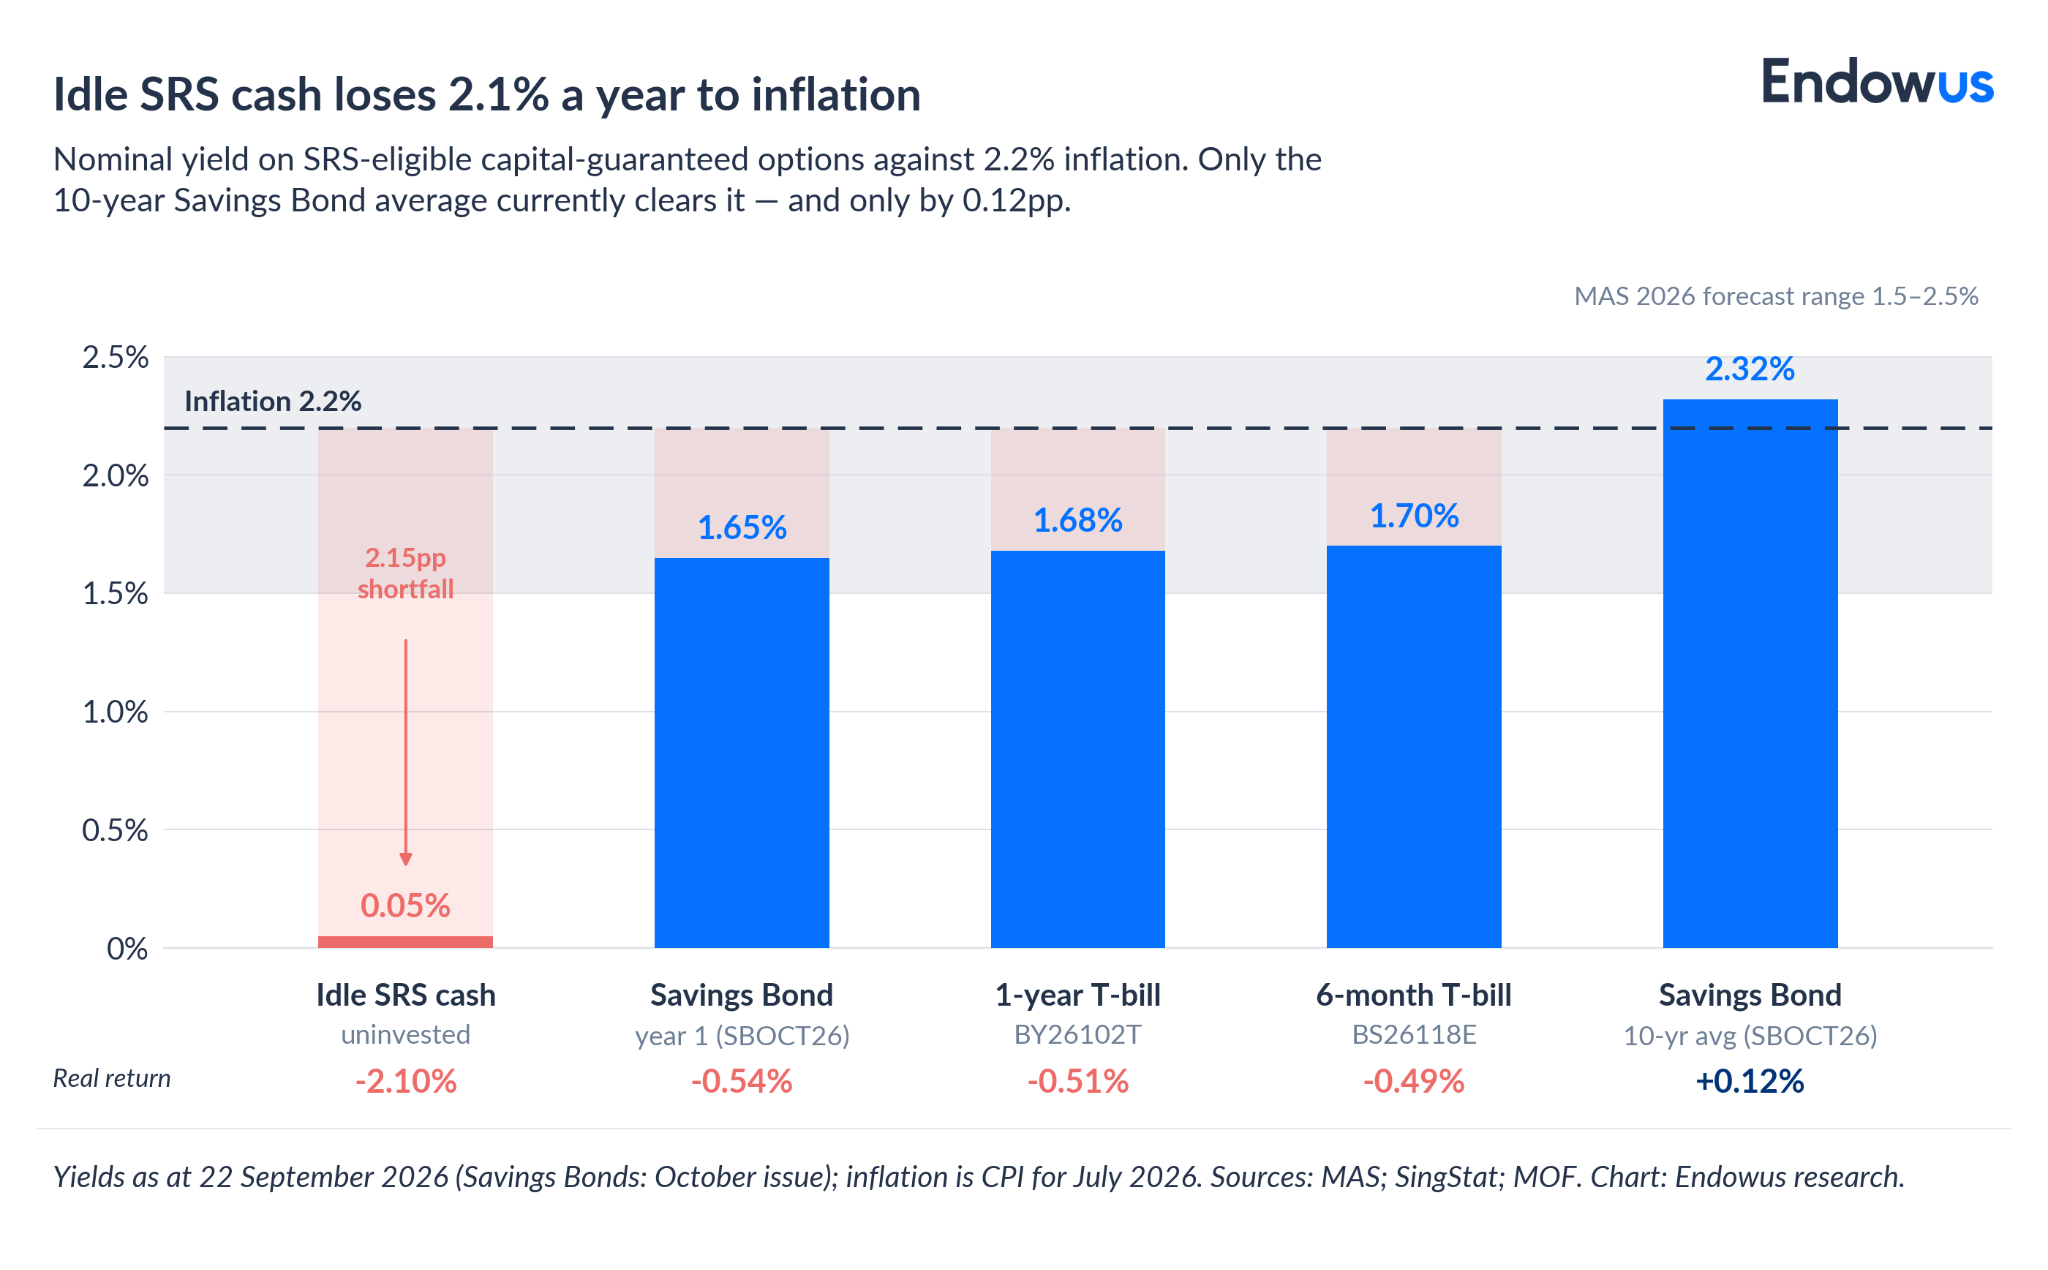
For an individual, the interest on Singapore Government Securities and Savings Bonds is already tax-exempt outside SRS, so holding them inside the scheme adds no further tax efficiency — the reason to hold them there is to keep contributed funds productive and capital-stable, not to shelter interest that is untaxed anyway.
Growth options: unit trusts, ETFs, and shares
Up the risk spectrum, unit trusts and exchange-traded funds (ETFs) can be bought with SRS through digital platforms and brokerages, and individual shares through an SRS-linked brokerage account. These carry market risk and may fall in value, but they also carry higher return potential.
Cost is the variable within a contributor’s control, and it compounds just like returns. Traditional retail fund structures can layer a recurring fund expense of up to around 1.75% a year, an initial sales charge near 1%, and a platform fee. Low-cost platforms that rebate trailer commissions may reduce that drag, which matters more the longer the holding period.
This is the sleeve where the SRS wrapper earns its keep, because untaxed compounding over decades can convert front-loaded tax relief into a materially larger balance.
Insurance: a defined payout, with conditions
Single-premium insurance and retirement plans may also be funded with SRS, and they appeal to contributors who want a defined income stream rather than a market-linked balance. The trade-offs are that life cover is capped at three times the single premium, no trust nomination is permitted over an SRS insurance policy, and the commitment is far less liquid than a fund holding.
Time horizon should drive the choice
The organising principle for an SRS portfolio should not be the best rate on offer this month but the date the money is likely to be needed, measured against the statutory retirement age of 64 (from 1 July 2026).
For a contributor close to retirement, or a foreigner planning to leave Singapore within a few years, locking in an asset or investment product with a known return may be a reasonable use of the account. For a contributor with a long runway, the case for growth assets strengthens, because time is what allows a diversified portfolio’s higher expected return to compound and to absorb interim volatility.
The size of that difference is easy to underestimate. Over 20 years of S$15,300 annual contributions, a balance left in cash at 0.05% barely exceeds the sum contributed, while the same contributions invested at an illustrative 5% a year would grow to roughly S$505,900 — a gap of nearly S$200,000 on identical inputs. And this is before inflation is accounted for.
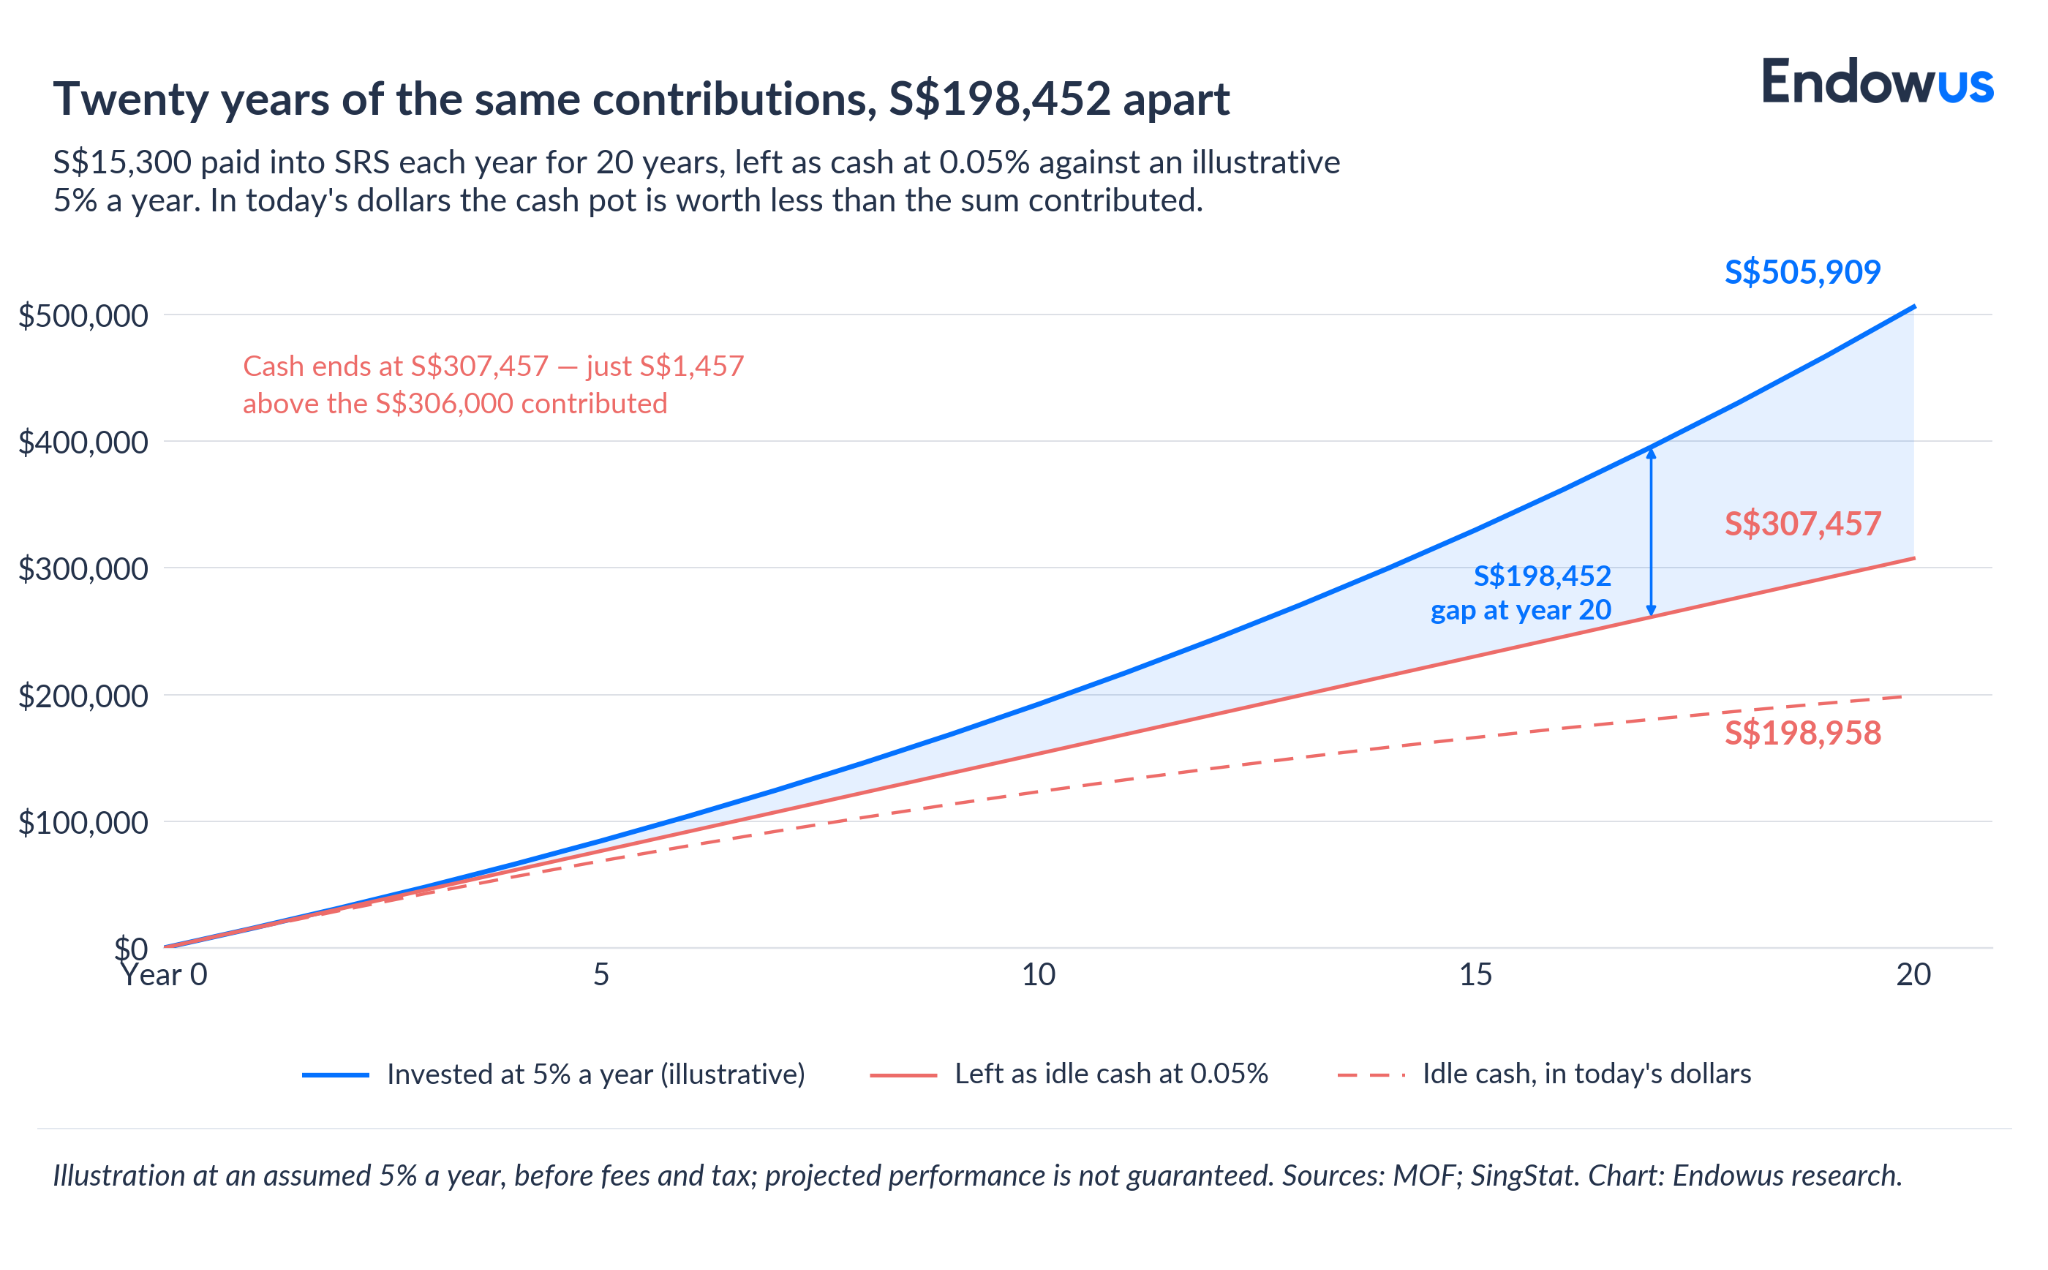
That figure is illustrative, not a forecast: actual returns vary, may be negative, and past performance is not necessarily a guide to future returns.
Investment implications
On one hand, short-dated instruments may be an option for someone near retirement or a near-term departure, who can lock in some relatively safer income compared to investments in unit trusts or stocks. On the other hand, SRS is retirement money that most early contributors cannot withdraw without penalty for years or decades, and over that horizon the return potential of a diversified portfolio, compounding untaxed inside the wrapper may be more attractive.
In our view, the most important action is to invest, and it should be done contextually with the tax saving allocation; the following one would be to match risk to horizon rather than to this month’s best rate. Diversification reduces risk but does not remove it, and no allocation is right for every contributor — but an idle account may lead to the money being lost to inflation.
For the rules that govern who may contribute, how the relief works, and what happens on withdrawal (particularly for foreign professionals) see our companion guide to SRS for foreigners. Endowus offers one route to invest SRS funds in globally diversified, low-cost portfolios, with trailer fees rebated in full.
Frequently asked questions
What are the SRS investment options in Singapore?
SRS funds may be invested in fixed deposits, Singapore Government Securities (Treasury bills and bonds), Singapore Savings Bonds, unit trusts, exchange-traded funds, single-premium insurance, and individual shares — spanning capital-guaranteed options through to market-linked assets. Endowus offers one route to invest SRS funds in globally diversified, low-cost portfolios, with trailer fees rebated in full.
Can I buy Singapore Savings Bonds with SRS funds?
Yes. Despite a common assumption to the contrary, Savings Bonds can be bought with SRS through your operator bank’s internet banking portal, with the funds earmarked on application. The S$200,000 individual holding limit applies across your cash and SRS holdings combined.
What interest does uninvested SRS cash earn?
Uninvested SRS cash earns a mere 0.05% a year, the base rate paid by the operator banks (DBS, OCBC, and UOB), and that is before inflation. It is the same across operators and sits well below what capital-guaranteed alternatives currently offer.
Is an SRS fixed deposit a good option?
A fixed deposit preserves capital and suits a short horizon, but SRS fixed deposit rates can differ from standard deposit rates, which usually exclude SRS funds. Confirm the applicable SRS rate directly with the operator before deciding.
How do I start investing my SRS funds?
Open an SRS account with DBS, OCBC, or UOB, then deploy the funds through a linked investment platform or brokerage that accepts SRS — choosing instruments that match your time horizon and risk tolerance. Endowus offers one route to invest SRS funds in globally diversified, low-cost portfolios, with trailer fees rebated in full.
Endowus CPF Portfolios outperform average returns of CPF Investment Scheme (CPFIS)-included funds in 2020

5 Things to know before investing your CPF

Webinar: Starting your CPF Millionaire journey early