








Register for the event
Endowus invites you to our exclusive event with Macquarie Asset Management, as we discuss unlocking opportunities in Infrastructure- a $1.3tn asset class.
This event is reserved for Accredited Investors (AIs) only. To register for the event, please indicate one of the following:
- On a weighted-average basis, roughly half of STOXX Europe 600 revenue is generated outside Europe, which places European equities closer to a set of globally diversified businesses than to a directional bet on the European economy.
- A concentrated portfolio of 30 to 50 European holdings can carry enough names to diversify away some stock-specific risk while allowing sector, country, and factor exposures to be minimised deliberately rather than inherited from a broad index.
- Because the European single market is smaller than that of the United States, many of Europe’s largest companies must operate globally to reach competitive scale, which may make their international revenue base more structural than cyclical.
When investors weigh an allocation to European equities, many frame the decision as a directional call on eurozone growth. The composition of the market complicates that framing. Many of Europe’s largest listed companies generate a signficant proportion of their revenue beyond Europe’s borders, and a number earn the majority beyond their home region altogether.
The investment case therefore rests less on the European economic cycle than on the global footprint of the businesses that list there. An allocation buys exposure to internationally diversified revenue streams in pharmaceuticals, industrial engineering, luxury goods, and energy technology, delivered through companies with decades of cross-border operating history.
We spoke to Niall Gallagher, Lead Portfolio Manager of Jupiter European Select to discuss where European-listed companies actually earn their revenue, why the structure of the European market pushes them outward, how a concentrated portfolio can capture that exposure while managing portfolio risk, and what the distinction means for an investor constructing a globally diversified allocation.
This article is drafted in collaboration with Jupiter Asset Management.
European-listed companies generate a significant revenue abroad
The STOXX Europe 600 tracks 600 large-, mid-, and small-capitalisation companies across 17 European countries and covers close to 90% of the region’s free-float market capitalisation. Its aggregate revenue is not, however, a proxy for European demand. On a weighted-average basis, roughly half of that revenue is raised outside Europe, according to FactSet GeoRev data cited by STOXX as at 31 March 2026.
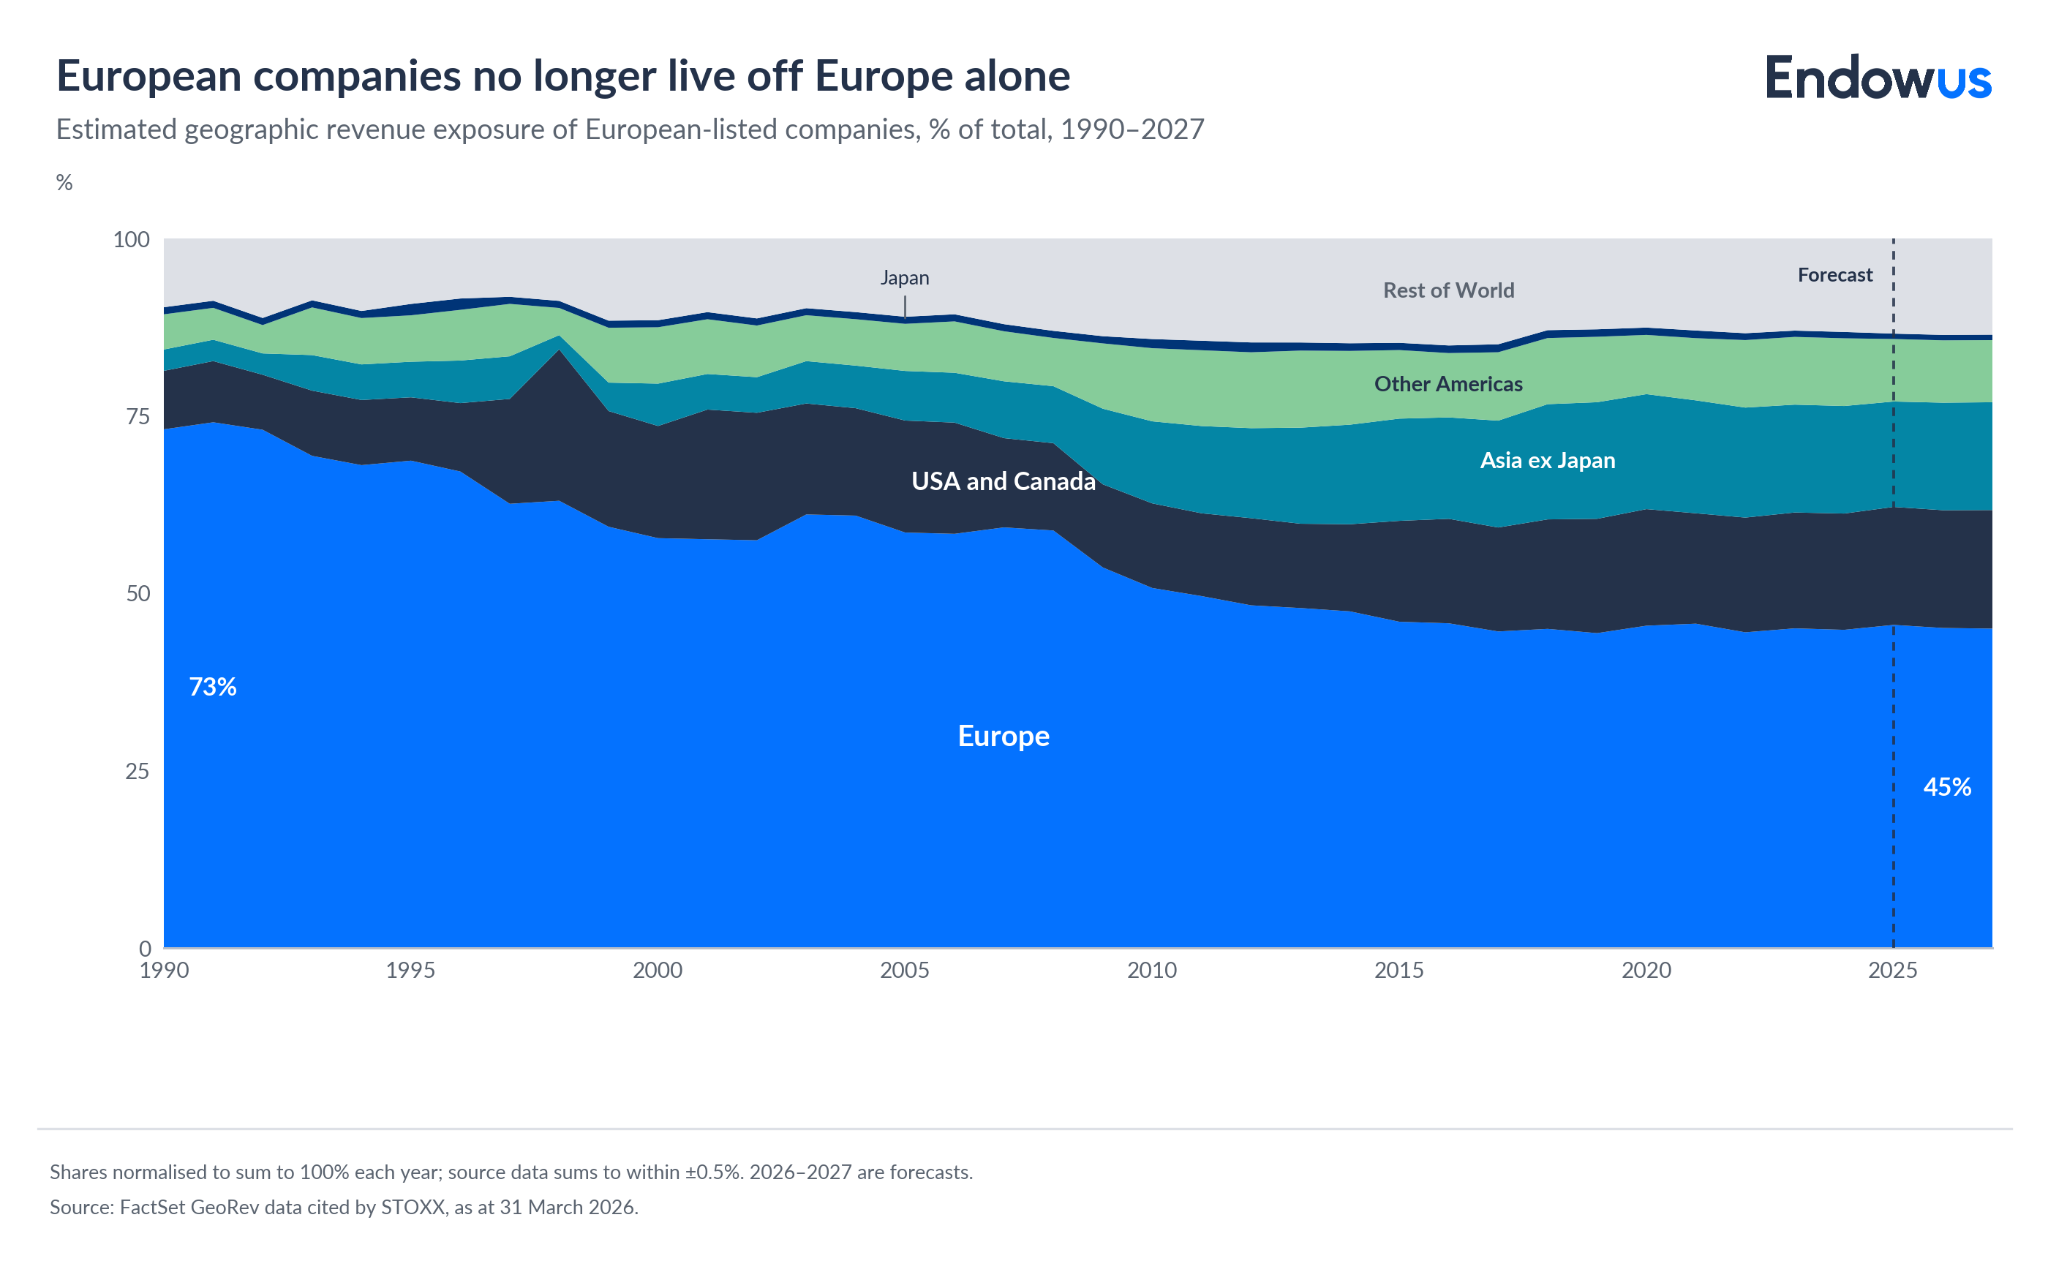
If we look at the components of the index we can get granular. Novartis, the Swiss pharmaceutical group, generated close to 69% of its 2025 net sales outside Europe. Nestle draws its largest single share of sales from the Americas (48%). At LVMH, Asia and the Americas together account for more than half of revenue.
For large European corporations, a globally distributed revenue base is the structural norm. An allocation to European equities can be an allocation to globally diversified companies that happen to be domiciled and listed in Europe.
The structure of the European market pushes companies outward
The European single market is large by any absolute measure. The European Union counted 450.4 million inhabitants as at 1 January 2025. Yet for many multinationals, even a market of that size is insufficient to reach the scale and profitability that global leadership requires.
This is where European and American companies diverge. A large US technology, financial, or industrial company can achieve world scale while generating a substantial share of its revenue at home, because the domestic market is deep enough to support it. That option is less available in Europe. The practical consequence is that the international revenue base of many European companies is embedded in their supply chains, capital allocation, and customer relationships, which may make it more durable than a revenue mix chosen opportunistically.
Why is concentration potentially positive for your portfolio?
A common assumption is that diversification requires owning hundreds or thousands of positions. In practice, even a very broad index can accumulate factor exposures without intent. Momentum, high-beta names, or a handful of mega-caps can come to dominate the behaviour of a portfolio even if it has thousands of names. The result is that what seemingly appears as a diversified portfolio is in fact exposed to a narrow set of systematic risks spread across many tickers.
A concentrated portfolio approaches the problem differently. Research by Meir Statman1 (1987) found that a well-diversified portfolio needs at least 30 to 40 stocks to capture most of the available reduction in stock-specific risk. A portfolio of that size can potentially diversify away the majority of idiosyncratic risk while remaining small enough for each holding to be understood - and well researched - and for sector, country, and factor exposures to be set deliberately.
The distinction matters for how risk is managed. When a manager holds 30 to 50 positions selected through fundamental analysis, the portfolio’s tilts — whether toward value, smaller capitalisations, or specific industrial cycles — are visible and intentional. A very broad index may carry the same tilts, obscured by the number of holdings. A manager applying a disciplined concentration framework may use this transparency to model and control portfolio risk directly, rather than accepting the exposures a broad benchmark happens to produce.
Whether a concentrated portfolio ultimately exhibits lower volatility or better downside behaviour than a broad index is a function of manager skill and remains illustrative rather than assured. It is not a general property of concentration, and no such outcome should be assumed.
European industry is diverse enough that concentration need not narrow exposure
Concentration at the portfolio level need not imply concentration of economic exposure, because European industry is itself diverse. Germany leads in industrial machinery, automotive components, and chemicals. Switzerland is home to global leaders in pharmaceuticals and specialty ingredients; chemicals and pharmaceuticals accounted for around 52% of Swiss exports in 2024. France is strong in luxury goods and aerospace. The Nordic region has developed depth in industrial technology, automation, and software. The United Kingdom hosts leaders in financial services, pharmaceuticals, and consumer goods. Italy specialises in premium and design-led manufacturing.
This breadth means that a portfolio of 30 to 50 European holdings can span several independent economic themes at once: the energy transition, through industrial and renewable-technology manufacturers; demographic ageing, through pharmaceuticals and healthcare; digitalisation, through automation and software; and global consumption, through multinational consumer and luxury companies. The natural variety of European industry allows a concentrated portfolio to remain diversified across drivers that actually move returns.
Investment implications
The most common case for European equities is cyclical: that valuations are inexpensive, or that the region is due a recovery. Arguments of that kind date quickly and depend on the accuracy of a macro forecast. The structural case is more durable. European-listed companies generate a large share of their revenue outside Europe, and that exposure can be held in a concentrated portfolio whose diversification comes from the underlying earnings streams rather than from the number of holdings or the breadth of geographic labels.
For an investor with conviction in global industrial growth, the energy transition, and infrastructure — themes that do not depend on European domestic performance — a considered allocation to quality European equities may offer more authentic diversification than a mechanically broad one. In our view, the more important point is one of construction: diversification is better sourced from what companies do than from how many of them a portfolio holds.
On one hand, a concentrated European allocation may deliver genuine global diversification alongside intentional control of sector and factor exposures. On the other, concentration raises the importance of manager skill and security selection, and European-listed companies remain subject to currency movements, regulatory change, and shifts in global demand that no allocation can remove. Sizing the position to its role within a broader portfolio, rather than treating it as a directional bet on Europe, is the discipline that matters.
For investors using Endowus, our advisers can help determine whether and how much European or global equity exposure suits your objectives, time horizon, and risk profile.
Endowus offers access to Jupiter’s European equities strategy on the Fund Smart platform, in three currencies: SGD, EUR and USD. Speak with an Endowus adviser to understand how European equity exposure may fit your broader financial plan.
Frequently asked questions
Are European equities a bet on the European economy?
Not primarily. Most of the largest European-listed companies earn the majority of their revenue outside Europe, so their earnings track global demand more closely than eurozone growth. An allocation to European equities is closer to owning globally diversified businesses than to taking a directional view on the European economy.
How much of European companies’ revenue is earned outside Europe?
On a weighted-average basis, roughly half of STOXX Europe 600 revenue is generated outside Europe, according to FactSet GeoRev data cited by STOXX as at 31 March 2026. The exact share varies with the index and methodology used.
Does holding a concentrated portfolio mean taking on more risk?
Not necessarily. Research by Meir Statman (1987) indicates that a portfolio of 30 to 40 stocks can diversify away most stock-specific risk. A concentrated portfolio can therefore remain diversified against idiosyncratic risk while allowing sector, country, and factor exposures to be managed deliberately. Whether it carries more or less overall risk than a broad index depends on how it is constructed and managed.
How can investors in Singapore gain exposure to European equities?
Common routes include exchange-traded funds that track European indices and actively managed European or global equity funds. On the Endowus platform, investors can access advised portfolios and actively managed strategies with European exposure, and can speak to an adviser about how such exposure fits a broader allocation.
What risks should investors consider?
Key risks include currency movements between the euro, other reporting currencies, and the Singapore dollar; regulatory and policy change across the markets these companies serve; sensitivity to global demand; and, for concentrated strategies, greater dependence on manager skill and security selection. Investors should weigh these against their own circumstances.
1Journal of Financial and Quantitative Analysis, Volume 22, No.3, September 1987. “How Many Stocks Make a Diversified Portfolio” - Meir Statman.